Forward Air Crushes EPS Estimate As EBITDA Keeps Climbing, But A Paused Intermodal Sale Leaves Leverage At The Center Of The Story
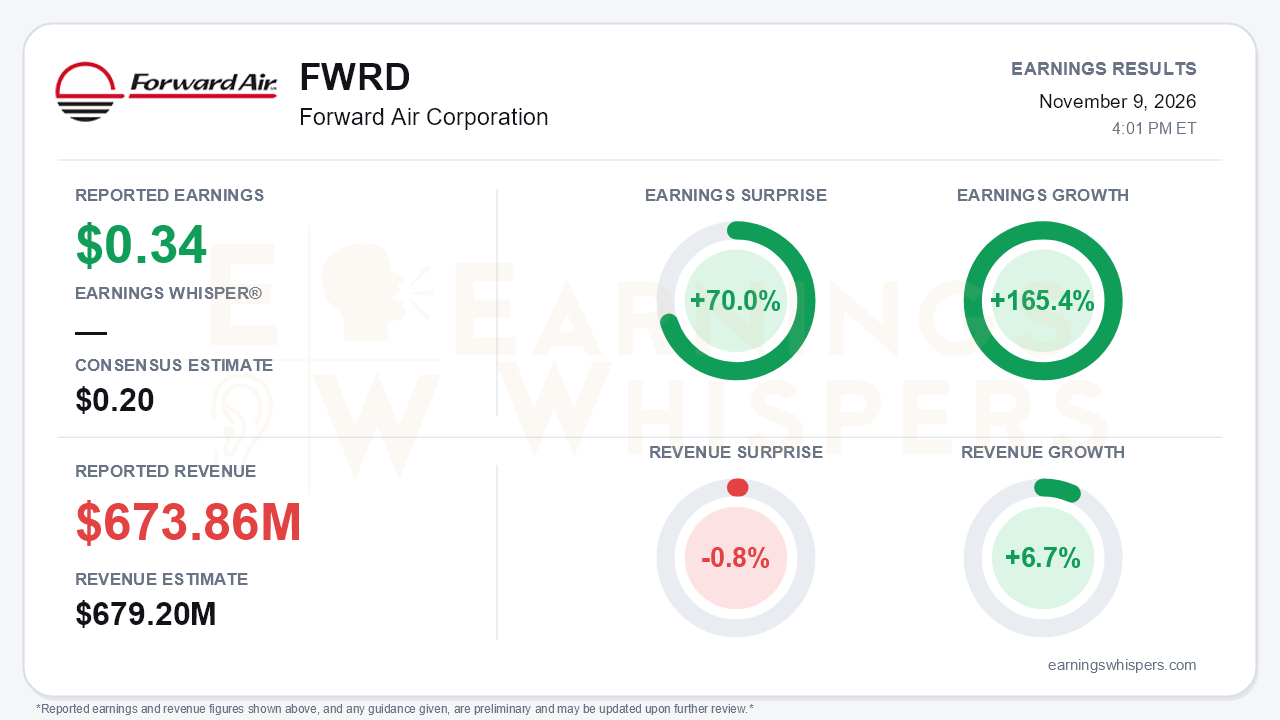
Forward Air delivered the kind of quarter turnaround skeptics were not positioned for. Third-quarter earnings of $0.34 per share beat the $0.20 consensus by 70.0%, a swing from a $0.52 loss a year ago that equates to 165.4% earnings growth. Revenue of $673.86 million was a company record for the second straight quarter and grew 6.7% year over year, though it fell 0.8% short of the $679.2 million consensus. The central takeaway is that operating earnings power is improving quarter after quarter. Consolidated EBITDA has stepped from $70 million in the first quarter to $93 million in the second and $101 million in the third. The balance sheet remains the constraint on how much of that improvement reaches shareholders.
The quality of the EPS beat deserves scrutiny. Operating income nearly tripled to $43.9 million, and operating margin widened 410 basis points to 6.5%. Even so, $44.1 million of net interest expense consumed essentially all of it. Pretax income from continuing operations was only $9.1 million, and roughly $6.8 million of net gains on business dispositions flowed through other income. Without those gains, GAAP profit would have been close to breakeven. Cash generation also lagged earnings. Operating cash flow fell to $35.3 million from $52.7 million, and free cash flow dropped to $33.3 million from $48.9 million, largely because receivables rose $36 million. Year-to-date operating cash flow of $76 million still tops last year's $67 million. Liquidity improved to $446 million, but long-term debt sits near $1.7 billion and shareholders' equity is now a deficit of about $109 million after this year's $244 million goodwill impairment.
Beneath the headline, the operating story is genuinely better. Expedited Freight revenue jumped 30.5% and operating income rose 87.5%, with the operating ratio improving to 89.2% from 92.5%. Shipments per day grew 7.9% and weight per shipment 6.9%, a sharp reversal from tonnage declines earlier in the year. Management said the network still has 15% to 18% spare capacity and has added more than 50 owner-operators this year, so volume can grow without proportional fixed cost. Two caveats apply. Revenue per hundredweight excluding fuel slipped 2.6%, and purchased transportation climbed to 53.2% of segment revenue from 48.4%, as truckload revenue surged 59.3%. At Omni, revenue fell 8.0% as Ground dropped 35.6%. Contract Logistics grew 12.3% and Air and Ocean 24.9%, and the segment's EBITDA margin improved to 11.3% from 9.6%. Intermodal posted its best revenue in more than three years on a 14.1% rise in drayage revenue per shipment.
The most consequential development was the definitive two-year agreement with the major customer whose roughly $250 million of business was at risk in the first quarter. Under the second-quarter memorandum of understanding, Forward expected to retain at least half and up to 75% of that revenue. Management now expects retained-service revenue to exceed the customer's full 2025 total and to keep growing into 2027, turning a loss scare into a growth account. Net leverage fell below 5x, about a turn lower year over year. The offset is real, however. The Intermodal sale, previously expected to close by year-end, is paused because bids fell short of management's aspirations, and that delays deleveraging proceeds. The transition of the non-retained customer services runs from November through March 2027. Management also flagged fourth-quarter seasonality and fewer working days, and it still offers no formal guidance or margin targets. Omni EBITDA dipped sequentially to $35 million from $38 million, and Intermodal margin eased to 14.3% from 16.7%. Bears have legitimate ammunition on cash flow and the balance sheet, even if the operating trend favors the bulls.
Investor expectations had already started to shift. Earnings Whispers sentiment moved from -0.117 after the prior report to +0.113, a modest but meaningful flip from mildly negative to mildly positive. The stock has not followed. Shares entered the report at $16.64, down 5.9% from the $17.69 opening after the August release and 4.6% below the 200-day moving average. They have given back much of the run to the $20.57 inter-earnings high set on August 13, sitting 19.1% below that peak while holding 18.0% above the September 21 low of $14.10. The internal trend readings are mixed, with momentum positive while AVWAP remains negative.
The bottom line is that Forward Air's operating recovery is real and broadening. EBITDA is rising sequentially, expedited volumes are accelerating into spare capacity, and the customer overhang has been converted into a retained relationship. The EPS beat, however, owes a meaningful share to divestiture gains, interest expense still absorbs nearly all operating income, and the paused Intermodal sale removes a near-term deleveraging lever. With shares below their 200-day average despite improving sentiment, the market appears to want proof that EBITDA growth will translate into cash flow and debt reduction before it pays for the turnaround.
Read our earnings preview for Forward Air Corporation: https://www.earningswhispers.com/article/FWRD/22627
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Nov-10 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-02 | |
| Oct-28 | |
| Oct-28 | |
| Oct-15 | |
| Oct-01 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 |
