AMC Global Media's Lopsided Beat: Tax-Aided Adjusted EPS Overshadows A Revenue Miss And A Steep Q4 Bar
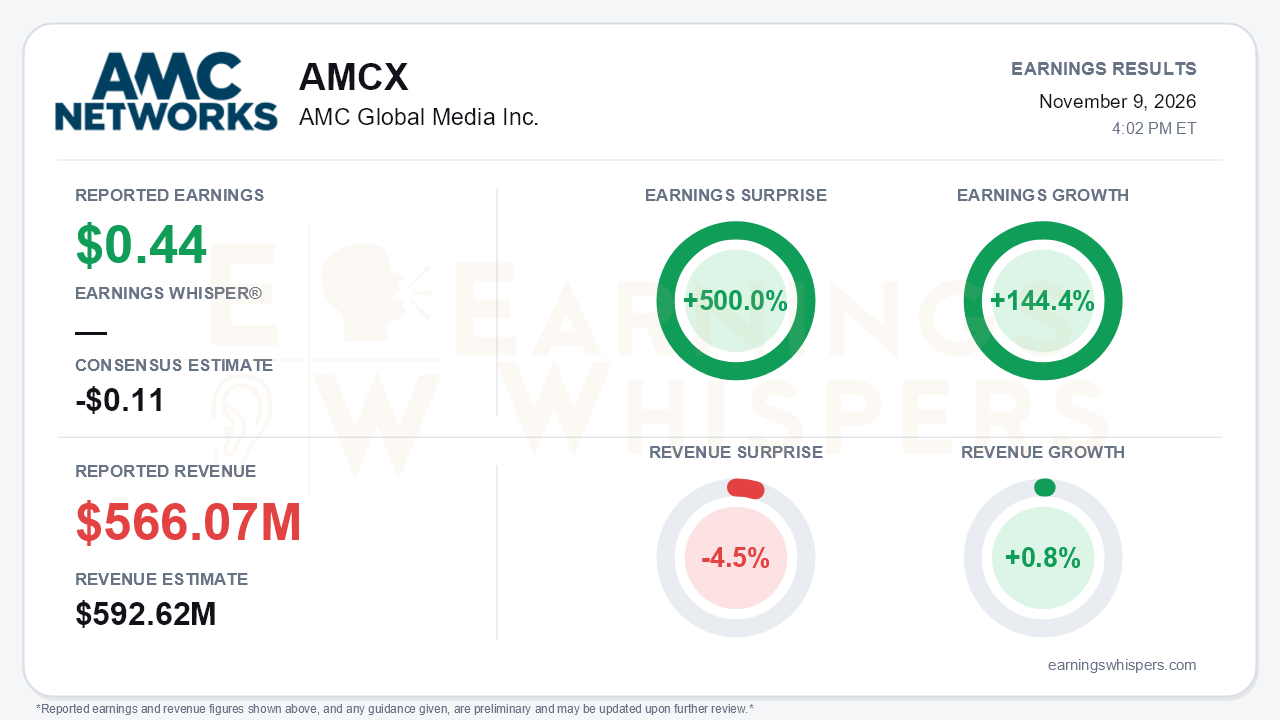
AMC Global Media (NASDAQ: AMCX) posted adjusted earnings of $0.44 per share for the September quarter, far ahead of the consensus estimate for a $0.11 loss. That is a 500.0% surprise and 144.4% year-over-year earnings growth. The top line told a different story. Revenue of $566.07 million rose just 0.8% and missed consensus by 4.5%. On a GAAP basis, the company swung to a $(1.13) per-share loss from a $1.38 profit a year ago, driven by an $85 million charge to settle the long-running Walking Dead litigation. The central tension is that the earnings beat looks far stronger than the operating performance beneath it.
The quality of the beat deserves scrutiny. Adjusted pre-tax income was only $9.9 million, down from $31.1 million a year earlier. Adjusted net income of $25.0 million was lifted by a $16.5 million income tax benefit. Operating profitability is still falling. Consolidated Adjusted Operating Income dropped 25.4% to $70.4 million. Domestic segment AOI fell 21% to $89 million as technical and operating expenses climbed to $314 million from $291 million. Domestic revenue grew 2%, but much of that came from a 42% jump in content licensing to $84 million. The company attributed that gain to the timing of deliveries, which is not a recurring driver. Core lines remained under pressure:
- subscription revenue fell 2.5%;
- domestic advertising declined 6.9% on lower marketplace pricing;
- International revenue dropped 5%, or 4% excluding currency.
The conference call nonetheless preserved a credible stabilization narrative, especially when viewed sequentially. Consolidated revenue growth improved to +1% from -9% in Q2 and -2% in Q1. Affiliate declines narrowed to -11% from -17% and -16% as new distribution agreements took effect. AOI recovered from the $46 million Q2 trough. Management reaffirmed full-year guidance of $2.40 to $2.45 billion in revenue and $410 to $420 million in AOI, the targets it raised in Q2. It held those targets despite selling ALLBLK, a business it described as profitable. Other operating points were also constructive:
- hours per active user rose sequentially and year over year;
- retention held despite price increases;
- advertising commentary improved, citing a successful upfront, scatter and digital demand, political spending, and more than a dozen sponsorships tied to Thunder Road and Point Break.
Several trends still cut the other way. Streaming growth keeps decelerating, from 11% in Q1 to 6% in Q2 and 4% in Q3, or 7% excluding ALLBLK. International AOI margin slipped to 14% from 18% in Q2. Management still expects the full-year affiliate decline to resemble 2025's roughly 13%.
The forward catalysts center on AMC's studio pivot. The Netflix relationship moved beyond the earlier $500 million Walking Dead license in two ways:
- a co-production and co-ownership model, with the spy drama Bannerman as the first greenlight;
- Netflix's purchase of The Headlands House.
The full Walking Dead universe arrives on AMC+ on January 7, and the settlement removes a litigation overhang. The cost is visible in cash flow. Q3 free cash flow was $(52) million, or $33 million excluding the settlement. Full-year FCF guidance now sits near $150 million, down from about $220 million, with a further $35 million advance due by January. Management characterized the underlying view as roughly unchanged. Net debt stands at $1.30 billion and leverage at 4.5x, so cash generation still matters.
The guidance also carries an implied burden. With $1.66 billion in revenue and $185 million in AOI through nine months, the full-year targets require roughly $745 to $795 million in Q4 revenue. They also require about $225 to $235 million in Q4 AOI, more than the first three quarters combined. Investors are effectively being asked to trust heavy fourth-quarter content deliveries. Bears have legitimate ammunition if that timing slips.
The market has been skeptical. Shares entered the report at $8.39, down 6.5% from the open after the July report. The stock had spiked to a 52-week high of $12.93 in late August, then gave back that entire move and touched $7.31 in late October. It now sits 11.5% below its 200-day moving average, though 14.8% above that recent low. Investor sentiment remained slightly negative but improved modestly, from -0.063 to -0.036, which falls short of a meaningful shift in conviction. The Earnings Whispers trend signals are mixed, with price and AVWAP readings negative while momentum is positive.
The bottom line is that AMC Global Media delivered a headline beat with substantial asterisks. The adjusted EPS outperformance leaned on a tax benefit, revenue missed, and AOI fell by a quarter year over year. Still, the sequential direction improved: affiliate erosion eased, revenue returned to growth, and reaffirmed guidance with a deepening Netflix partnership gives the studio strategy real substance. Whether this quarter marks a durable turn depends on a heavily back-loaded Q4 and on halting the steady deceleration in streaming.
Read our earnings preview for AMC Global Media Inc.: https://www.earningswhispers.com/article/AMCX/22606
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 3 hours | |
| 4 hours | |
| Nov-02 | |
| Oct-22 | |
| Sep-11 | |
| Aug-06 | |
| Jul-31 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-09 | |
| Jun-16 | |
| May-11 |
