PPHC Misses On EPS As Government Relations Drives Organic Reacceleration And Guidance Holds
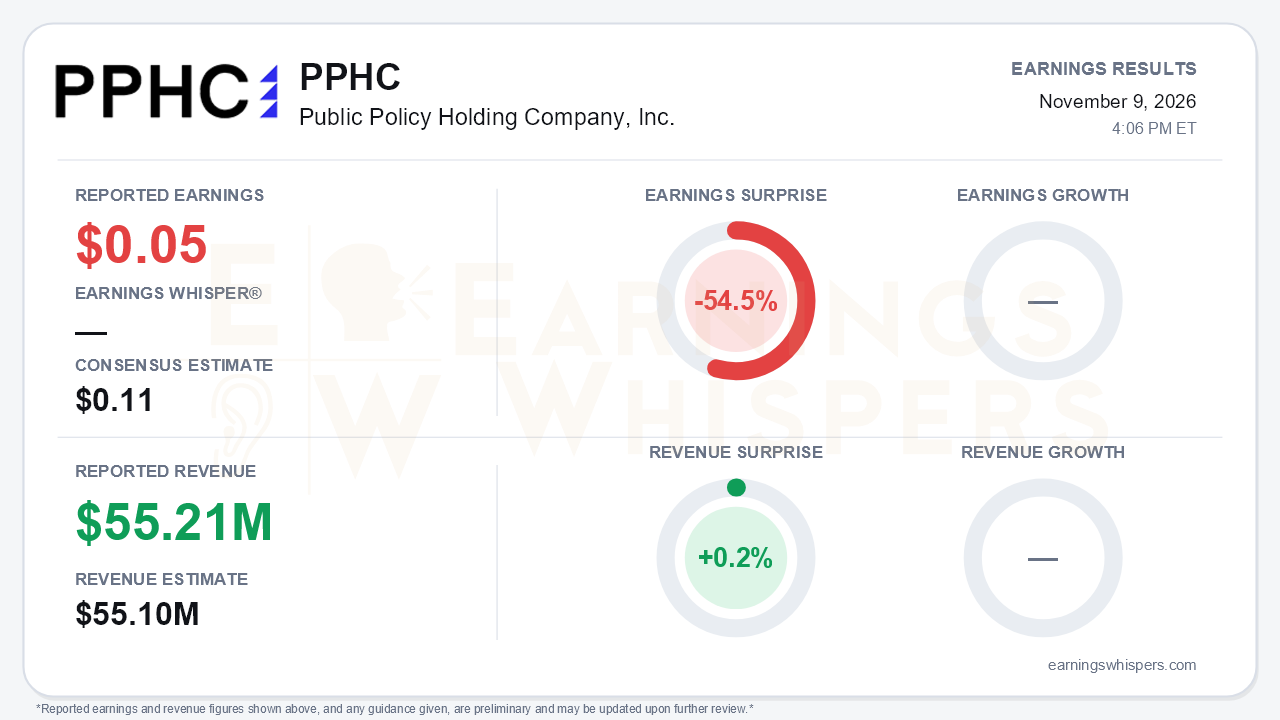
Public Policy Holding Company (NASDAQ: PPHC) delivered a quarter in which the top line and the bottom line pointed in different directions. Earnings Whispers recorded earnings of $0.05 per share against a $0.11 consensus, a 54.5% miss. Revenue of $55.21 million was essentially in line, beating the $55.1 million consensus by 0.2%.
The company's own per-share figures sit on different bases from the Earnings Whispers number:
- **GAAP:** a loss of $0.01 per share.
- **Adjusted, fully diluted:** $0.33, down from $0.36 a year ago.
None of these measures tells a story of per-share earnings growth. That is the central tension. The operating business is reaccelerating, but shareholders are not yet seeing it in earnings per share.
The quality of the quarter deserves scrutiny on both the GAAP and adjusted lines.
- **GAAP:** The swing from a $7.4 million net loss to $0.2 million of net income rests almost entirely on a $9.8 million non-cash bargain purchase gain. Management itself describes this gain as a product of tax-versus-book purchase-price accounting, not a genuine bargain. Without it, GAAP results would have remained firmly in the red.
- **Adjusted:** Adjusted EBITDA rose 11.1% to $12.8 million and adjusted net income rose 8.7% to $10.7 million. However, a roughly 20% increase in the fully diluted share count following the January U.S. IPO more than absorbed those gains.
- **Margins:** The adjusted EBITDA margin slipped to 23.2% from 23.6% a year earlier and 23.5% in Q2. Non-allocated corporate costs jumped to $4.8 million from $3.0 million, reaching 8.6% of revenue as public-company and platform costs piled up. Including M&A expense, adjusted EBITDA grew just 4.2%.
Beneath the headline, the operating trends improved in the core franchise.
- **Organic growth:** Organic revenue growth reaccelerated to 5.1% from 3.9% in Q2.
- **Government Relations:** The segment, now about 58% of revenue, grew 7.5% organically. That compares with 7.4% in Q2 and roughly 5% in Q1, with strength spanning federal, state and London work. Segment pre-bonus EBITDA margin expanded sharply to 48.3% from 42.0%, reflecting consistent retainer pricing.
- **Compliance and Insights:** The segment grew 16.3%.
- **Corporate Communications & Public Affairs:** This remains the soft spot. Organic revenue fell 0.8% in Q3, following a roughly 3% decline in Q2, and segment margin compressed to 25.5% from 30.4% on lower project volumes and lower-margin acquired revenue.
- **International:** Revenue more than doubled, up 106.6%, as acquisitions such as Tancredi pushed the non-U.S. mix to 9.2% of sales.
Full-year guidance was reaffirmed rather than raised:
- revenue of $213 million to $216 million;
- adjusted EBITDA of $48.5 million to $50.5 million, a 22.5% to 23.5% margin;
- organic growth of about 5%.
The release states that these unchanged ranges already include two months of the newly closed Reevemark acquisition. Put differently, the deal did not move the numbers, which the call analysis characterized as guidance not lifted for Reevemark. Management's tone on 2027 was notably more confident. It framed the midterm elections, with 21 new governors and more than 6,000 state legislative seats turning over, as a catalyst for a rebound in communications project work similar to 2025. That is an expectation, not a result, and fourth-quarter communications performance will test it.
The forward catalysts are tangible:
- **Acquired revenue:** Four 2026 acquisitions add roughly $33 million of annualized revenue.
- **Financing capacity:** A new five-year $105 million Bank of America facility is targeted to expand to $150 million.
- **GAAP profitability:** Management expects the roughly $30 million annual share-based charge tied to the 2021 London IPO to roll off after 2026, setting up a path to GAAP profitability.
Bears have legitimate ammunition as well:
- **Cash flow:** Nine-month adjusted free cash flow fell to $14.6 million from $21.1 million as receivables rose by $11.6 million, partly reflecting collection issues. The call did note that Q3 free cash flow of about $10 million showed improvement.
- **Net debt:** It climbed to $21.4 million from $5.2 million at the end of Q2 after cash-funded deals.
- **Earnouts:** Expected earnout obligations total $80.2 million through 2031, with $49.7 million concentrated in 2028.
- **Margin target:** The 25% adjusted EBITDA margin target remains out of reach while holding-company costs run at their current level.
Investor sentiment heading into the report remained negative but improved substantially, rising from -1.0 to about -0.49. Expectations were shifting from outright pessimism toward something more balanced, though not yet constructive. The stock's path reflects that ambivalence:
- Shares at $11.17 were up just 1.7% from the open after the August report.
- That modest net change masks a wide swing, from a $13.39 high on September 18 to a $9.51 low on October 27.
- The stock entered the report 17.5% off that low but still 16.6% below the high and about 1.3% under its 200-day moving average.
- Earnings Whispers trend readings were mixed, with momentum positive while AVWAP remained negative.
The bottom line is that PPHC's quarter strengthened the operating narrative while doing little for per-share earnings. Government Relations is accelerating with expanding margins, M&A capacity is growing, and the 2027 roll-off of IPO-related charges offers a credible path to cleaner GAAP results. Yet the EPS miss, dilution-driven declines in adjusted EPS, stubborn holding-company costs, negative communications organic growth, weaker cash conversion and rising net debt mean the reacceleration has not yet translated into shareholder-level earnings growth. Until communications stabilizes and margins move back toward target, the stock is likely to be judged on that execution gap rather than on the strength of its lobbying franchise alone.
Read our earnings preview for Public Policy Holding Company, Inc.: https://www.earningswhispers.com/article/PPHC/22662
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 3 hours | |
| Nov-02 | |
| Nov-02 | |
| Nov-02 | |
| Oct-28 | |
| Oct-14 | |
| Sep-25 | |
| Sep-11 | |
| Aug-11 | |
| Aug-10 | |
| Aug-03 | |
| Jul-27 | |
| Jul-14 | |
| Jul-01 |
