Myomo Beats And Nears EBITDA Breakeven, But A Thinning Pipeline Clouds 2027
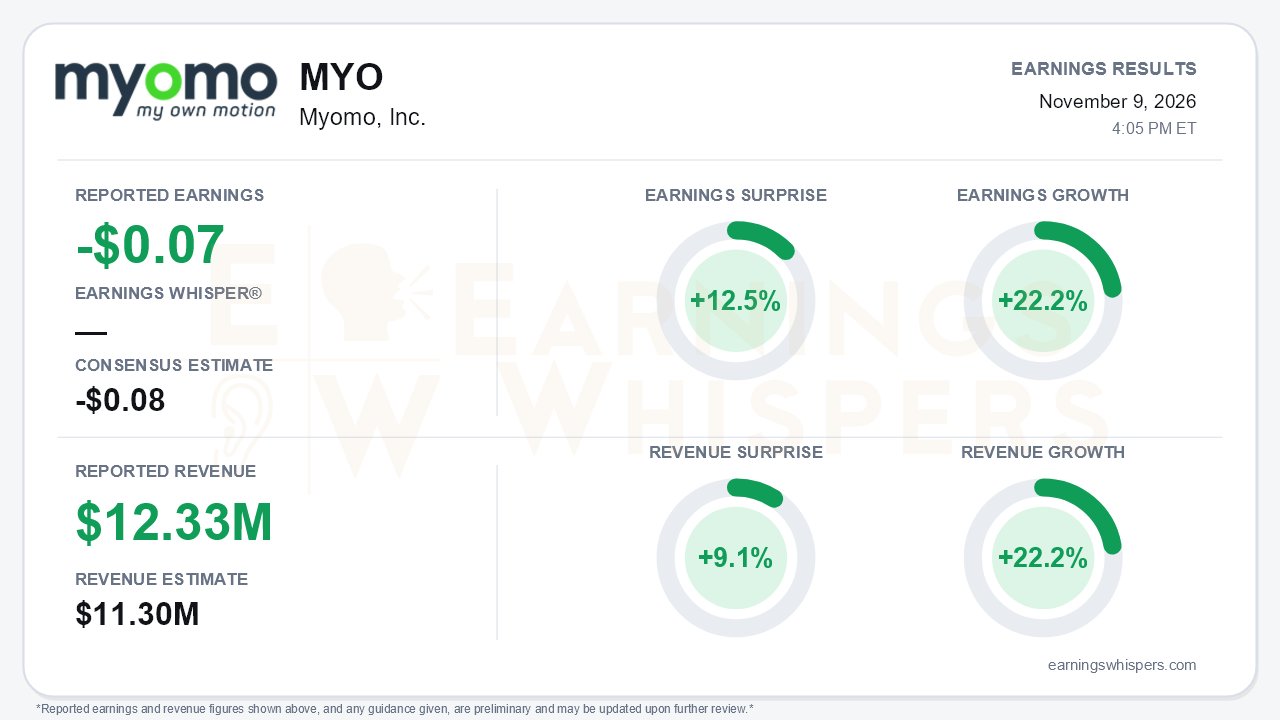
Myomo delivered the cleanest quarter of its recent turnaround. The question now is whether the front end of the business can keep pace with the back end. The company reported a loss of $0.07 per share on record revenue of $12.33 million. That beat the -$0.08 consensus by 12.5% and topped the $11.3 million revenue estimate by 9.1%. Earnings improved 22.2% year over year and revenue grew 22.2%. Revenue also cleared management's own $11.5-12.0 million guide. Growth held at the low-20% pace established in the second quarter (+21%), a sharp turn from just 3% in the first quarter. Management narrowed full-year guidance to $46-47 million, the upper half of a range that has now been lifted twice. The central tension is that conversion and margins are improving while pipeline adds, order growth and the reimbursement pipeline are softening.
The quality of the beat is mostly genuine at the operating level, but it deserves scrutiny below that line. Revenue units rose 19% and ASP rose 2% to about $55,500. Gross margin expanded 750 basis points to 71.3% on material cost reductions and better fixed-cost absorption. Operating expenses grew only 6%, and the operating loss was cut roughly in half to $1.7 million. Adjusted EBITDA was essentially breakeven, compared with a $2.7 million loss a year ago. That figure excludes stock-based compensation, however, which more than doubled to $1.3 million. Management acknowledged that stock-paid incentives aided the result and that compensation expense should normalize in the fourth quarter. GAAP tells a weaker story. Net loss widened to $4.2 million, or $0.10 per share, reflecting a $1.8 million non-cash derivative mark-to-market charge and $560,000 of net interest tied to the Avenue term loan. That compares with a $0.09 GAAP loss a year earlier.
The call showed a business shifting toward more durable demand sources. Recurring patient sources reached 54% of revenue, up from 42% in the fourth quarter of 2025. MyoConnect direct-billing referrals climbed to 27% of revenue from 20% in the first quarter, and referring sites expanded from roughly 150 to more than 500 this year. Orders hit a record 258. That progress coexists with a softer top of funnel:
- Pipeline adds fell to 600 from 739 in the second quarter and 723 in the first, which management attributed to summer seasonality, MyoConnect staffing gaps and inefficient direct-to-consumer lead generation.
- Order growth slowed to 13% from 23%.
- The total reimbursement pipeline shrank to about 1,400 from 1,491 and 1,680 in the prior two quarters.
- Backlog edged down to 217.
- Gross margin slipped sequentially from 72.1%.
Management said October adds ran about 30% above the third-quarter monthly average, but one month does not settle the trend.
The catalyst list addresses that funnel problem directly. Payer contracts covering roughly 35 million additional lives are signed or being finalized, including Medicare Advantage and commercial plans. Seven state Medicaid enrollments open secondary payment on Medicare Part B patients. New Chief Commercial Officer Katie McClure, formerly of Inspire Medical, is already adding field clinical staff. In-sourced 3D printing of custom shells, expected by year-end, should support further cost reductions, and management guided fourth-quarter gross margin modestly higher. Bears have legitimate ammunition on the balance sheet, though:
- Cash fell to $11.9 million.
- Debt totals about $13.4 million.
- Stockholders' equity has shrunk to $2.8 million from $11.4 million at year-end.
- Fourth-quarter opex will rise modestly.
- Management declined to commit to a 2027 operating-leverage target.
Investor sentiment moved the opposite direction from the fundamentals. It remained negative and deteriorated to -0.38 from -0.21 heading into the report. The stock's path explains some of that caution. Shares spiked to a 52-week high of $1.89 shortly after the August report, then surrendered most of the move. At $1.21 before this release, they sat 35.8% below that peak. They were still up 18.6% from the $1.02 post-report open, which was also the quarter's low, and 11.6% above the 200-day moving average. The trend readings are mixed, with momentum positive and AVWAP still negative.
The bottom line is that Myomo proved it can grow above 20% with real gross-margin and operating leverage, and guidance has now risen twice. The next leg depends on refilling a pipeline that contracted for two straight quarters. It also depends on the new commercial leadership and payer contracts translating into orders before a thin balance sheet forces the financing question back to the forefront.
Read our earnings preview for Myomo, Inc.: https://www.earningswhispers.com/article/MYO/22787
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-09 | |
| Nov-03 | |
| Nov-03 | |
| Nov-02 | |
| Oct-12 | |
| Sep-01 | |
| Aug-06 | |
| Jul-29 | |
| Jun-16 | |
| May-20 | |
| May-14 | |
| May-13 | |
| May-07 | |
| May-04 |
