Mesa Labs Posts Margin-Driven Gains And First-Ever Guidance, But The Outlook Implies A Softer Second Half
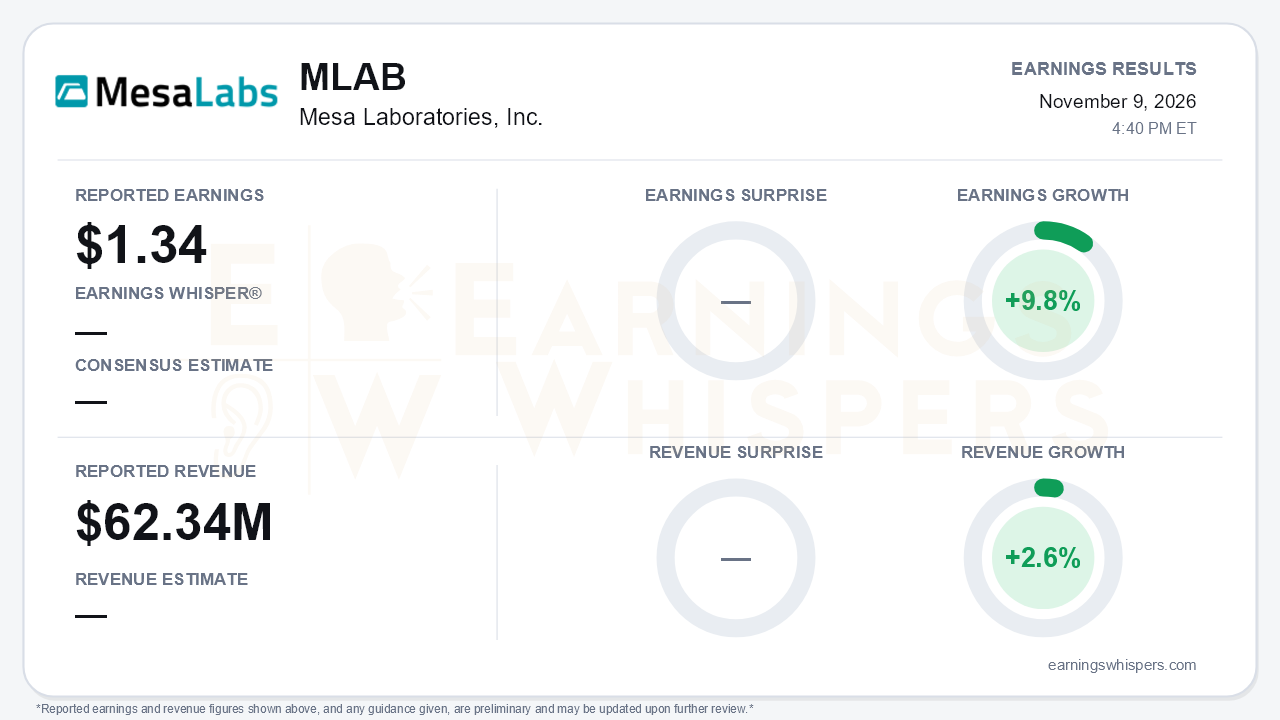
Mesa Laboratories (NASDAQ: MLAB) reported earnings of $1.34 per share on revenue of $62.34 million for its fiscal second quarter ended September 2026. Earnings grew 9.8% and revenue grew 2.6% year over year. There was no consensus estimate to measure against, so the quarter has to be judged on its trajectory. On that basis, profitability improved far faster than the top line. GAAP diluted EPS rose to $0.75 from $0.45. Adjusted EBITDA climbed 21.1% to $17.3 million, and margin widened to 27.8% from 23.5%. The more consequential news, though, was what management chose to issue alongside the results: first-ever full-year guidance, a cost-savings plan, and a new $40 million buyback. Together they amount to a statement that the execution problems of the past year are being contained. The central tension is that the guidance, by management's own description built conservatively, implies the second half will be slower than the first.
The quality of the quarter's growth deserves scrutiny. Sterilization and Disinfection Control, roughly 41% of revenue, drove most of the improvement. Organic sales rose 14.6%, but the company acknowledged that this largely reflects an easy comparison with a year-ago quarter hurt by production-related fulfillment delays. The division's gross margin rose 260 basis points as contract labor and consulting costs fell away. Trailing-twelve-month SDC revenue reached a record $103.9 million, and the FDA inspected the Bozeman biological indicator plant without issuing any Form 483 observations. Both are genuine positives for a franchise whose reliability had been in question.
The other three divisions were less encouraging:
- **Biopharmaceutical Development** swung from roughly 5% organic growth in the first quarter to an 8.2% decline. The cause was export-control processing delays on peptide hardware, with some shipments slipping past quarter-end by days.
- **Calibration Solutions** decelerated from 7.6% to 3.5% organic growth, and its gross margin fell 110 basis points.
- **Clinical Genomics** dropped 8.8%. Management is now deliberately shrinking it toward pharmacogenomics, oncology, and high-utilization accounts.
The overall picture still improved. Organic growth accelerated from 1.0% in the first quarter to 2.6%, and to 5.2% excluding Clinical Genomics.
The guidance is where the setup becomes more complicated than the margin story suggests. Fiscal 2027 targets are revenue of $250 million to $255 million and adjusted EBITDA of $66 million to $68 million. That equates to 5% to 8% EBITDA growth on 0% to 2% revenue growth. First-half adjusted EBITDA was already $32.8 million, however. The guidance therefore implies second-half EBITDA of roughly $33.2 million to $35.2 million, below the roughly $35.8 million generated in the prior-year second half. Trailing EBITDA of $68.6 million also sits at the top of the full-year range. Management attributed the moderation to a planned decline in Clinical Genomics, reinvestment of about $4.3 million of the $9.3 million in gross savings, and uneven quarterly timing. Third-quarter revenue is guided roughly flat. The call also flagged that the SDC product line carrying the largest share of past-due backlog is only partially fixed. Bears have legitimate ammunition here: the guide frames a business still in repair, not one already compounding.
The catalysts are real, though largely self-help:
- **Savings plan.** It targets a net $5 million annualized cost reduction, with $2.6 million to $3.4 million of pre-tax restructuring charges concentrated in the second half and excluded from adjusted EBITDA.
- **Balance sheet.** First-half debt repayment totaled $20.1 million, net leverage is down to 1.75x, and first-half operating cash flow rose by $8.7 million to $18.8 million.
- **Capital return.** The $40 million repurchase authorization is now possible because of that deleveraging.
- **Clinical Genomics.** The top three customers renewed for two to three and a half years, which lowers the risk of the restructuring.
- **Taxes.** Management raised the possibility of a partial U.S. valuation allowance release within 12 months.
EPS figures should be compared on a consistent basis. The adjusted $1.34 grew 9.8%, while GAAP EPS jumped about two-thirds. The GAAP comparison was helped by lower interest expense and a prior-year quarter burdened by severance, partly offset by a swing from a tax benefit to tax expense.
Investors came into the report skeptical. Earnings Whispers sentiment stood at a negative -0.28 after the August release, and no updated reading is yet available to show how that has shifted. Shares opened at $98.12 the morning after the prior report, below the 200-day moving average now near $105.03. That suggests the market has been treating Mesa as a show-me story. A conservative guide, a buyback, and visible deleveraging are the tools management chose to address that skepticism.
The bottom line is that Mesa's second quarter showed genuine margin repair and better execution in its most important franchise, and management backed it with credible capital-allocation moves. The forward picture is less robust. The SDC acceleration was comparison-aided, BPD and Calibration lost momentum, and the guidance implies flat third-quarter revenue and softer second-half EBITDA than a year ago. If management is right that the outlook is conservative, the bar has been set low enough to clear. Until the SDC backlog fix is complete and BPD shipments normalize, however, the turnaround remains a work in progress.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 2 hours | |
| 3 hours | |
| Oct-28 | |
| Oct-13 | |
| Oct-09 | |
| Aug-11 | |
| Aug-10 | |
| Aug-10 | |
| Aug-03 | |
| Jul-06 | |
| Jun-17 | |
| May-27 | |
| May-27 | |
| May-05 |
