Kaltura's Bookings Surge And Third Guidance Raise Run Into A Soft Fourth-Quarter Outlook
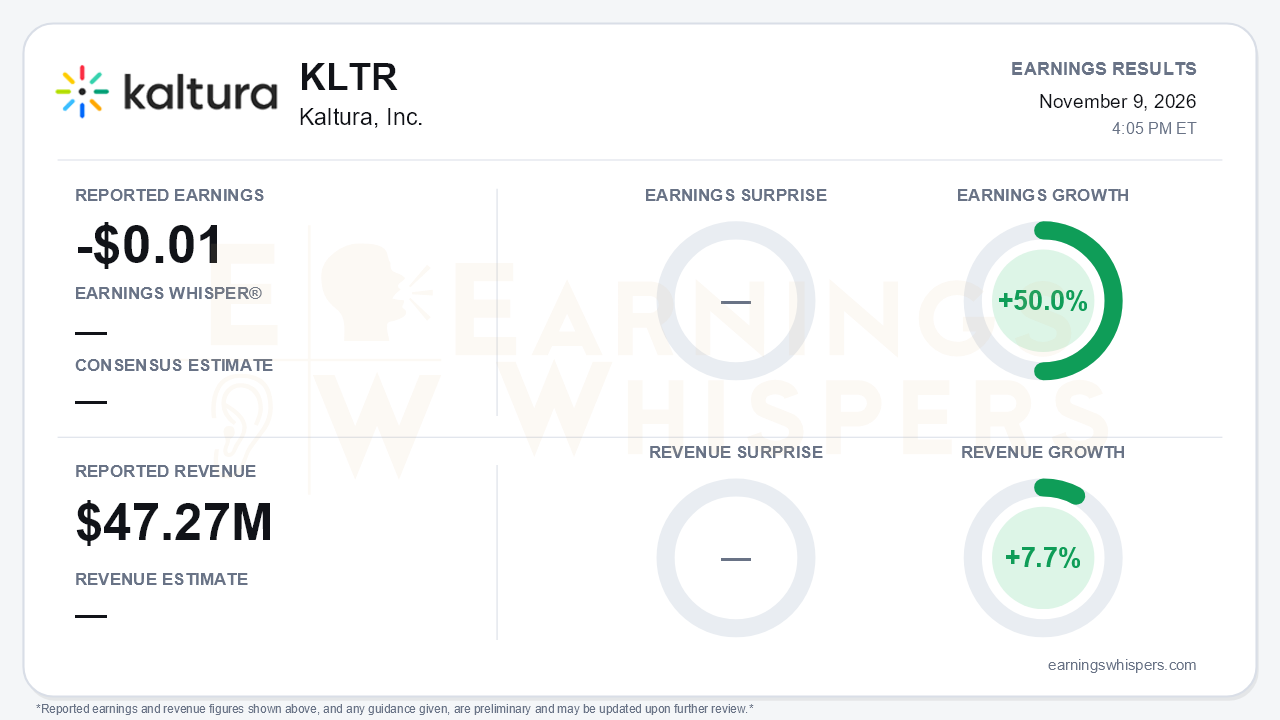
Kaltura narrowed its GAAP loss to $0.01 per share from $0.02 a year ago, which works out to 50.0% earnings growth. Revenue rose 7.7% to $47.27 million, a clear acceleration from 5% growth in the second quarter and a 5% decline in the first. Management called it the company's fastest growth since early 2022. No consensus figures were available, so the relevant yardstick is Kaltura's own guidance. The company beat the high end of its ranges for total revenue, subscription revenue and adjusted EBITDA, then raised full-year guidance for the third straight quarter. That is the headline. The central tension is that the fourth-quarter outlook points to a sharp slowdown, even as the leading indicators of future demand improved most clearly in roughly two years.
The quality of the quarter holds up reasonably well, with some caveats. Adjusted EBITDA climbed 45% to $6.0 million, a record for a third quarter. Non-GAAP operating profit rose to $4.9 million from $3.1 million, and non-GAAP EPS improved to $0.02 from $0.01. On a GAAP basis, the business was essentially breakeven before taxes. A $1.6 million tax provision, along with a currency gain in financial income, shaped the bottom line, so the GAAP loss says little about operating direction either way.
The segment mix tells the real story. Enterprise, Education and Technology revenue grew 14%, accelerating from 11% in the second quarter and a 1% decline in the first. Media & Telecom fell 10% as elevated churn from 2025 continued to work through results. Subscription gross margin held at 77%. GAAP gross margin of 72% improved from a year ago but slipped from 74% in the second quarter.
The call supplied the most encouraging evidence. New subscription bookings more than doubled sequentially, making this the best bookings quarter since 2024. Kaltura signed three seven-figure deals, compared with one in the first quarter and none in the second. AI-related deals rose to about $3.8 million in total contract value across 15 transactions, up from about $1.0 million last quarter. The AI pipeline expanded to roughly $24 million in potential annual contract value from about $17 million, and new logos now make up nearly half of it. Proofs of concept increased to more than 80 from more than 60. Net dollar retention improved for a second straight quarter, reaching 97% from 96% in the second quarter and 95% in the first. Management's tone has moved from calling 2026 a transition year to describing commercial momentum, with explicit confidence in a more meaningful contribution from new offerings in 2027. Full-year adjusted EBITDA guidance of $19.5 million to $20.5 million now exceeds the 2025 level of $18.6 million, which management originally hoped only to approach.
Bears have legitimate ammunition, however. The outlook implies fourth-quarter revenue of $46.2 million to $46.9 million, below the third quarter's $47.3 million and only about 1% higher than a year ago. Subscription growth is expected to slow to 4% to 5%. Adjusted EBITDA guidance of $2.0 million to $3.0 million is less than half the third-quarter figure. Several other metrics stalled:
- Gross churn rose on legacy Kaltura and PathFactory contracts, and management expects that pressure to persist into the fourth quarter. This reverses the second quarter's strong retention.
- ARR was essentially flat sequentially at $184.7 million.
- Remaining performance obligations slipped 2% sequentially to $161.6 million.
- Professional services revenue fell 29%.
- Management warned that AI inference costs could trim gross margin by 1 to 2 points in the near term.
The pattern suggests the bookings surge has not yet reached the recurring base. Meanwhile, churn is eating into what has already been sold.
The balance sheet adds another layer. Cash and marketable securities totaled $41.0 million, down from about $63 million at year-end after the $22.5 million PathFactory acquisition. The current portion of long-term loans stands at $25.3 million. That makes the credit facility refinancing management expects to close in the fourth quarter, with a new three-year term, a meaningful item to watch. Third-quarter operating cash flow of $7.6 million was healthy but below the $9.3 million of a year earlier. Year-to-date operating cash flow is $6.3 million, compared with $10.9 million last year.
Market context is thin. The shares opened at $1.45 after the August report, just above a 200-day moving average now at $1.40. No current price or sentiment reading was available, so it is not possible to say how investors have been positioned into this report.
The bottom line is that Kaltura delivered its most convincing evidence yet that the agentic AI pivot is producing commercial traction. The evidence includes doubled bookings, a jump in seven-figure deals, a growing AI pipeline and improving retention, all alongside a third beat-and-raise. Yet the quarter also exposed a gap between pipeline enthusiasm and recurring revenue. Flat ARR, falling RPO, rising churn and a near-flat fourth-quarter guide mean the growth story still depends on converting proofs of concept into production revenue in 2027. Until ARR resumes climbing, the acceleration remains a promise rather than a trend.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-09 | |
| Nov-05 | |
| Nov-03 | |
| Oct-26 | |
| Oct-21 | |
| Sep-28 | |
| Sep-15 | |
| Sep-08 | |
| Sep-07 | |
| Sep-03 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 |
