Better Home & Finance Misses Badly As Founder's Return Swaps Growth Targets For A Cost-Cutting Reset
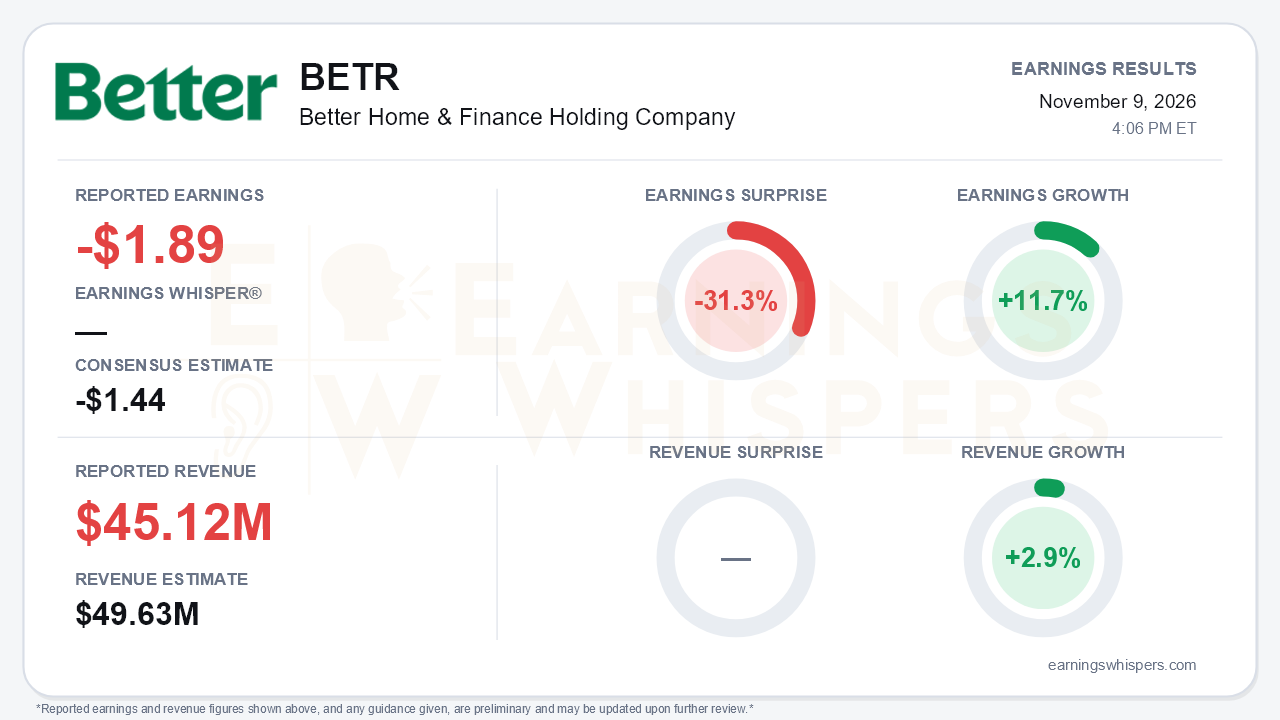
Better Home & Finance Holding Company (NASDAQ: BETR) delivered a clear miss in a quarter that management is treating as a reset. The company lost $1.89 per share from continuing operations, well short of the $1.44 consensus loss, a 31.3% negative surprise. Revenue of $45.12 million trailed the $49.63 million consensus by 9.1% and also fell short of the company's own $49-52 million guidance from the second-quarter call. The loss did narrow from a year ago, with Earnings Whispers calculating 11.7% year-over-year earnings growth, and revenue grew 2.9%. The central tension is that founder Vishal Garg's return through a proxy fight has produced an aggressive cost and channel overhaul, but it arrived alongside deteriorating volume, rising cash burn, and the loss of any dated path to profitability.
The quality of the quarter is weaker than the year-over-year comparisons suggest. The press release cites 9% revenue growth against a reclassified $41.5 million prior-year figure, which excludes Birmingham Bank as a discontinued operation. The Earnings Whispers normalized growth rate is a lower 2.9%, so investors should note the two bases differ. The sequential picture is clearer. Revenue fell from $54.7 million in Q2, and loan volume slid to $1.40 billion from $1.67 billion. The adjusted EBITDA loss widened to $29.7 million, compared with $14 million in Q2 and $19 million in Q1. Management excludes about $12.8 million of proxy-related and other one-time legal costs, which brings the loss to roughly $16.8 million, inside the $15-18 million guide. Even on that friendlier basis, the business is losing more than it did last quarter. General and administrative expense more than doubled year over year to $21.0 million.
The call made the operating damage explicit. Garg blamed the interim leadership for a 29% drop in loan officer talk time, a 25% decline in production hours, and stalled partner launches. Monthly volume fell from $496 million in July to $345 million in October. Management called October and November the bottom of a "U," with seasonal weakness extending into January. Rising rates and macro uncertainty pushed the refinance mix down to 25.5% from 33% in Q2. The company provided no Q4 revenue or volume guidance. The breakeven target has drifted from "end of Q3 2026" to "as soon as possible." The $1 billion monthly volume goal for May 2026 is effectively dead.
The constructive case rests on cost and channel mix:
- **Cost savings:** The annualized savings target rose again, from $25 million to more than $45 million and now about $64.2 million, with $30.4 million already executed.
- **Opex guidance:** Q4 adjusted operating expenses are guided to $45-47 million, versus roughly $75 million in Q3, the most consequential forward number in the report.
- **Platform growth:** Platform volume grew 64% year over year to $792 million, a record 57% of the total.
- **HELOC momentum:** HELOCs rose to 19% of volume.
- **New channels:** An AI-powered HELOC launched with a large existing partner, and the wholesale channel signed 39 brokerages representing about $400 million in annual addressable volume.
- **Partner pipeline:** Four previously stalled partner opportunities were re-engaged.
- **Capital actions:** The Birmingham Bank sale is expected to bring in about $65 million in Q1 2027, and the company has repurchased 6.9% of Class A shares.
Bears have legitimate ammunition. Cash fell to $77.5 million from about $102 million in Q2, and stockholders' equity is just $24.3 million. The weighted share count rose about 24% year over year, so the per-share loss improvement partly reflects dilution. Cutting management layers and marketing spend while volume is falling creates real execution risk. A smaller cost base does not by itself produce more funded loans.
Investor sentiment shifted meaningfully, moving from slightly negative (-0.09) to modestly positive (+0.22) ahead of the report. This likely reflects enthusiasm around the leadership change. The stock's path was volatile:
- It hit a 52-week low of $7.51 on October 14.
- It surged to $23.63 by October 29 as the proxy outcome took shape.
- It stood at $19.24 just before earnings, up 21% from the open after the August report.
- That price was still 18.6% below the October high and 22.6% below the $24.85 200-day moving average.
The AVWAP trend reading is positive while the price trend is neutral. This fits a stock that has rebounded sharply but has not reclaimed its longer-term trend.
The bottom line is that Better's third quarter was a fundamental miss wrapped in a governance-driven narrative change. The market has already partly priced in the founder's return, but the numbers have not yet caught up. Volume is still falling, revenue missed guidance, and cash is thinning. Whether the stock's rebound holds now depends on the company landing Q4 opex near $45-47 million and showing that the new HELOC, wholesale, and partner channels can lift funded volume out of the seasonal trough.
Read our earnings preview for Better Home & Finance Holding Company: https://www.earningswhispers.com/article/BETR/22784
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Oct-29 | |
| Oct-28 | |
| Oct-27 | |
| Oct-26 | |
| Oct-20 | |
| Oct-20 |
