APEI Clears A Low Bar And Raises Again, But Margin Compression And A Cooling Health+ Engine Explain The Market's Skepticism
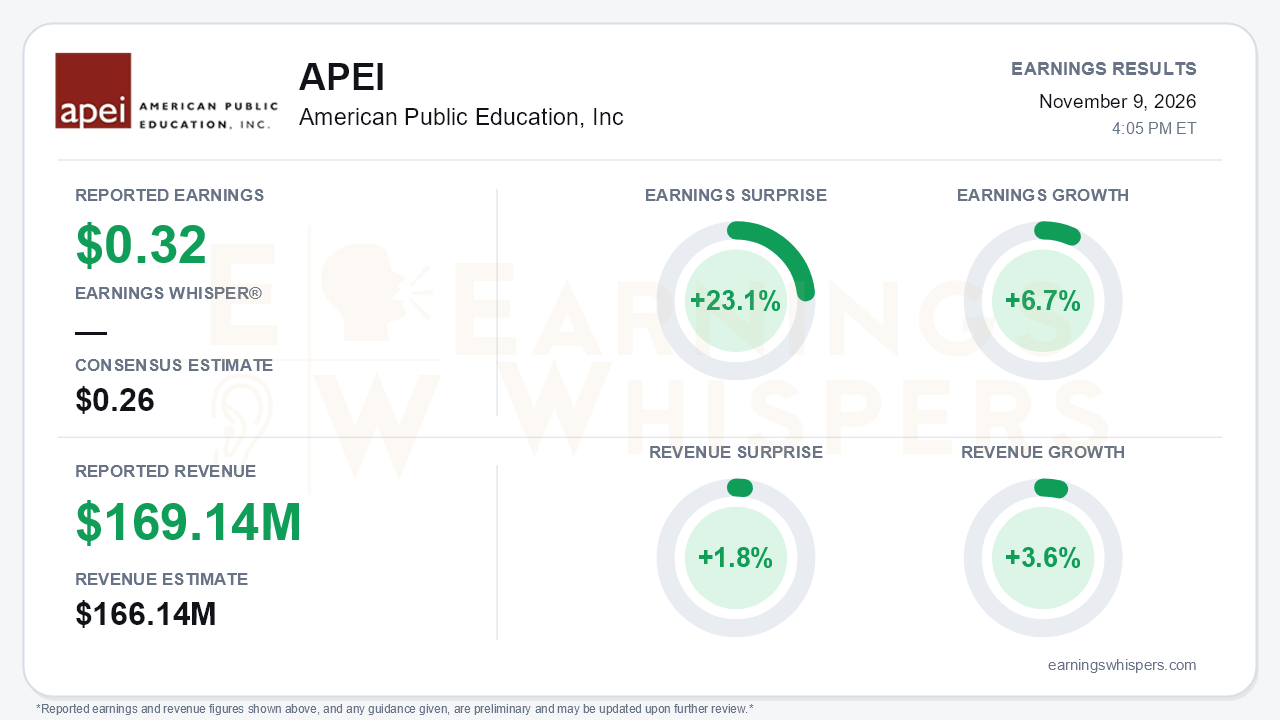
American Public Education delivered another beat-and-raise quarter. Third-quarter EPS of $0.32 topped the $0.26 consensus by 23.1% and grew 6.7% year over year. Revenue of $169.14 million beat the $166.14 million consensus by 1.8% and rose 3.6%. Revenue, net income, EPS and adjusted EBITDA all exceeded the company's own guidance, and full-year targets moved higher for the third consecutive call. Yet Earnings Whispers characterizes the outlook as in-line, and that is the central tension. The raises are getting smaller, operating margins are compressing, and the Health+ growth engine is visibly decelerating. A clean headline sits on top of a more complicated quarter.
The quality of the beat deserves scrutiny. GAAP operating income fell to $7.9 million from $9.7 million, and adjusted EBITDA dropped to $17.5 million from $20.7 million, taking the margin to 10.4% from 12.7%. EPS grew only because of items below the operating line. Net interest swung to $0.5 million of income from $1.1 million of expense, and tax expense fell. The year-ago quarter also carried a $3.9 million loss on the GSUSA sale. Selling and promotional spending rose $5.7 million to 24.7% of revenue from 22.1%. Military+ segment EBITDA margin slid to 27% from 32%, and from 29.4% in Q2. Management attributes part of the pressure to roughly $6.0 million of Military+ revenue that shifted into the fourth quarter on registration timing. That is a legitimate timing argument, but it does not explain the full margin step-down. Cash generation also weakened: operating cash flow fell to $11.8 million from $21.7 million because of Title IV disbursement delays tied to the institutional combination.
The operating story splits by segment. Military+ is improving. Registrations rose 3.8% to 103,800, above the 101,000-103,000 guide and faster than the 2% growth in Q2. Active-duty registrations returned to growth, led by the Army, after earlier calls cited deployments as a drag. Q4 registrations are guided up 21.7% to 27.7% against a shutdown-depressed comparison. Health+ is cooling:
- Segment revenue growth slowed to 9% from 11% in the first half, even with campus nursing up low teens and online health up mid-teens.
- Total enrollment grew just 2.5%.
- Q4 enrollment is guided to roughly 1%, versus about 3% in the prior guide and 7% actual growth in Q2.
- The culprit is Online Plus, the non-healthcare online business. In Q2 management framed it as a cost-per-lead problem expected to improve; it is now declining.
- Health+ swung to a $1.9 million operating loss from $0.3 million of income in Q2, hit by disbursement delays and bad debt.
The forward story still has credible support. Management quantified recurring cost synergies of $5 million from 2027 (Rasmussen/Hondros) and $9 million from 2028 (Health+/Military+), both already embedded in its long-range plan. It also kept the 2029 framework of $890 million to $1 billion in revenue at a 20-21% margin. Full-year guidance now calls for:
- Revenue of $695-701 million, up from $690-698 million.
- Adjusted EBITDA of $98-105 million.
- EPS of $2.59-2.84, up from $2.48-2.79.
That implies a heavy fourth quarter, with EPS of $0.81-1.07 versus $0.67 a year ago. Buybacks more than doubled to about $9 million, with roughly $36 million authorized remaining, and cash and investments stand at $216.4 million. The risk list grew too. The Detroit 2 campus slipped to Q2 2027 because the accreditor requires separate approval. NDAA reconsideration clouds a potential tuition assistance rate increase. Management also flagged healthcare-benefit inflation heading into 2027 and set an unusually wide Q4 registration range.
The market had already turned skeptical before the report. Shares closed at $37.28 on November 6, down 26.0% from the $50.35 open after the August report. They sat 25% below the 200-day moving average of $49.68 and just 3.1% above the inter-earnings low of $36.15 set that same day. The stock has round-tripped from its quarterly high on the first post-report session to the bottom of its range. Investor sentiment swung meaningfully, falling from a positive 0.31 to a slightly negative -0.09. Earnings Whispers price and AVWAP trend readings are negative, while momentum remains positive. Bears have legitimate ammunition in the margin and Health+ data. Still, a guidance raise and accelerating Military+ registrations are not what a stock trading at its lows typically prices in.
The bottom line is that APEI beat a low bar and raised again, but the quarter's earnings growth came from below the operating line while margins, cash flow and Health+ enrollment momentum all weakened. Military+ recovery, quantified synergies and a deeply discounted share price give the story a credible floor. Investors will need evidence that the Q4 revenue catch-up, bad-debt normalization and an Online Plus fix materialize before the decelerating Health+ narrative loses its grip.
Read our earnings preview for American Public Education, Inc: https://www.earningswhispers.com/article/APEI/22608
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-02 | |
| Oct-29 | |
| Oct-28 | |
| Oct-27 | |
| Oct-14 | |
| Oct-12 | |
| Oct-02 | |
| Oct-01 | |
| Sep-22 | |
| Sep-17 | |
| Sep-09 | |
| Sep-02 |
