AlTi Global Misses Badly As Cost Cuts Lift Margins While Flows Turn Negative And Revenue Growth Stalls
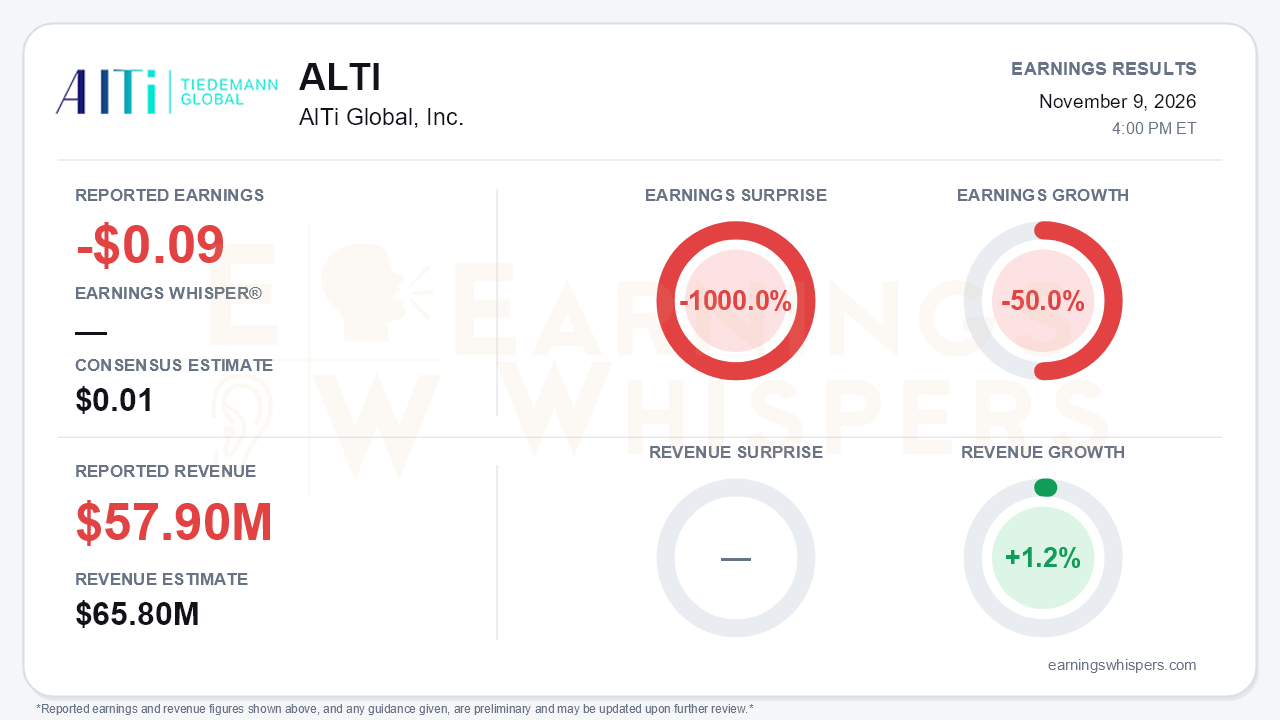
AlTi Global's third quarter set aggressive cost cutting against a franchise that stopped growing. The wealth manager reported a loss of $0.09 per share against a consensus estimate for a $0.01 profit, a 1000.0% miss. Revenue of $57.9 million came in 12.0% below the $65.8 million consensus. Earnings fell 50.0% year over year, and revenue grew just 1.2%. Margins are improving, but the top line, net flows and the value of external manager stakes all moved the wrong way. That is the central tension: AlTi is getting leaner faster than it is getting healthier.
The quality of the quarter needs careful reading, partly because the press release disclosed no financial figures and pointed investors to a separate presentation. The call filled in the detail.
- Operating expenses fell 25% year over year to $64 million, compared with a 12% decline in the second quarter.
- Non-compensation expenses fell 44%, and professional fees fell 37%.
- Headcount is down about 8% over twelve months and about 3% since June.
- Adjusted EBITDA topped $6 million, up 15% sequentially, and adjusted EBITDA margin rose to 11% from 9.3%.
- The GAAP net loss from continuing operations narrowed to $11 million from $31 million in the second quarter and $87 million a year earlier.
That sharp narrowing in continuing-operations losses sits awkwardly beside the normalized per-share figure, which shows earnings down 50.0% year over year. The supplied materials do not reconcile the two measures. Investors should not assume the GAAP improvement translated into better per-share results.
The operating trends beneath the cost story are deteriorating.
- **Revenue growth:** Growth slowed to roughly 1% from 11% in the second quarter and 28% in the first. The first quarter's $73 million had been inflated by incentive income.
- **Net flows:** Wealth management net flows swung to about -$250 million from roughly +$700 million of inflows in the second quarter. Management attributed the outflows to lower-fee legacy accounts leaving.
- **Distributions:** Distributions from investments fell 17% year over year after rising 28% in the second quarter.
There are bright spots. Recurring management and advisory fees rose 7% year over year to $55 million, up from $54 million. AUM edged up to $51.6 billion from $51 billion, which is distinct from the roughly $95 billion of combined managed and advised assets cited in the release. Still, recurring-fee growth this modest cannot offset lost incentive income and investment distributions.
The forward risks are concrete.
- **Zebedee write-downs:** Zebedee, the European equities manager that generated about $18 million of first-quarter incentive income, is shifting to a co-CIO structure and triggering redemptions. After a $7 million write-down in the third quarter, management expects a further $20-23 million non-cash unrealized loss in the fourth quarter.
- **Repeat pattern:** The Zebedee loss follows a roughly $19 million hit on an Asian credit manager in the second quarter. That manager's continued wind-down is still eroding fee contributions.
- **Leverage:** The new $85 million credit agreement with Diameter Finance adds flexibility, with a $28 million term loan drawn, an undrawn revolver, and a delayed-draw tranche earmarked for advisor and team lift-outs such as Miami. However, part of the facility is funding earnouts and UK real estate administration obligations, which adds leverage for non-growth purposes.
- **Open questions:** The strategic review remains unresolved with no update, and management again offered no formal guidance.
On the positive side, zero-based budgeting will be repeated for fiscal 2027, with further reductions slated for the fourth quarter and benefits expected through 2027-2028. The margin trajectory therefore has a credible runway even if revenue stays flat.
The market had already turned sharply against the stock before the report. Shares closed at $2.34 on November 6, down 39.8% from the $3.89 opening after the August report. They are 34.6% below the 200-day moving average of $3.58 and 45.6% below the inter-earnings high of $4.30 set August 14. The stock sits only 3.5% above the 52-week low of $2.26 reached October 15. Investor sentiment slid from mildly positive (0.0923) to mildly negative (-0.1195) over the quarter. That is a meaningful shift in tone but not capitulation. Price and AVWAP trends remain negative, while sequential growth and momentum readings are neutral. This fits a stock where cost progress is visible but has not changed how the market views the business.
The bottom line is that AlTi delivered real expense discipline and a cleaner margin profile, but missed badly on both earnings and revenue. Organic flows reversed, and a second straight external-manager write-down is coming. Bears have legitimate ammunition in stalled revenue, new leverage partly used for legacy obligations, and an open-ended strategic review. Until flows and revenue growth recover, the cost story alone is unlikely to change the setup for a stock trading near its lows.
Read our earnings preview for AlTi Global, Inc.: https://www.earningswhispers.com/article/ALTI/22782
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-09 | |
| Nov-03 | |
| Nov-02 | |
| Aug-11 | |
| Aug-11 | |
| Aug-10 | |
| Aug-03 | |
| Jul-20 | |
| Jun-29 | |
| Jun-25 | |
| Jun-25 | |
| Jun-09 | |
| May-15 |
AlTi Global to deploy Nevis AI platform across global adviser base
ALTI
Private Banker International
|
| May-14 |
