Zeta Global's Organic Growth Re-Accelerates To 30% And Guidance Rises Across The Board, But The Outlook Points To Slower Growth Ahead
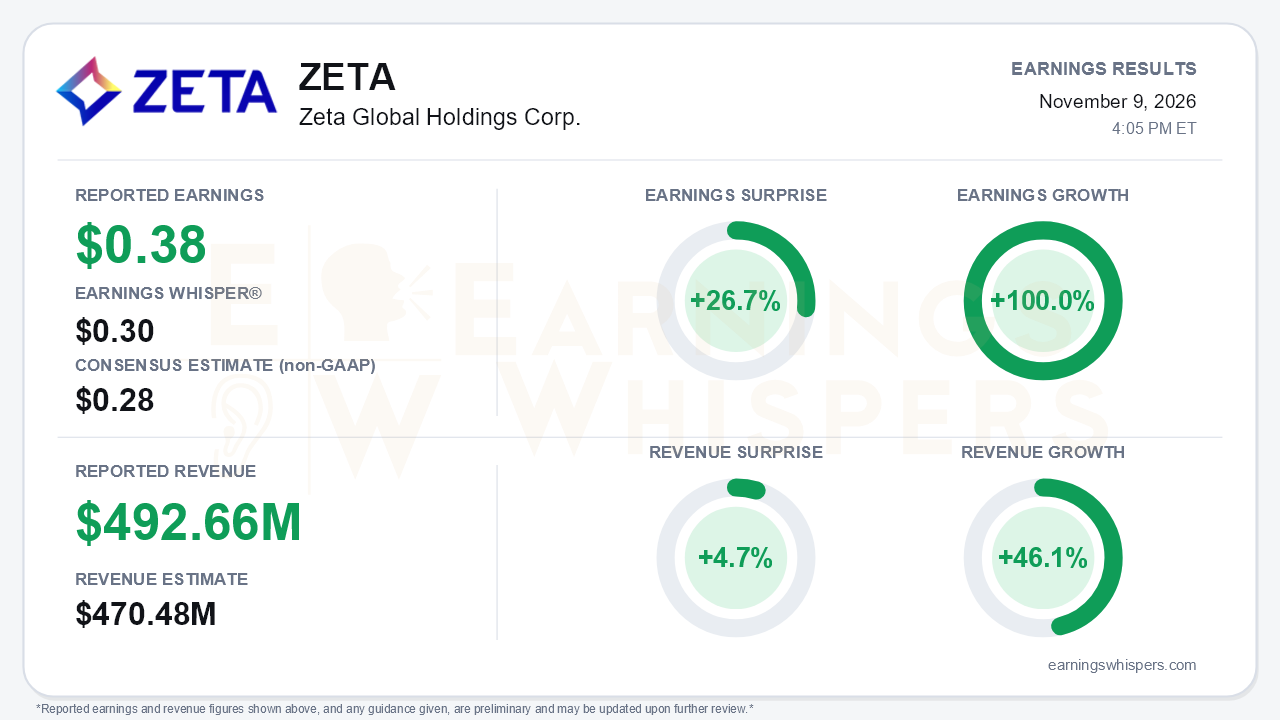
Zeta Global delivered a clean beat-and-raise. Non-GAAP earnings were $0.38 per share, ahead of the $0.28 consensus and the $0.30 Earnings Whisper number, a 26.7% surprise. That doubled the year-ago result, a 100.0% increase. Revenue of $492.66 million beat consensus by 4.7% and grew 46.1% year over year. The more important number is organic growth. Excluding the Marigold enterprise business and political candidate revenue, sales grew 30%, up from 28% in the second quarter and 29% in the first. That marks Zeta's 21st consecutive beat-and-raise, according to the call. The central tension is that management is guiding growth back toward the low 20s just as the business is re-accelerating.
The quality of the quarter holds up well beyond the headline. Adjusted EBITDA rose to $121 million, and margin reached a record 24.6%. That is up from 20.7% in Q2 and 16.7% in Q1. Free cash flow of $82 million rose 73% at a 16.5% margin. The GAAP result is the real inflection. Net income was $38.3 million, or $0.14 per share, versus a $3.6 million loss a year ago and $0.03 in Q2. The gap between $0.14 GAAP and $0.38 non-GAAP still deserves scrutiny. Stock-based compensation of nearly $50 million remains the largest reconciling item. The basic share count rose to 264.6 million from 222.4 million a year ago. Cost of revenues rose about 20 basis points as a share of sales, which management attributed to agency-driven social channel mix.
The operating metrics point to deepening customer engagement:
- Super-scaled customers reached 212, up 18%.
- ARPU for those customers grew 22%, up from 17% in Q2. Management says both metrics are running ahead of its 2028 model.
- Monthly active use of the Athena platform among super-scaled customers topped 50%, up from more than 40% last quarter.
- Net revenue retention for Athena adopters is now 500 basis points above the company average, up from 400 basis points.
- RFPs more than doubled year over year, and pipeline per seller rose 32%.
This is the clearest evidence that the AI product layer is driving monetization rather than just generating marketing language.
Guidance rose on every major line:
- Full-year revenue: up $37 million to a $1.855 billion midpoint, 42% reported growth and 27% organic.
- Adjusted EBITDA: up to $414.6 million.
- Free cash flow: up to about $271 million.
- GAAP EPS: raised to $0.23 from $0.10, against an initial $0.03. This figure excludes a possible one-time tax benefit from releasing part of the valuation allowance.
Bears still have legitimate ammunition. The fourth-quarter outlook implies roughly 23% organic growth, down sharply from Q3's 30%, even with the cushion management typically builds in. Management also previewed starting the 2027 organic guide near its historical 20–21%. That would be a meaningful step down from 2026's roughly 27% pace. Political revenue, raised to $13 million for Q4, also flatters near-term comparisons.
The catalyst list is long but uneven in maturity.
- **Palantir:** the partnership has eight customer wins, with the first joint customer converting to super-scaled status this month. Management reiterated more than $100 million of incremental annual revenue potential.
- **Zeta Live:** generated more than $100 million of new pipeline within weeks and 23 signed deals.
- **Salesforce–Braze:** management views Salesforce's pending acquisition of Braze as accelerating the marketing-cloud replacement cycle.
- **OpenAI ads:** Zeta is serving ads into OpenAI's ad business, with some budget shifting away from Google search.
- **Athena Inference Model:** built with Fireworks and NVIDIA, it is claimed to deliver 95% accuracy at 40% lower cost per request than frontier models.
- **AthenaOS and acquisitions:** AthenaOS extends the pitch into broader enterprise intelligence, and the Senso and Digital Audience deals add capabilities.
AthenaOS is still in alpha, with general availability targeted for Q1 2027, so the expansion beyond marketing is a promise, not a result. Balance-sheet moves add some complexity. Long-term borrowings rose to $244 million, and year-to-date investing included $51 million of acquisitions and $70 million of loan advances. Share repurchases were $85.5 million. Record investment spending could also cap margin upside.
The market had been leaning into this story before the print. Investor sentiment rose from essentially neutral (0.008) to a moderately positive 0.20, a meaningful improvement. Shares entered the report at $31.03, up 25.9% from the open after the August report and 36.4% above the 200-day moving average. However, the stock sat 13.2% below its 52-week high of $35.75, set on October 16, so it had already given back part of its autumn run. Most of the Earnings Whispers trend readings are positive, consistent with that improving price action. Expectations are therefore higher than they were three months ago. That raises the bar for how investors interpret the deceleration embedded in the guidance.
The bottom line is that Zeta produced one of its strongest quarters on record. Organic growth re-accelerated, margins expanded, GAAP profitability arrived, and guidance rose on every major line. The open question is durability rather than performance. Management's own framing points to growth settling back toward 20–21% next year. Holding the stock's premium now depends on Athena adoption, the Palantir channel, and AthenaOS proving they can keep growth above that conservative baseline.
Read our earnings preview for Zeta Global Holdings Corp.: https://www.earningswhispers.com/article/ZETA/22679
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-03 | |
| Nov-02 | |
| Oct-26 | |
| Oct-16 | |
| Oct-13 | |
| Oct-09 | |
| Oct-08 | |
| Oct-08 | |
| Oct-07 | |
| Oct-06 |
