GeneDx Crushes EPS Consensus On Margin Gains, But Lower Volume Guidance Exposes A Business Trading Growth For Profitability
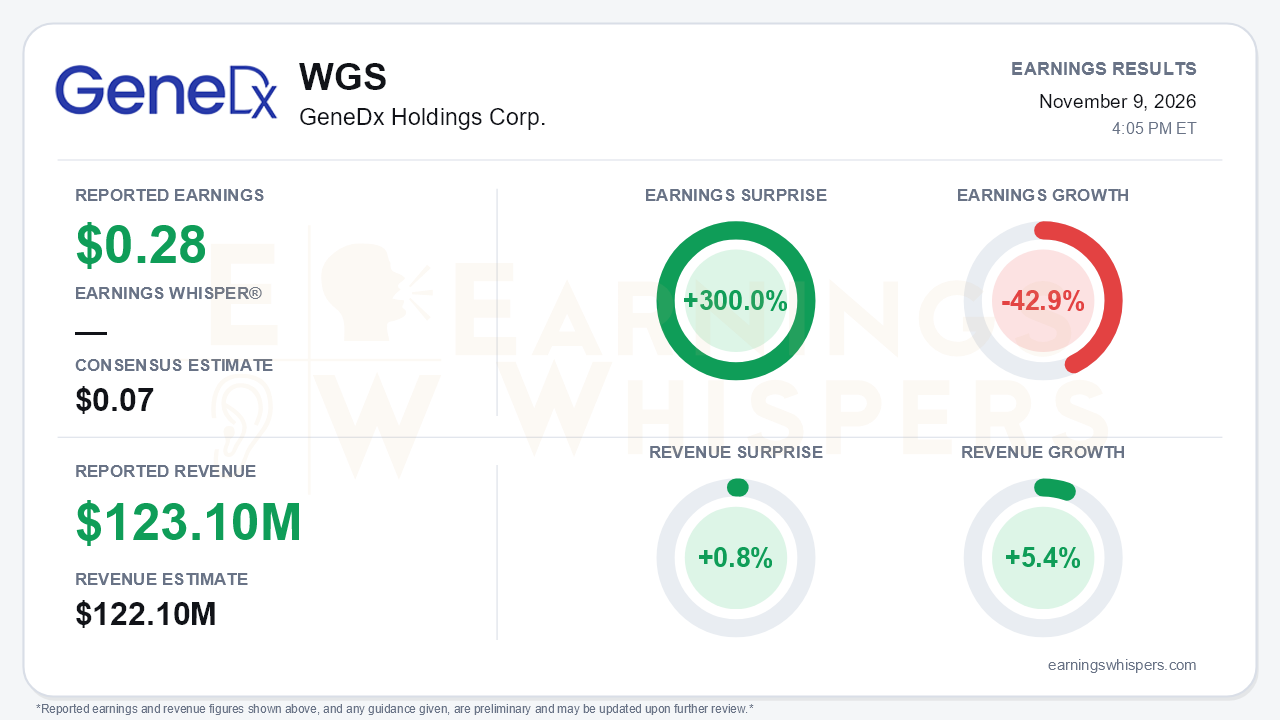
GeneDx Holdings (NASDAQ: WGS) reported adjusted earnings of $0.28 per share for the third quarter, far above the $0.07 consensus, a 300.0% surprise. Revenue of $123.1 million edged past the $122.1 million estimate by 0.8% and grew 5.4% year over year. The headline beat is real, but it is not the whole story. Earnings still fell 42.9% from a year ago. Management also cut its full-year volume and exome/genome revenue growth targets while raising its margin and profit outlook. That is the central tension. GeneDx is making each test more profitable while performing fewer of them than it planned, and the revenue line is settling at the bottom of a range that was already cut once this year.
The quality of the beat deserves scrutiny. Adjusted net income of $8.6 million came well above the roughly $2 million management had guided and marks a clean progression: a loss of about $8.2 million in Q1, break-even in Q2, and a profit in Q3. Adjusted gross margin rose to 72% from 70% in Q2, though it remains below the 74% posted a year ago. On a GAAP basis, however, GeneDx lost $12.3 million, or $0.41 per share, wider than the $7.6 million loss in the prior-year quarter as SG&A climbed to $79.1 million from $67.9 million. Mix is also shrinking the base. Exome and genome revenue grew 12% to $110.4 million, but other panel revenue fell to $9.7 million from $14.6 million, holding total growth to the mid-single digits. The balance sheet tells a similar story. Operating cash flow was a $72 million outflow over nine months versus a $36 million inflow a year earlier, and long-term debt has risen to $146 million.
The call explained where the volume went. Exome and genome tests rose 25% to 32,134, short of the roughly 33,200 management had guided. Accessions grew 28%, and management attributed the gap to upfront payer-documentation requirements that are causing order cancellations, downgrades, and delays. Genome mix of outpatient insurance volume slid to 26% from 32% in Q2 and 40% in Q1. Management also acknowledged that growth in its foundational market is running below the high-20s. Analysts pressed on why the volume impact was not anticipated, which is a fair question. The full-year volume growth target has now been lowered from 33-35% at the start of the year, to at least 30%, and now to at least 28%.
The offsetting evidence is genuine. Average reimbursement rose 5% sequentially to $3,436, ahead of the roughly $3,300 guide, and management expects about $3,500 in Q4. The outpatient genome collection rate improved to 36% from 32% after two flat quarters. The share of genome claims submitted under a positive coverage policy jumped to 82% from 67%, and genome cost per test is down 43% year over year. Medicaid genome coverage expanded to 25 states. Beren Therapeutics and Mirum added to a biopharma business that grew for a second straight quarter. Management said the new general pediatrics sales force is already paying for itself and expects it to drive the most unit growth in 2027. Long-read genome sequencing and a direct-to-family online exome offering broaden the product set.
The forward risks are concrete. Management quantified PAMA for the first time as a mid-single-digit headwind to 2027 revenue, with about 45% of revenue exposed. It said revenue-cycle improvements should offset that headwind, but that remains an expectation rather than a result. Competitors are pushing genome-first and long-read testing just as GeneDx's own genome mix is falling. The exome collection rate is stuck near 32%. The Q4 guide of $135 million in revenue and 34,500 tests leaves the year at the low end of the reaffirmed $475-$490 million range, which began 2026 at $540-$555 million.
The market had already turned skeptical before the print. Shares closed at $62.37 heading into the report, down 17.9% from the open after the August release and 12.3% below the 200-day moving average. The stock sits 40.7% below its mid-September high of $105.18 and only 13.4% above the October low of $55.00. Investor sentiment, already negative, weakened modestly from -0.32 to -0.39. The Earnings Whispers trend signals lean negative on price and AVWAP, with sequential growth the notable positive reading, consistent with improving quarter-over-quarter profitability inside a deteriorating chart.
The bottom line is that GeneDx delivered a quarter of better unit economics that its bulls can point to: rising reimbursement, falling genome costs, and a swing to meaningful adjusted profit. Bears have legitimate ammunition in a third downward revision to volume expectations, shrinking genome mix, GAAP losses, cash burn, and a newly quantified PAMA headwind. The EPS beat answers the profitability question for now. Whether GeneDx can reaccelerate volume once documentation friction eases is the question the stock still has to resolve.
Read our earnings preview for GeneDx Holdings Corp.: https://www.earningswhispers.com/article/WGS/22678
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 9 hours | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-05 | |
| Nov-02 | |
| Oct-27 | |
| Oct-23 | |
| Oct-20 | |
| Oct-19 | |
| Oct-07 | |
| Oct-02 | |
| Sep-24 | |
| Sep-09 |
