USA Rare Earth Misses Badly As The Serra Verde Production Pivot Arrives Alongside Slipping Timelines And An Unreaffirmed 2027 EBITDA Target
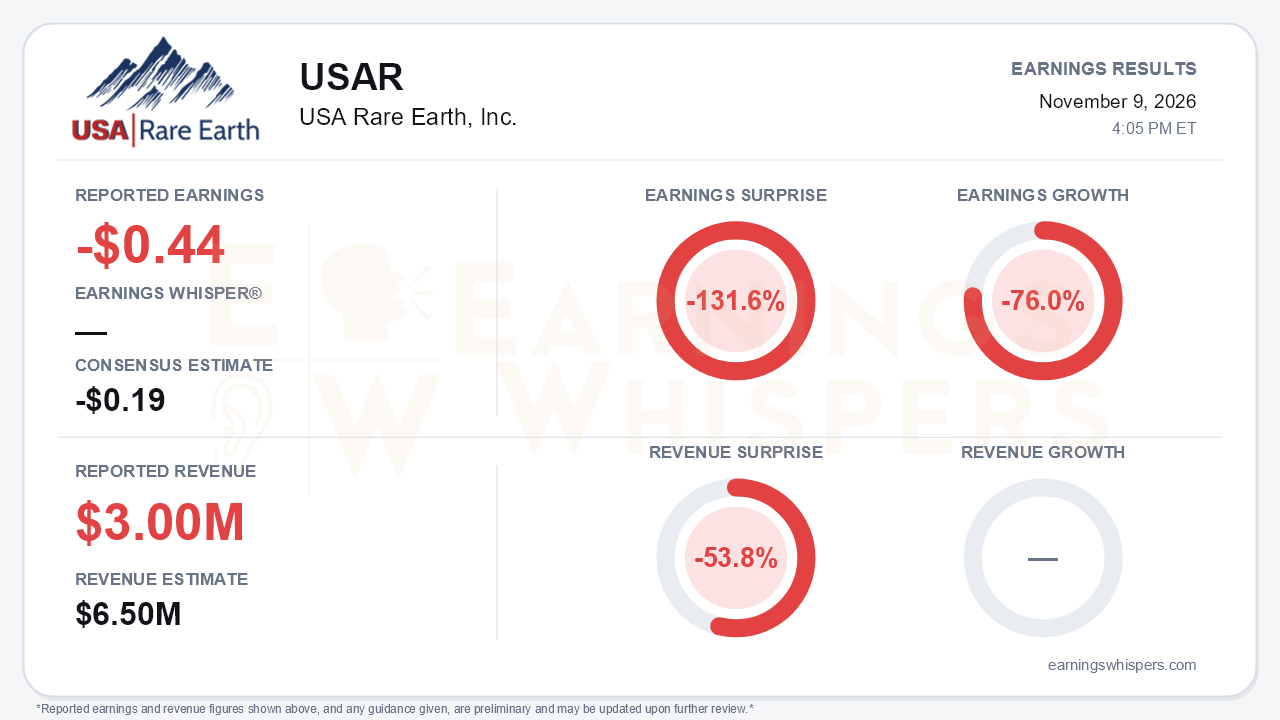
USA Rare Earth's third quarter was a split between operating progress and financial results. On the operating side, the company now has a producing mine, a selling magnet plant and a government-backed offtake. Financially, the quarter was a clear miss. The company reported an adjusted loss of $0.44 per share against a consensus estimate of a $0.19 loss, a 131.6% miss. That compares with an adjusted loss of $0.25 a year ago, and earnings fell 76.0% year over year. Revenue of $3.0 million missed the $6.5 million consensus by 53.8%. The central tension is that USAR finally crossed into commercial production with the Serra Verde combination while its near-term financials, development timelines and long-range profit target all moved the wrong way.
The headline GAAP figure needs context. Net income attributable to shareholders was $11.7 million, or $0.04 per basic share, which looks like a swing from last year's $156.7 million loss. That profit was entirely non-operating. It came from a $136.6 million gain on the fair value of financial instruments, mostly warrant and earnout liabilities, which typically fall in value when the stock drops. Diluted GAAP EPS was still a $0.02 loss. Beneath that, the operating picture was weak:
- Loss from operations widened to $141.4 million from $15.9 million.
- Cost of revenue of $22.9 million against $3.0 million of sales produced a gross loss of nearly $20 million.
- SG&A jumped to $103.7 million.
- Operating cash outflow was $143.7 million in the quarter alone.
Cash, equivalents and restricted cash of $1.16 billion remains substantial, but it is down from roughly $1.5 billion in Q2 and $1.75 billion in Q1. The Serra Verde deal also brought about $306 million of notes payable and roughly $362 million of royalty obligations onto the balance sheet.
The call explained why revenue fell by half from the roughly $6 million posted in each of the first two quarters. Shortages of dysprosium oxide and samarium metal constrained both Less Common Metals and Stillwater. That is an awkward problem for a company built on supply-chain independence. Gross margin also deteriorated for two reasons:
- Serra Verde and Stillwater startup costs are now being expensed.
- Input costs rose, while legacy LCM contracts will not be repriced until the first half of 2027.
Operating expenses of roughly $121 million compared with about $45 million in Q2 and $37 million in Q1.
The forward catalysts are real, however. Serra Verde finished Stage 1 on time and on budget and began commercial MREC shipments in October under a 15-year, 100% take-or-pay offtake. The buyer is a U.S. government-backed purchasing vehicle that raised $1.55 billion in funding, including $750 million from the Department of War. Fourth-quarter guidance calls for at least 325 tonnes of TREO. Management valued the basket at about $43/kg at floor prices and about $97/kg at current market prices, helped by non-China dysprosium and terbium prices that are multiples of Chinese levels. Other operating milestones:
- Stage 2 is 40% complete, with more than 75% of capital committed, and targets a 6,400 tpa run rate by end-2027.
- Stillwater recorded its first commercial magnet sale, though at prototype volumes.
- Magnet LOIs and MOUs held at about 2,500 tonnes.
- LCM is on track for roughly 90% volume growth in 2026.
Bears have legitimate ammunition, though. The CFO declined to reaffirm the $550-650 million exit-2027 EBITDA run-rate. For a pre-profit company, that number had anchored much of the long-term case. Timelines also slipped across the portfolio:
| Project | New timing | Prior timing |
|---|---|---|
| Round Top SK-1300 | Q3 2027, with FID in 2H27 | DFS by year-end 2026, SK-1300 early 2027 |
| Stillwater Line 1b | Q2 2027 | Q1 2027 |
| Carester start | Early 2027 | Ramp near end-2026 |
| Investor event | Early 2027 | Q3 2026 |
Management also flagged that it may not meet a Department of Commerce equity-raise milestone, and no reimbursement request has been filed despite earlier expectations. New CEO Thras Moraitis has reorganized the company into Upstream, Midstream and Downstream units. His framing is notably different from his predecessor's emphasis on speed: he now ties the pace of expansion to feedstock and demand visibility. That posture may preserve capital, but it lengthens the path to scale.
The market had already turned hard against the story before the report. Shares closed at $8.23 on November 6, down 56.1% from the $18.73 open after the August report. The stock sits about 56% below its $18.65 200-day moving average. Shares peaked at $20.52 in late August and set a 52-week low of $6.84 on November 5, leaving them only about 20% off that trough heading into the release. Investor sentiment swung from modestly positive (0.16) to modestly negative (-0.16), a meaningful reversal, though not an extreme reading. Expectations were already depressed, which partly explains why a large miss arrived into a stock that had lost more than half its value.
The bottom line is that USAR delivered the operational milestones that matter most for its mine-to-magnet thesis: Serra Verde is selling under a take-or-pay contract and Stillwater has made its first magnet sale. The quarter's financials, however, showed heavier spending, falling revenue and a shrinking cash cushion. Combined with slipping timelines and the unreaffirmed 2027 EBITDA target, the story now depends on execution evidence rather than ambition. Fourth-quarter Serra Verde volumes and realized pricing are the next real test.
Read our earnings preview for USA Rare Earth, Inc.: https://www.earningswhispers.com/article/USAR/22791
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 3 hours | |
| 4 hours | |
| 4 hours | |
| Nov-03 | |
| Nov-02 | |
| Nov-02 | |
| Nov-02 | |
| Oct-30 | |
| Oct-26 | |
| Oct-14 | |
| Oct-07 | |
| Oct-07 | |
| Oct-01 | |
| Sep-29 |
