Quantum Corp. Crushes Estimates And Doubles Its Backlog, But A Supply-Gated Q3 Guide Tempers The Acceleration
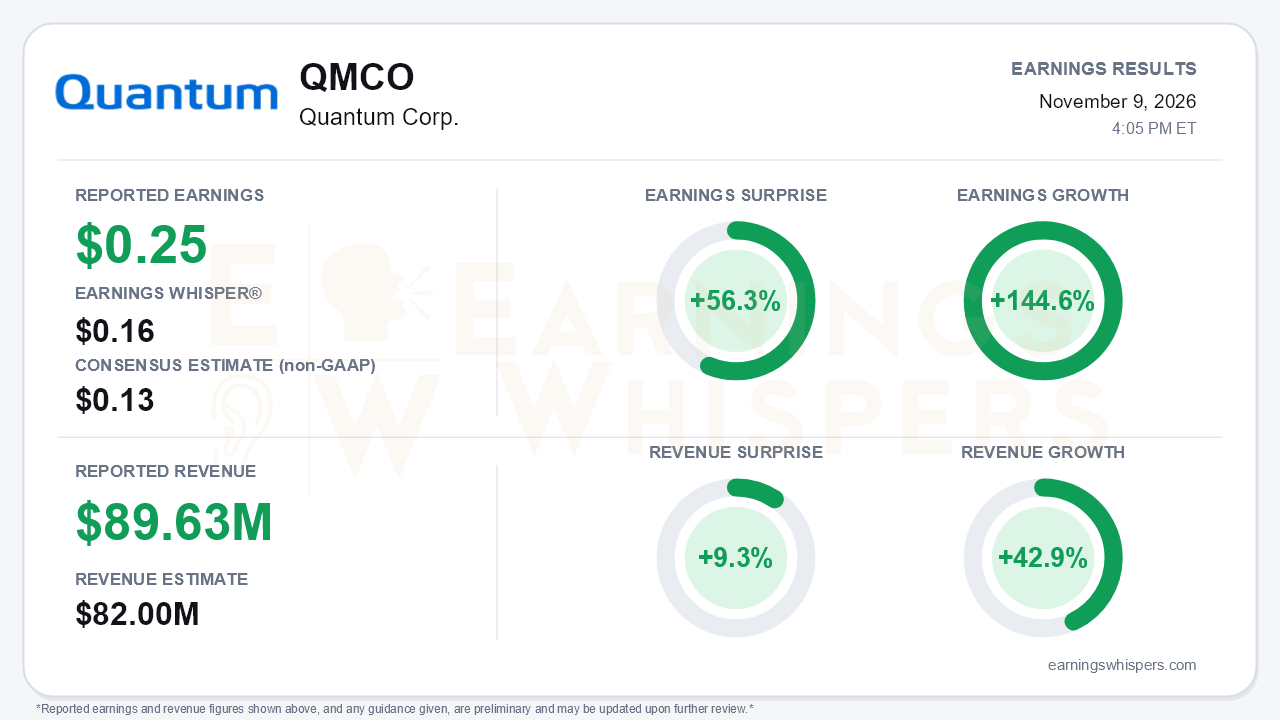
Quantum Corp. (NASDAQ: QMCO) delivered the cleanest operating quarter it has posted in years. Non-GAAP earnings were $0.25 per share, well ahead of the $0.13 consensus and the $0.16 Earnings Whisper number, a 56.3% surprise. Revenue of $89.63 million beat the $82.0 million consensus by 9.3% and grew 42.9% year over year. That is a sharp acceleration from roughly 26% to 27% growth in the prior two quarters. Earnings grew 144.6% year over year, a swing from an adjusted loss of $0.54 per share to a $0.25 profit. The central tension is that fiscal third-quarter guidance points to a near-pause in sequential growth just as demand indicators are hitting records. Management attributes the gap to supply rather than demand.
The quality of the beat holds up better than the GAAP line suggests. Gross margin reached 41.0%, up 170 basis points sequentially and 340 basis points from a year ago. Adjusted EBITDA of $11.1 million cleared the top of guidance by $4.1 million, and the GAAP operating line swung to a $6.8 million profit from an $8.2 million loss. The $44.8 million GAAP net loss is almost entirely a $51.6 million non-cash warrant fair-value charge, which moves with Quantum's own stock price. Per-share comparisons also deserve a caveat. Weighted shares nearly tripled to 39.4 million from 13.3 million after the convertible-note conversion and a $94.3 million private placement. Adjusted net income of $9.8 million, versus a $7.1 million loss a year ago, is the fairer read. That recapitalization also leaves Quantum debt-free with $67.5 million in cash, a transformation from $16.2 million in cash and about $56 million of term debt in March.
The call reinforced that demand is not the constraint. Backlog reached nearly $100 million, up from $45 million at fiscal year-end and just over $20 million two quarters before that. Several data points supported the demand picture:
- Hyperscale tape demand rose 2.6 times year over year, and four hyperscalers are now doing multi-quarter demand planning.
- Quantum landed one of the largest purchase orders in its history, a Scalar i7 Raptor hyperscale deployment that followed a multi-year evaluation.
- It also booked its largest-ever ActiveScale order.
- The core channel grew about 30%, and deals above $1 million rose 50%.
- A China distribution partner went from zero to well above $30 million in a year.
Management also raised its gross-margin ambition to roughly 43% within 18 months. In prior calls the goal had been a recovery toward 40%.
The guidance is where the caution lies. Third-quarter revenue guidance of $91 million, plus or minus $2 million, sits well above recent guide levels. Even so, the midpoint implies only about 1.6% sequential growth, and year-over-year growth would slow to roughly 22%. EBITDA guidance of $9.1 million is below the $11.1 million just reported, because non-GAAP operating expenses step up to about $28 million on commissions and R&D hiring. The upside depends on suppliers:
- IBM tape-drive ramp timing remains unknown.
- Sony media supply is expected to be flat next year.
- Hard drives were secured, but at higher prices.
- Fujifilm's plan to quintuple tape media output helps over time, not immediately.
Other soft spots include a flat mid-market and SMB pricing resistance on tape drives. Second-quarter operating cash flow of roughly $14 million was partly helped by payables timing. The CFO's absence from the call, alongside a new COO and new finance leadership, adds an execution question.
The market setup is more complicated than the surprise implies. Shares spiked to a 52-week high of $35.65 on October 5, then collapsed to an inter-earnings low of $12.87 on November 5. They entered the report at $14.47, essentially flat (-0.3%) from the open after the prior report, 59.4% below that peak and 9.1% above the 200-day average. The October spike likely helps explain the large warrant charge as of September 30. Because the company says warrant values depend on its stock price, the subsequent decline could swing that GAAP item the other way. Investor sentiment cooled sharply, falling from a solidly positive 0.35 to roughly neutral at -0.02. That leaves expectations reset well below where they stood a quarter ago. Earnings Whispers trend readings are mixed, with momentum positive but AVWAP negative, consistent with a stock still digesting a failed breakout.
The bottom line is that Quantum's turnaround moved from promise to proof this quarter. It delivered accelerating revenue, expanding margins, a doubled backlog and a clean balance sheet. The near-term story, however, is now about supply rather than demand. A flat-ish third-quarter guide and higher operating expenses mean the next leg depends on IBM drives and tape media arriving on time. After a round-trip from $35 to the low teens and a sharp cooling in sentiment, the bar heading forward looks considerably lower than the fundamentals alone would suggest.
Read our earnings preview for Quantum Corp.: https://www.earningswhispers.com/article/QMCO/22665
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-08 | |
| Nov-03 | |
| Nov-02 | |
| Oct-27 | |
| Oct-19 | |
| Oct-05 | |
| Sep-28 | |
| Sep-14 | |
| Sep-11 | |
| Sep-10 | |
| Sep-10 | |
| Sep-08 |
