OraSure Beats On The Bottom Line, But A Delayed Cash-Breakeven Target Overshadows Margin Progress
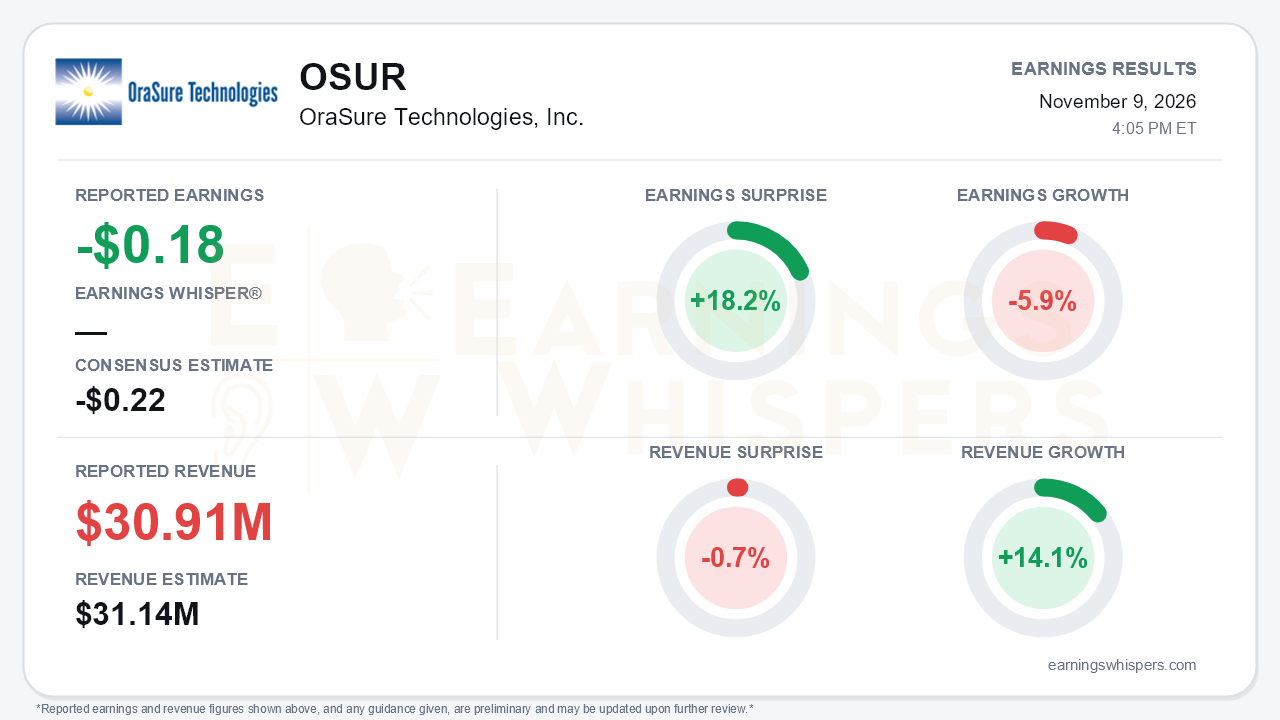
OraSure Technologies delivered a third quarter that looked better operationally than its headline numbers, but the call moved the timing of its most important financial commitment. On Earnings Whispers' normalized basis, the company lost $0.18 per share, beating the -$0.22 consensus by 18.2%. Earnings still fell 5.9% year over year. The press release shows a GAAP loss of $0.19, unchanged from a year ago, and a non-GAAP loss of $0.15, wider than the prior year's $0.13. Revenue of $30.91 million rose 14.1% year over year but missed consensus by 0.7%, and the fourth-quarter outlook came in below estimates. The central tension is that margins and costs are clearly improving, while the path to self-funding has been pushed out. Management now targets operating cash flow breakeven in the second half of 2027, not 'entering 2027' as previously promised.
The quality of the improvement is real but uneven. GAAP gross margin rose to 45.2%, up from 43.5% a year ago. It has also climbed steadily from 41.0% in the fourth quarter of 2025, then 42.3%, then 43.5%. Management credited better fixed-overhead absorption from operational efficiencies. Spending cuts are visible too:
- R&D fell to $7.6 million, from $13.7 million in the first quarter and $9.4 million in the second.
- G&A eased to $12.0 million from $14.4 million.
- The non-GAAP operating loss narrowed to $10.2 million, from $19.0 million in the first quarter and $12.7 million a year earlier.
Those gains did not reach non-GAAP net income, which slipped to a $10.1 million loss from $9.8 million. The main drag was other income, which dropped to $1.2 million from $2.8 million as the cash pile shrank. A lower share count was not enough to offset it. Investors should also note that the nine-month GAAP comparison is flattered by a $22.5 million gain from contingent consideration, which makes the year-to-date narrowing of losses look larger than it is.
The revenue mix also deserves scrutiny. Sample Management Solutions drove the quarter, reaching $12.5 million. That was up 21% year over year and up from $9.9 million in the second quarter. However, management attributed part of that strength to the timing of specific orders and expects it to soften in the fourth quarter. Diagnostics grew 16% year over year to $16.8 million, helped by HIV, HCV, and the acquired Sickle SCAN line. Sequentially, though, Diagnostics fell from $19.4 million. Total revenue grew only 1% from the second quarter. The fourth-quarter guidance of $30 million to $32 million implies 12% to 20% year-over-year growth, but roughly flat sequential revenue. Management also guided fourth-quarter gross margin similar to or slightly below the third quarter.
The catalyst story is intact, but it is running late. Colli-Pee•Dx and OraQuick Ebola 2.0 both generated initial orders in the quarter, and early HPV development for Colli-Pee is underway with global molecular diagnostics partners. Ebola adoption, however, now depends on new African-led evaluation and procurement processes. Results from the Bridge Access Study are still pending, and the CEO acknowledged she would have expected them already. The CT/NG IntelliQuick test remains in FDA pre-submission with no resubmission timeline and a possible additional clinical trial. On the second-quarter call, management said the CT/NG delay would not change the breakeven target. Bears therefore have legitimate ammunition on execution credibility. The offset is management's first look at 2027, which calls for full-year revenue growth to accelerate from 2026's roughly 4.7% midpoint pace.
Balance-sheet runway is adequate but is being consumed. Cash fell to $148.2 million from $161 million at the end of the second quarter and $199 million at year-end. Third-quarter operating cash flow was -$10.9 million, and share buybacks remain paused.
The market had already turned skeptical before the report. As of the pre-report snapshot, shares were down 17.1% since the open following the August release, at $3.44. That left them about 2.6% below the 200-day moving average. The stock briefly reached $4.38 in late October but had given back most of that spike, sitting 21.5% below the high and just 9.4% above the September low of $3.15. Investor sentiment was mildly positive at 0.11, which suggests cautious rather than enthusiastic expectations. The Earnings Whispers trend readings are mostly neutral, with AVWAP still negative.
The bottom line is that OraSure is executing on the parts of the plan it controls, including gross margin, operating expenses, and loss reduction. The parts that depend on regulators, procurement bodies, and order timing keep slipping. Pushing out cash breakeven, alongside a flat sequential guide and a modest revenue miss, makes the 2027 acceleration call the key promise investors will now hold management to.
Read our earnings preview for OraSure Technologies, Inc.: https://www.earningswhispers.com/article/OSUR/22657
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-02 | |
| Nov-02 | |
| Oct-26 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Jul-22 | |
| Jul-21 | |
| Jun-11 | |
| May-06 | |
| May-06 | |
| Apr-22 |
