Coherus Misses On Both Lines As Loqtorzi Stalls, Guidance Is Cut And A Going-Concern Warning Overshadows An Esophageal Signal
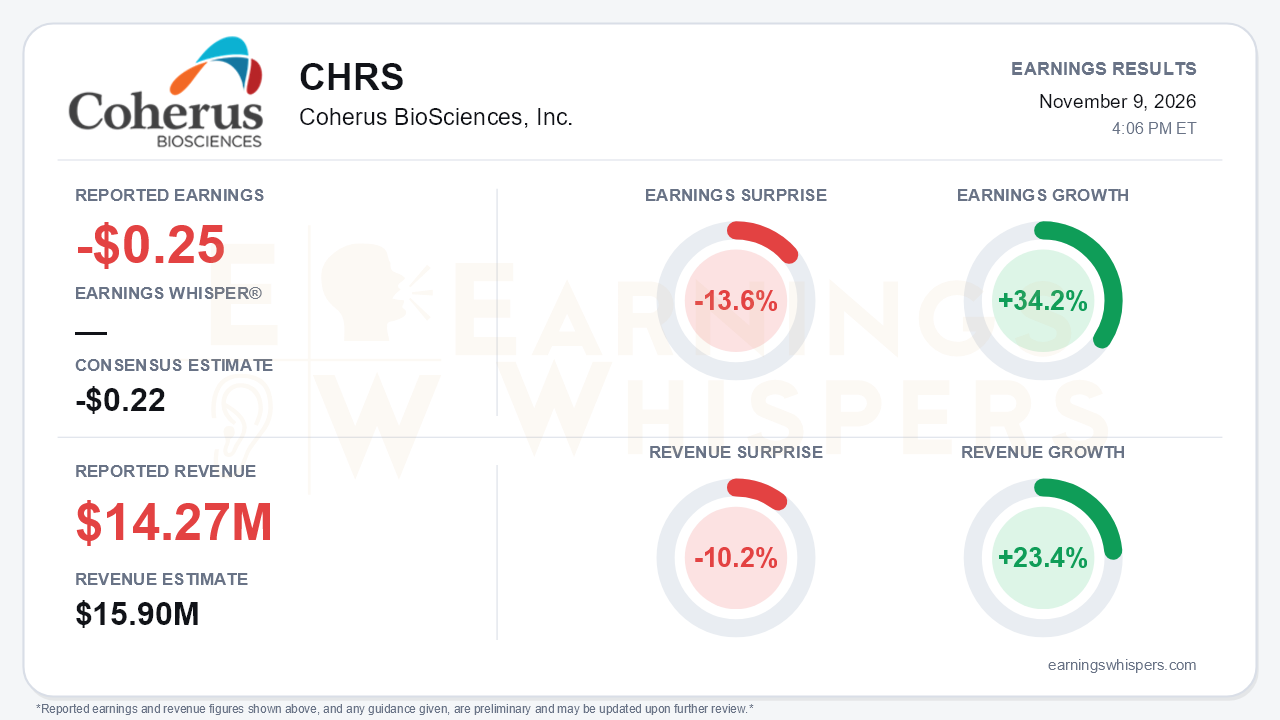
Coherus (NASDAQ: CHRS) delivered a quarter that turned its story from steady build to retrenchment. The company reported a loss of $0.25 per share on revenue of $14.27 million. That missed the consensus estimate of a $0.22 loss by 13.6%, and revenue fell 10.2% short of the $15.9 million consensus. Year over year, the comparisons still look healthy: earnings improved 34.2% and revenue grew 23.4%. The misses matter less than what came with them. Management cut full-year Loqtorzi guidance, cut headcount by about 30%, narrowed the pipeline, and disclosed going-concern language with cash runway now under 12 months. The one genuinely encouraging development, an esophageal cancer signal for tagmokitug, arrives just as the balance sheet has become the dominant issue.
The quality of the quarter deserves scrutiny on both sides. The GAAP loss of $0.25 included a $3.4 million loss on debt extinguishment from refinancing a term loan. On a non-GAAP basis, the loss was $0.20 per share, compared with $0.33 a year ago. The year-over-year improvement in losses is real and came mainly from the expense side:
- R&D fell to $22.6 million from $27.3 million.
- SG&A fell to $21.2 million from $24.9 million.
- Operating cash use dropped to $34 million, about 43% below the first-half quarterly average.
The top line is the problem. Loqtorzi revenue reached $14.0 million, up 25% year over year but only 3% sequentially. Management had guided to 10-15% average quarterly growth on its prior three calls, and the second quarter had grown roughly 15%. Growth decelerated sharply.
The call made the slowdown more consequential. Management:
- cut full-year Loqtorzi guidance to $54-57 million from $57-62 million;
- narrowed the target for a $15 million quarter to the fourth quarter only;
- did not reiterate the 2027 goal of $30 million or more per quarter.
Management blamed lumpy patient flow in a rare disease, and it cited a physician survey in which 75% view Loqtorzi as the standard of care in nasopharyngeal carcinoma. Even so, market share sits at only about 20-22%, with roughly 30% of patients on chemo alone and 40% on off-label IO. The cost cuts lower the quarterly Loqtorzi revenue needed to cover core burn to $25-30 million from $30-35 million. That is a real efficiency gain. It is also a target roughly double current sales, which turns CEO Denny Lanfear's "path to financial self-sufficiency" over the next four or five quarters into a demanding bet on reaccelerating share.
The balance sheet is the central tension. Cash and investments fell to $83.6 million from $105.3 million at the end of the second quarter and $172.1 million at year-end. That balance also includes $19.6 million of Transition Services Agreement collections owed to others. Two other items weakened the cash outlook:
- **Refinancing:** The new $55 million term loan added only about $11.5 million net.
- **Udenyca earn-out:** The first $37.5 million milestone was narrowly missed on the buyer's reported figures. Management had earlier described itself as favorably positioned, and recovery now depends on an audit dispute.
The earlier assurance that the company was funded through its 2026-2027 readouts no longer stands. Dilution or financing risk is elevated, and bears have legitimate ammunition.
The pipeline offers the counterweight, but a thin one in size. In second-line esophageal cancer, the 700 mg dose of tagmokitug plus toripalimab produced a 33.3% confirmed response rate and a 55.6% clinical benefit rate, with median progression-free survival of 5.5 months. The call framed this against a chemotherapy benchmark of roughly 10%. The 300 mg dose produced no responses, which supports dose dependence. However, the call describes the result as nine evaluable patients at 700 mg, while the release's narrative refers to 13 evaluable patients across the cohorts. Either way, the sample is very small. A first-line ESCC safety cohort showed 8 of 9 responders.
Several catalysts are now scheduled:
- An FDA Type B meeting on an accelerated-approval design is targeted for around March 2027.
- An advisor has been engaged to pursue ex-U.S. partnering, which could bring upfront cash.
- The PDUFA date for transferring toripalimab drug-product manufacturing is November 30.
- Casdozokitug's Phase 2 liver cancer readout is expected in the first half of 2027.
The cost of this focus is a narrower story: head and neck, upper GI adenocarcinoma, and other indications were deprioritized after earlier calls promoted a broad Treg platform.
The market had largely anticipated trouble. Shares fell 44.2% from the $1.38 open after the August report to $0.77 before this release. That left the stock about 49% below its 200-day moving average of $1.51 and just above the 52-week low of $0.73 set on November 5. Price and AVWAP trend readings are negative. Investor sentiment remained positive but softened modestly, slipping to 0.27 from 0.34. That decline is far milder than the stock's slide and suggests holders were still extending some benefit of the doubt heading into a report that withdrew several prior commitments.
The bottom line is that Coherus traded growth credibility for survival discipline this quarter. Lower burn and a credible-looking esophageal signal give the story a narrower, more focused path. However, stalled Loqtorzi growth, reduced guidance, a disputed earn-out, and going-concern language shift the burden of proof to financing and partnering outcomes. Until those arrive, the clinical upside will compete directly with dilution risk.
Read our earnings preview for Coherus BioSciences, Inc.: https://www.earningswhispers.com/article/CHRS/22615
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-02 | |
| Oct-28 | |
| Oct-27 | |
| Oct-26 | |
| Oct-14 | |
| Sep-23 | |
| Aug-31 | |
| Aug-17 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Jul-22 |
