The Trade Desk Clears A Lowered Bar By A Wide Margin, But Its Q4 Guide Points To Steeper Decline
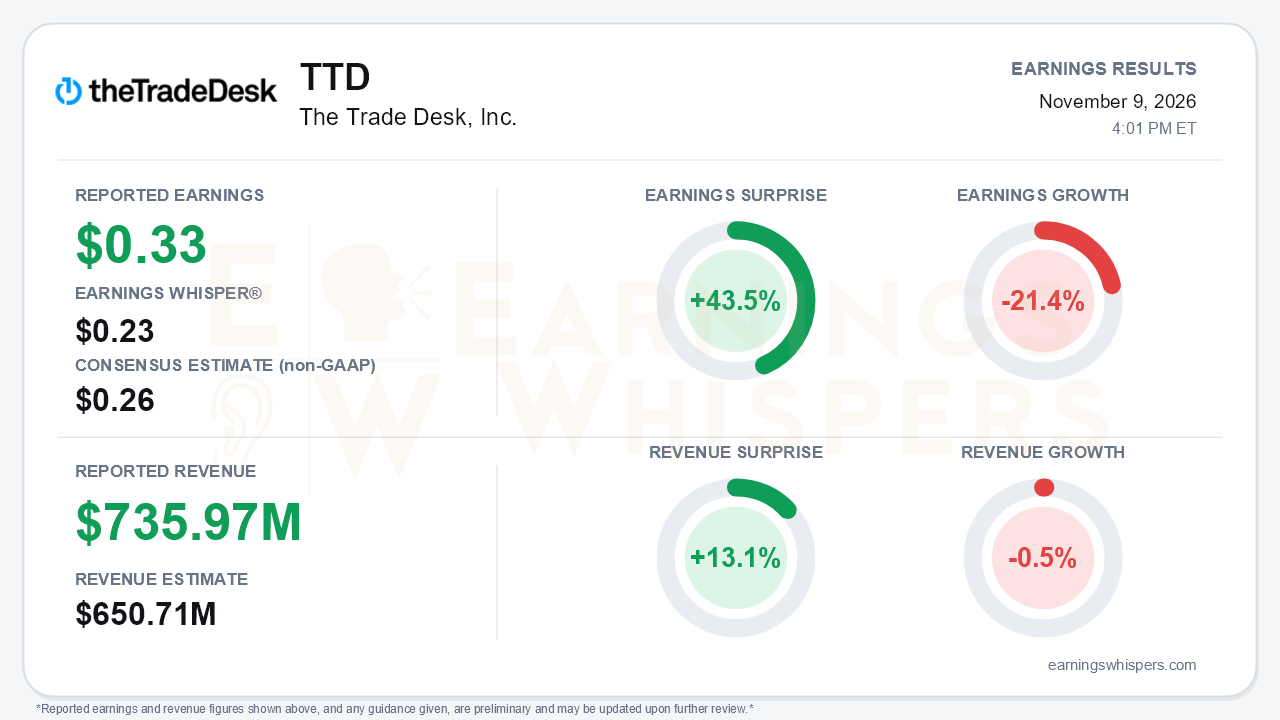
The Trade Desk delivered a decisive beat against expectations that had been reset sharply lower. Non-GAAP EPS of $0.33 topped the $0.26 consensus by 43.5% and cleared the $0.26 Earnings Whisper number. Revenue of $735.97 million beat the $650.71 million consensus by 13.1%. Yet earnings still fell 21.4% year over year and revenue slipped 0.5%, the first year-over-year decline in the sequence the company has been tracing. That is the central tension. The quarter beat a low bar handily, but the growth trajectory is still heading the wrong way. Year-over-year revenue growth has gone from 14% in Q4 FY25 to 12% in Q1, 3% in Q2 and now slightly negative.
The quality of the beat deserves scrutiny. The consensus revenue figure sat almost exactly on management's own guidance floor of at least $650 million, so the upside partly reflects how conservatively that floor was set. According to the call, about 3 points of Q3 revenue came from non-recurring strategic-partner revenue. A record midterm political cycle contributed a mid-single-digit share of revenue. On a GAAP basis the picture is considerably weaker:
- GAAP net income fell to $38 million, or $0.08 per diluted share, from $116 million, or $0.23.
- A $44 million restructuring charge weighed on GAAP results.
- A $68 million tax provision was heavy against $106 million of pretax income.
- Platform operations expense rose 23% year over year, and income from operations dropped to $93 million from $161 million.
Adjusted EBITDA of $266 million came in at a 36% margin. That is down from 43% a year ago, though it far exceeded the roughly $160 million guide. Margin has improved sequentially from 30% in Q1 and 34% in Q2. A 4.6% lower diluted share count also cushioned per-share results.
The call marked a clear shift in posture. CEO Jeff Green moved from the defensive, macro-heavy framing of the Q2 call to an execution narrative. Co-founder Dave Pickles is returning in an expanded role, and the company is pushing new products:
- Kokai Zuma launched with a median 21% CPA improvement across 62 A/B-tested campaigns.
- Audience Unlimited has 100+ advertisers testing, showing more than 30% CPA gains and roughly 14% lower CPMs.
- Open Measurement formally launches in Q4.
- Netflix's expanded integration lets advertisers apply first- and third-party data inside Kokai starting in November.
A roughly 15% workforce reduction is expected to yield more than $100 million in gross savings in 2027. Even so, the release itself frames this as a company still operating below the growth level it expects of itself.
The forward picture is where bears have legitimate ammunition. Q4 guidance calls for revenue of at least $755 million and adjusted EBITDA of at least $280 million. That revenue figure implies roughly an 11% year-over-year decline against $847 million. One analyst on the call estimated the underlying decline at about 16% excluding political spend and the one-time benefit, versus about 8% in Q3. Management is not expecting the usual seasonal uplift, and large global advertisers remain under pressure, with persistent weakness in CPG and auto. The comparison to last year's roughly $400 million, 47%-margin Q4 EBITDA is stark. The FY26 target of at least a 40% adjusted EBITDA margin, reaffirmed as recently as Q1, was not reiterated, and the implied full-year figure is about 34%. Leading indicators are also cooling:
- JVP growth slowed from +55% to +38% to +30%.
- China growth fell from over 100% year-to-date to 45%.
- EMEA growth eased from about 30% to above 20%.
CFO Nate Olmstead flagged that election-year Q4-to-Q1 declines have historically run around 25% as political dollars roll off.
Capital return offers some support. The buyback authorization was lifted to $1 billion, and the balance sheet holds about $1.65 billion in cash and short-term investments. Repurchases totaled only $241 million through nine months versus $958 million a year earlier, however. Free cash flow improved to $153 million from $136 million in Q2, and the company reports no debt on its balance sheet.
Investor sentiment improved meaningfully heading into the print, rising from -0.61 to -0.32, but it remains firmly negative. Price action reflects that skepticism. Shares at $12.93 were essentially flat (+0.5%) from the open after the August report and sat 34% below the 200-day moving average of $19.59. They were 15.5% below the September 15 inter-earnings high of $15.31 and 11.3% above the October 7 low of $11.62, which was also a 52-week low. Most of the Earnings Whispers trend signals, including momentum and AVWAP, remain negative.
The bottom line is that The Trade Desk beat a deliberately low bar with room to spare and sounded more like a company regaining its footing, with credible product traction and cost discipline. The numbers that matter most for the next several quarters still point down: an implied double-digit Q4 revenue decline, a lapsed 40% margin target, decelerating leading indicators, and a political tailwind that reverses in Q1. Until the new products show up as reaccelerating top-line growth rather than better CPA statistics, this remains an improving narrative attached to a still-deteriorating revenue base.
Read our earnings preview for The Trade Desk, Inc.: https://www.earningswhispers.com/article/TTD/22675
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-04 | |
| Nov-03 |
Byron Donalds Could Be Next Florida Governor: Here Are the Stocks He's Been Buying in 2026
TTD
Benzinga Prediction Markets
|
| Nov-03 | |
| Nov-03 | |
| Nov-02 | |
| Oct-27 | |
| Oct-24 |
How Trade Desk Rescued Executives' Stock Options From a Dive in the Share Price
TTD
The Wall Street Journal
|
| Oct-22 |
