Rocket Lab's Record Backlog And Neutron Pricing Power Collide With A 2027 Launch Slip And A Messy GAAP Miss
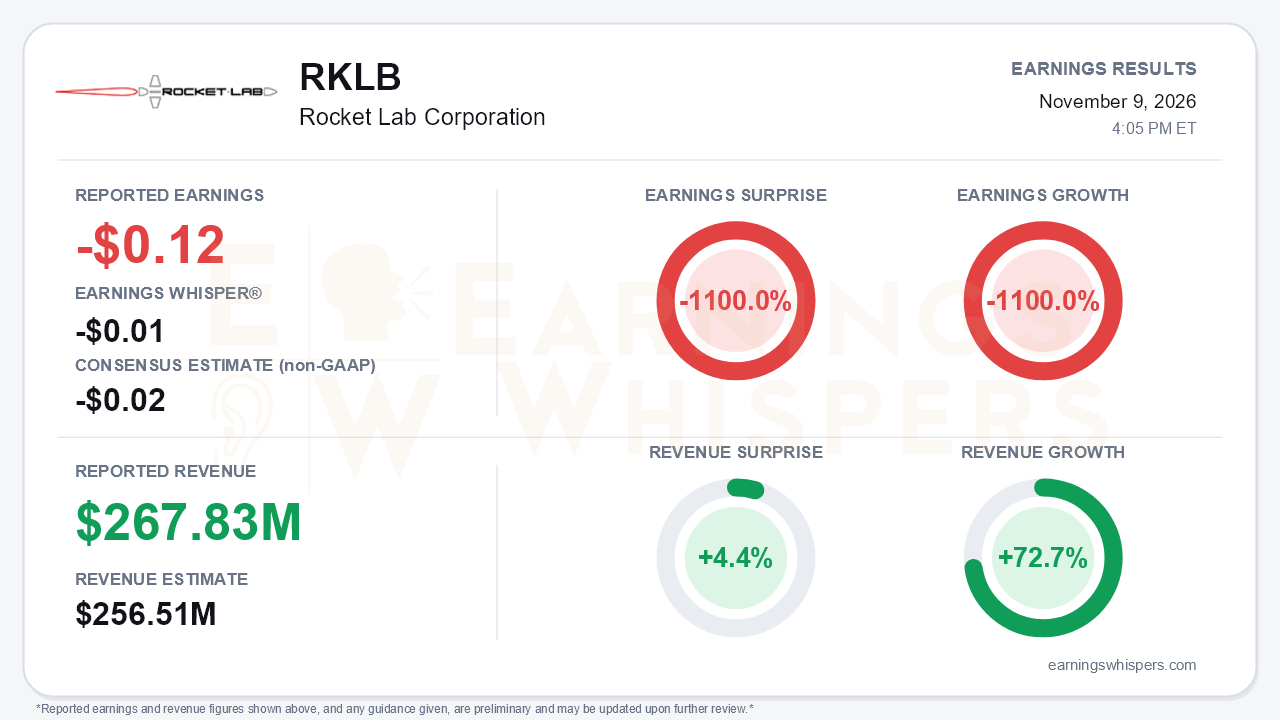
Rocket Lab's third quarter split cleanly into two stories. The GAAP loss of $0.12 per share missed the -$0.02 consensus by 1100.0% and the -$0.01 Earnings Whisper number, and was 1100.0% worse than a year ago. The commercial side was strong: revenue rose 72.7% to a record $267.83 million, beat the $256.51 million consensus by 4.4%, and cleared management's own $250-265 million guide. Backlog rose 52% in a single quarter to $3.57 billion. The central tension is that bookings and pricing have never looked better, while the Neutron rocket that underpins the long-term thesis has slipped again, this time into 2027.
The headline miss deserves context rather than alarm. The reported figure is GAAP, while consensus was on a non-GAAP basis. Several items weighed on the bottom line:
- a $27.3 million loss on debt extinguishment;
- $21.3 million of transaction costs tied largely to the pending Iridium acquisition;
- a $3.5 million tax provision.
The tax line matters for the comparison. The year-ago quarter's $18.3 million net loss was flattered by a $41.1 million tax benefit, which distorts the year-over-year EPS comparison. On an operating basis, the non-GAAP operating loss narrowed to $27.4 million from $33.2 million a year earlier. Operating cash flow turned positive at $7.2 million, against an $84.1 million outflow in Q2. Weighted shares also rose to 652 million from 529 million, a reminder that the $4.7 billion liquidity cushion was built with roughly $3.9 billion of ATM equity this year.
The quality concerns sit in the margin line. GAAP gross margin did beat guidance at 33.6% versus 29-31%, and non-GAAP margin came in at 38.4%. But GAAP margin has declined three straight quarters, from 38.2% in Q1 to 36.1% in Q2 to 33.6%, on mix and the drag from Mynaric. Adjusted EBITDA loss widened sequentially to $18.0 million from $8.8 million in Q2, though it improved from $26.3 million a year ago. GAAP operating expenses of $169.3 million ran well above the $143-149 million guide because of Iridium-related costs.
Demand is where the call was most convincing, and management's tone was the most confident of the year. Rocket Lab signed:
- 54 launches and more than $1 billion of launch contracts, including 18 HASTE missions for Space Systems Command and 20 Electron launches for Synspective;
- eight Neutron missions worth about $515 million;
- $470 million of Space Systems orders.
The Neutron contracts lifted the base price to $70 million from the $50-55 million cited previously. Management said it turned away lower-priced volume, flagged Electron and HASTE price increases, and suggested 2027 small-launch growth could exceed 20%. Launch now represents 52% of backlog, versus 26% at the end of 2025. That is genuine pricing power, and it is the strongest evidence yet that tight industry launch capacity is working in Rocket Lab's favor.
Bears still have legitimate ammunition. Neutron's first flight, promised for Q4 2026 as recently as earlier this year, moved to 2027 after voids were found in the forward dome, and management declined to name a quarter. The company also booked a forward loss reserve on Neutron Flight 2. Management pushed the path to cash-flow positivity beyond six quarters after first launch and raised the possibility of extra capex. Near-term growth also cools: the Q4 guide of $270-290 million implies only about 4.5% sequential growth at the midpoint, with Space Systems expected to decline. The next-12-month backlog conversion ratio fell to 32.9% from 45.5%, meaning more of that record backlog is long-dated. Iridium regulatory approvals and government budget uncertainty remain open items.
The market had already priced in plenty of doubt. Shares entered the report at $53.07, down 30.4% since the open after the August report. That leaves them 32.8% below the 200-day moving average and 38.0% below the August 17 high of $85.55, though 20.9% above the November 5 low of $43.89. Investor sentiment stayed slightly positive but weakened, slipping to 0.03 from 0.08. Earnings Whispers trend readings are mixed: sequential growth and momentum are positive, while price and AVWAP trends remain negative.
The bottom line is that Rocket Lab delivered a demand quarter, not an earnings quarter. Record revenue, a $3.57 billion backlog, and a 30%-plus Neutron price increase strengthen the long-term franchise. The GAAP miss is largely explained by deal costs, debt extinguishment, and tax comparisons. But the Neutron delay, eroding GAAP margins, a decelerating Q4, and slower backlog conversion push the payoff further out. For a stock already trading far below its 200-day average, the debate now centers on execution timing rather than demand.
Read our earnings preview for Rocket Lab Corporation: https://www.earningswhispers.com/article/RKLB/22668
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 20 min | |
| 1 hour |
Rocket Lab Retreats On Mixed Q3 Report, Analysts Say Neutron Timing Is Key
RKLB
Investor's Business Daily
|
| 2 hours | |
| 2 hours | |
| 3 hours | |
| 4 hours | |
| 4 hours | |
| 4 hours | |
| 5 hours | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 |
