Babcock & Wilcox Misses On Normalized EPS As Warrant Gain Flatters GAAP Results And The Data Center Award Slips Into 2027
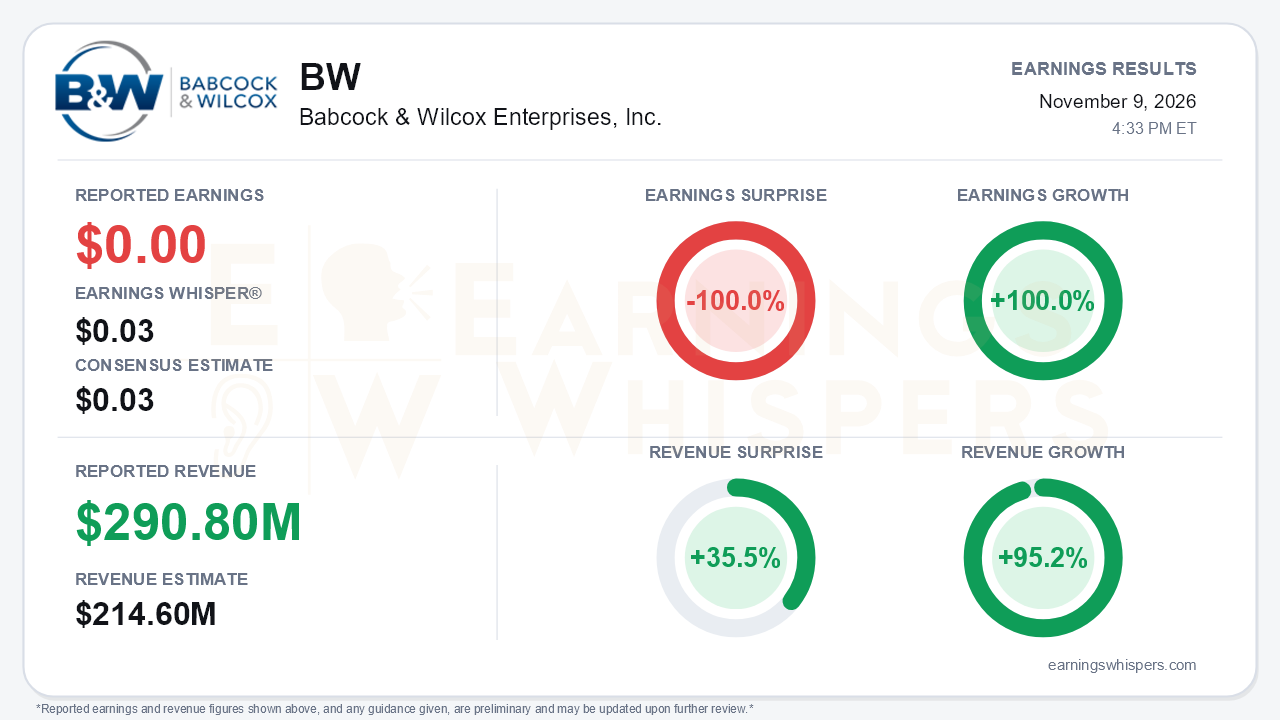
Babcock & Wilcox delivered a quarter where the top line and the bottom line tell very different stories. On a normalized basis, the company reported breakeven earnings of $0.00 per share. That missed both the $0.03 consensus estimate and the $0.03 Earnings Whisper number by 100.0%, although earnings still grew 100.0% from a year ago. Revenue was $290.8 million, 35.5% above the $214.6 million consensus and up 95.2% year over year by Earnings Whispers' measure. The company cites 109% growth against its reported prior-year figure of $139.2 million. Large project volume drove the increase, including $77.8 million from the Base Electron data center job. The central tension is that B&W is growing revenue rapidly but converting very little of it into earnings, while the catalyst that underpins the bull case, a second data center award, has slipped.
The quality of the reported profit deserves scrutiny. GAAP net income of $93.9 million and basic EPS of $0.61 look strong, but they rest on an $85.1 million non-cash gain from revaluing customer warrants tied to Applied Digital and Base Electron. That gain arose because the stock price fell during the quarter. Strip out the warrant and stock-appreciation-rights effects, and adjusted net income was just $4.8 million. Diluted EPS from continuing operations was $0.02. Operating income did improve to $13.8 million from $3.4 million, but cost of operations rose faster than revenue as construction-heavy work grew in the mix. Adjusted EBITDA of $17.7 million was up 88% year over year but down from $21.8 million in the second quarter. Revenue also fell sequentially from $319.7 million.
The conference call reinforced that the growth trajectory flattened this quarter. Management said gross margin was again pressured by project mix and a labor-availability problem on one construction project. That issue was first flagged in the second quarter and is now expected to run through year-end. Backlog has drifted lower every quarter as large projects burn off, falling from $2.8 billion at the end of 2025 to $2.5 billion. Working capital also absorbed cash. Receivables more than doubled from year-end to $260.0 million, and nine-month operating cash flow was negative $130.3 million. Cash and restricted cash fell to $128.9 million from $382.8 million in the second quarter, reflecting the bond retirement, $38 million of buybacks and the receivables build. Management expects strong fourth-quarter cash flow, but that remains an expectation, not a result.
The demand narrative is where bulls still have material to work with:
- **Bookings:** Third-quarter bookings rose 112% to $228 million, including record parts and services bookings.
- **Pipeline:** The pipeline expanded to more than $16 billion, from more than $14 billion last quarter. More than $10 billion of that is utility and industrial work outside data centers.
- **2027 target:** Management issued a first fiscal 2027 adjusted EBITDA target of $125 million to $140 million and called it conservative. Management said roughly 75% is backed by backlog or book-and-bill work. The release notes these targets are not formal guidance.
- **2026 target:** Reaching the reaffirmed 2026 range of $80 million to $105 million requires a sizable fourth-quarter step-up from the $55.5 million earned through nine months.
The softer points matter just as much. On the second-quarter call, management expected a second data center full notice to proceed this year and had reserved 1 gigawatt of Siemens turbines. That award has not been booked. It is now framed as partial bookings in the fourth quarter followed by full notices in the first quarter of 2027. Management referenced recent elections and capital-market sentiment while shifting emphasis toward non-data-center demand. Base Electron also went from "ahead of expectations" last quarter to "on track." None of these changes is a cancellation, but the cumulative tone is more hedged.
The balance sheet improved in some respects and was diluted in others. Total debt fell to $166.4 million from $276.8 million after the December 2026 bonds were fully retired. Stockholders' equity swung to a positive $109.6 million from a deficit at year-end. However, the improvement came partly from $259.6 million of equity issuance this year, and the basic share count rose to 147.3 million from 103.0 million a year ago. The $38 million buyback offsets only a fraction of that dilution.
The market had already priced in much of this skepticism. Shares opened at $11.86 after the August report and peaked at $12.08 that day. They then slid to a 52-week low of $3.07 on November 5, just days before this release. That left them deep below the $11.33 200-day moving average and near the bottom of the inter-earnings range. Price and AVWAP trend readings are negative, though momentum is positive. Investor sentiment entered the prior report mildly positive at 0.23, and no updated reading is available to show how expectations shifted during the collapse.
The bottom line is that B&W beat handily on revenue but missed on normalized earnings. The headline GAAP profit is largely a warrant accounting gain created by the stock's decline. The 2027 EBITDA target and the expanding pipeline keep a credible growth story alive. However, sequentially lower revenue and EBITDA, a shrinking backlog, cash burn and a delayed data center award give bears legitimate ammunition. With shares already near their lows, the next proof points are converting those $200 million-plus negotiations into actual notices to proceed and delivering the promised fourth-quarter cash flow.
Read our earnings preview for Babcock & Wilcox Enterprises, Inc.: https://www.earningswhispers.com/article/BW/22613
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 9 hours | |
| Nov-09 | |
| Nov-09 | |
| Nov-05 | |
| Nov-02 | |
| Oct-26 | |
| Sep-10 | |
| Aug-17 | |
| Aug-11 | |
| Aug-11 | |
| Aug-11 | |
| Aug-11 | |
| Aug-11 | |
| Aug-11 | |
| Aug-10 |
