Oxbridge Re Matches On A Loss As Reinsurance Revenue Shrinks And The AI GridWorks Pivot Remains Pre-Revenue
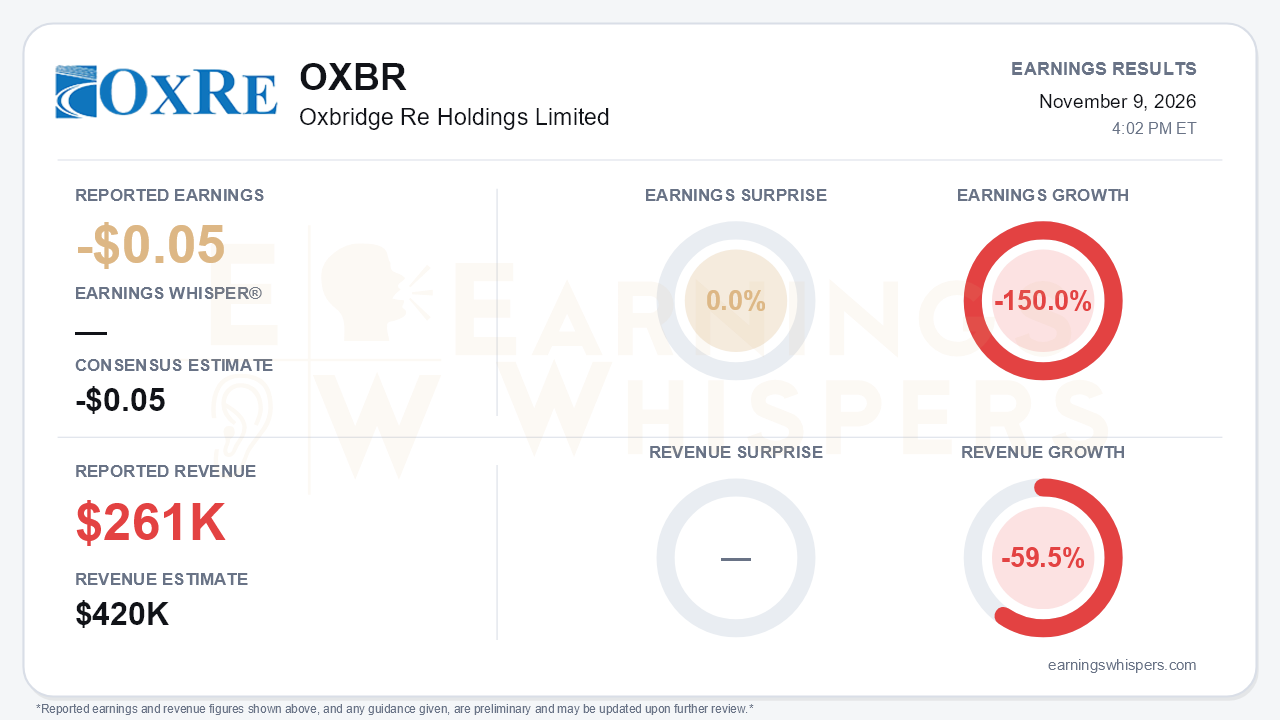
Oxbridge Re Holdings (NASDAQ: OXBR) reported a third-quarter loss of $0.05 per share, exactly in line with the consensus estimate. Revenue told a weaker story. Total revenue of $0.26 million missed the $0.42 million consensus by 37.9% and fell 59.5% from a year earlier. Earnings declined 150.0% year over year, as the net loss widened to $421,000 from $187,000. The in-line EPS print should not be read as stability. This was a quarter in which the legacy reinsurance engine visibly wound down while the company's new growth narrative, AI GridWorks, has yet to produce a dollar of revenue. That gap between a shrinking core and an unmonetized future is the central tension.
The quarter's quality deserves scrutiny because the sequential trend reversed. Oxbridge had earned $22,000 in the first quarter and $176,000 in the second. The third-quarter loss ended that modest profitability streak. Net premiums earned collapsed to $86,000 from $555,000 a year ago and from $368,000 in the second quarter, which management attributed to less capital deployed into reinsurance contracts. Assumed premiums were zero in the quarter, and SurancePlus management fee income, $501,000 year-to-date, contributed nothing in the third quarter. Two lines offered partial relief. Net investment and other income more than doubled to $175,000 from $79,000, and G&A fell to $638,000 from $754,000 on lower professional fees and compensation. With so little premium, however, the expense ratio ballooned to 752.3% from 146.8%, according to the release. The call summary cited 152.3%, but the income statement supports the release figure. The nine-month comparison looks far better: the net loss narrowed to $223,000 from $2.19 million. That improvement is almost entirely the absence of the full-limit loss that drove a 132.4% loss ratio last year, not an operating turnaround.
On the call, the emphasis shifted firmly to AI GridWorks. The tone was more measured than the launch enthusiasm of the August call. Since its debut, the unit has assembled a development team with 44 years of combined experience, begun evaluating specific sites, and engaged utilities on power availability and timing. Management is now explicitly targeting 2027 power delivery for 10-100MW 'nano' data center sites and said local officials remain supportive after the election. The strategy is deliberately optional: sell a powered site, partner, develop a powered shell for lease, or retain a finished facility. Management argues that site control, a path to power and permits create value before construction. That claim is credible in principle but unproven for Oxbridge. Management also floated geo-targeted tokenized offerings that would give county residents priority access to project financing, an attempt to marry SurancePlus's capital-raising capability with the new business.
The risks are concrete. Data center development is capital intensive, and management acknowledged in Q&A that tokenization is only a partial financing source, which raises the dilution question. That concern is already visible: shares outstanding rose to 8.18 million from 7.66 million at year-end. The balance sheet shows $19.57 million in combined cash, but only $4.14 million is unrestricted. Most of the remainder backs tokenholder obligations carried as $12.7 million of mezzanine equity, and Oxbridge shareholders' equity stands at just $6.19 million. On the reinsurance side, SurancePlus closed five 2026-27 offerings raising about $7.1 million, including three third-party HCI/Fortex Re deals. HCI said a hurricane is expected to affect Series B, though that series remained profitable as of October 21. Potential local pushback or moratoriums on data centers add another layer of execution risk.
The market has treated the pivot harshly. After the prior report, shares opened at $1.30 and spiked to $1.65 that same day on the AI GridWorks launch. They then slid to a 52-week low of $0.65 on October 27, roughly half the post-report opening price. Investor sentiment going into the August report was already decidedly negative at -0.50, and no updated reading is available to suggest a shift. The Earnings Whispers trend signals are mixed. Price and AVWAP readings remain negative, while momentum has turned positive off the lows.
The bottom line is that Oxbridge matched a low bar on earnings, but the quarter exposed how thin the operating base has become as reinsurance capital is pulled back. AI GridWorks offers a potentially larger opportunity with sensible staged optionality. For now, though, it is a 2027 power-delivery target with no revenue, significant capital needs and real dilution risk. Until site control, utility commitments or a monetization event materialize, the stock's collapse from its post-launch spike suggests investors want evidence rather than narrative.
Read our earnings preview for Oxbridge Re Holdings Limited: https://www.earningswhispers.com/article/OXBR/22658
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 8 hours | |
| Nov-09 | |
| Nov-03 | |
| Nov-02 | |
| Nov-02 | |
| Oct-27 | |
| Sep-09 | |
| Aug-31 | |
| Aug-21 | |
| Aug-13 | |
| Aug-12 | |
| Aug-12 | |
| Aug-06 | |
| Aug-04 |
