Trump Media's $1.38 Profit Is A Bitcoin Mark-To-Market Story As A $1 Billion Note Put And TAE Dilution Shape The Setup
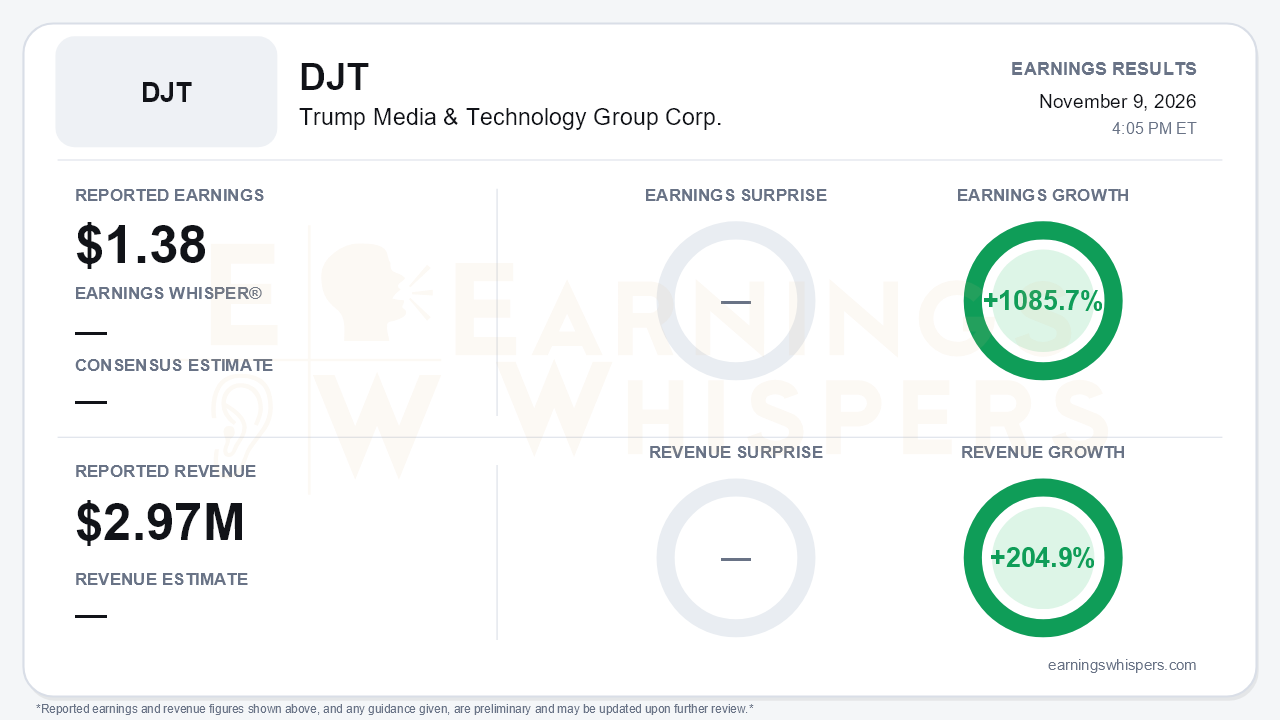
Trump Media & Technology Group reported third-quarter earnings of $1.38 per share on revenue of $2.97 million. Earnings grew 1,085.7% year over year, a swing from a $54.8 million net loss a year ago to $409.7 million of GAAP net income, and revenue grew 204.9%. No consensus estimate or Earnings Whisper was available, so there is no beat or miss to measure. That matters less than the composition of the profit. Nearly all of it came from $496.1 million of net realized and unrealized gains on digital assets and equity securities, driven by a roughly 42% Bitcoin rally from about $59,000 to $84,000 during the quarter. The operating business still lost money, with an Adjusted EBITDA loss of $12.3 million. That is the central tension: the headline profit reflects the treasury, while the operating story is improving from a very small base.
The quality of the quarter deserves scrutiny in both directions. On the positive side, the cost structure reset is real. Legal fees fell to $2.4 million from $20.3 million a year ago now that legacy litigation, including the July SPAC settlement, is resolved. Operating expenses excluding digital assets dropped to $26.5 million, down 45% sequentially and 37% year over year. The Adjusted EBITDA loss narrowed from $29.1 million in the year-ago quarter. The weaker side is that the nine-month Adjusted EBITDA loss of $83.1 million is still wider than the $72.9 million loss in the same period of 2025. Year-to-date GAAP results remain a $234.2 million loss despite the third-quarter gain. One discrepancy is worth noting. The call cited a second-quarter Adjusted EBITDA loss of $223.5 million, but that figure is hard to reconcile with the release's nine-month total. The year-over-year comparison is the cleaner yardstick.
Beneath the headline, revenue quality improved. Revenue rose 78% sequentially from about $1.7 million. Second-quarter growth had leaned on barter advertising, while third-quarter growth came from $1.8 million of subscription gains tied to Truth API, the data licensing product launched August 1, and Truth+. Higher advertising revenue and $0.2 million of Truth.Fi ETF management fees also contributed. Management had previously cited more than 10 API customer agreements at $60,000 to $100,000 per month, which suggests a recurring-revenue foundation. Still, quarterly revenue of $3 million is immaterial against $2.5 billion of total assets. Management's tone shifted from describing a "period of transition" last quarter to a more assertive emphasis on fundamentals. No formal financial guidance was offered, as was also the case last quarter.
The forward agenda is dominated by corporate events rather than operations. The SEC declared the TAE Technologies S-4 effective on November 5. A special shareholder meeting is set for December 14, and management reaffirmed a year-end close. That is a meaningful advance from last quarter, when management could not commit to timing. TAE also drew the remaining $100 million under its convertible note in October. The merger will roughly double the fully diluted share count to about 600 million, a significant dilution for current holders. The more immediate risk is the November 30 noteholder put on roughly $1 billion of convertible notes. The repayment amount is unknown, and management plans to fund it with cash and credit rather than new equity. That plan will be tested against cash of $182 million, down from $215 million last quarter.
Liquidity trends are mixed. Gross financial assets rose to $2.3 billion from $1.9 billion. Net financial assets after debt climbed to about $1.3 billion from $893 million, largely because Bitcoin holdings grew to roughly 15,649 BTC, of which 11,385 are pledged to a yield program. However, year-to-date operating cash burn widened to $28.4 million from $13.7 million at midyear, partly because yield is now received in Bitcoin rather than cash. The company made no buybacks in the quarter despite $360 million remaining on its $400 million authorization. It also discontinued its planned digital token distribution, replacing it with shareholder discounts and promotions.
Market context is thin. Shares opened at $9.37 after the prior report, and the 200-day moving average sits at $9.05. However, current price and sentiment readings were not available. The call acknowledged that the stock trades as a political-sentiment proxy and sold off sharply after the midterms. That behavior helps explain why operating improvements have struggled to drive the shares on their own.
The bottom line is that Trump Media delivered a cleaner operating quarter than its history would suggest, with subscription-led revenue growth, collapsing legal costs, and a merger timeline that is finally concrete. However, the $1.38 profit is a Bitcoin valuation outcome, not an earnings-power signal. With the $1 billion convertible put, continued cash burn, and a merger that doubles the share count all arriving within weeks, the investment setup now hinges on balance-sheet execution and the TAE vote far more than on Truth Social's growing but still tiny revenue line.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 14 hours | |
| 21 hours | |
| Nov-09 |
Trump Media & Technology Group Swings to Profit Ahead of TAE Technologies Merger
DJT
The Wall Street Journal
|
| Nov-09 | |
| Nov-06 | |
| Nov-05 | |
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 |
