LifeVantage Beats On Adjusted EPS, But Steeper Sequential Revenue Drop And No Guidance Push Its Turnaround Into 2027
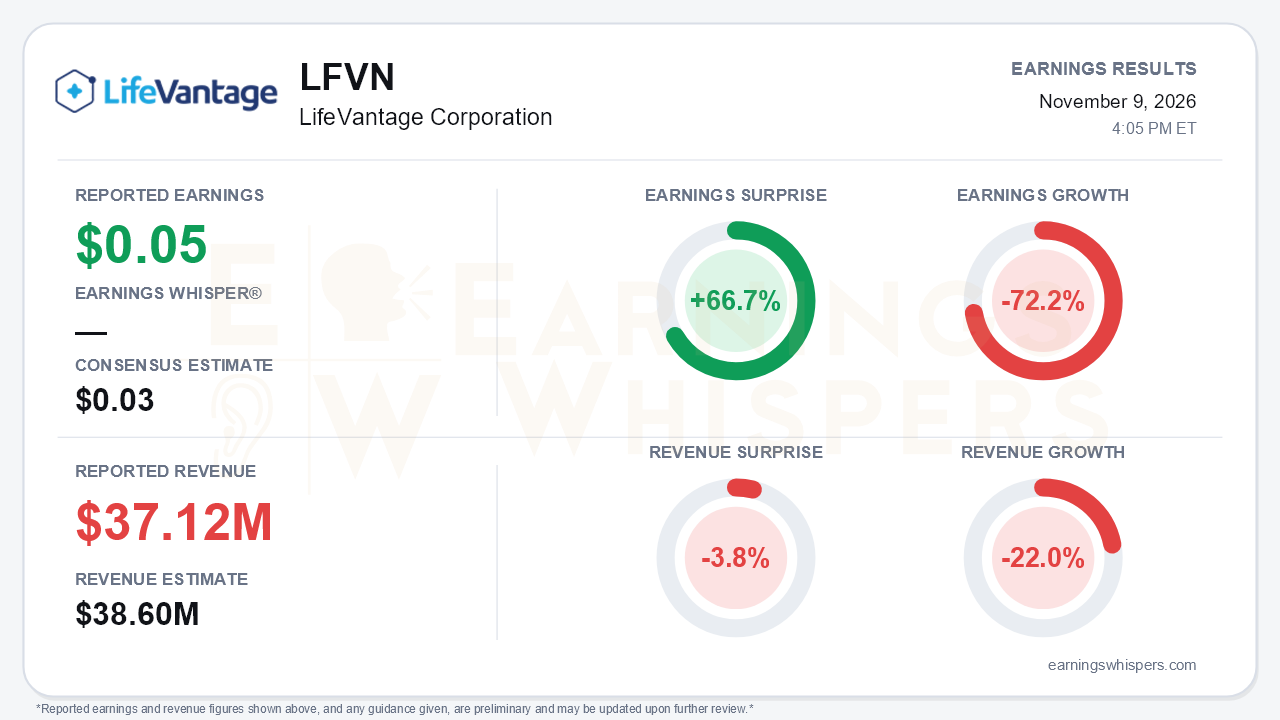
LifeVantage (NASDAQ: LFVN) cleared a low earnings bar in its fiscal first quarter, but the beat does little to change the trajectory of a shrinking business. Adjusted earnings of $0.05 per share topped the $0.03 consensus by 66.7%. Revenue of $37.12 million, however, missed the $38.6 million estimate by 3.8%. Earnings fell 72.2% year over year and revenue declined 22.0%. On a GAAP basis, the company swung to a net loss of $0.02 per share from a profit of $0.17 a year ago. The central tension is that a cost-driven bottom-line beat sits on top of a top line that is still falling, and falling faster sequentially. Management also again declined to offer a timeline for stabilization in the form of guidance.
The quality of the beat deserves scrutiny. The gap between the GAAP loss and the adjusted profit is almost entirely a $1.045 million inventory-obsolescence allowance tied to the MindBody GLP-1 System. This is not the first such charge; the call described it as another allowance, which makes the "non-recurring" treatment harder to take at face value. Excluding the charge, gross margin was 78.2%, still below the year-ago 79.5%, as shipping and warehouse costs rose. Reported gross margin was 75.4%. The real support came from commissions, which fell to 41.4% of revenue from 43.5%. SG&A dollars fell, but deleverage pushed SG&A to 34.3% of revenue, and the company posted a small GAAP operating loss of $0.1 million.
The sequential picture is weaker than the year-over-year comparison suggests. The annual decline rate has eased modestly across four quarters:
- -27.8% in fiscal Q2 2026
- -25.2% in Q3
- -23.1% in Q4
- -22% this quarter
But revenue fell roughly 12.5% from the $42.4 million reported in Q4, versus a decline of only about 3.1% the quarter before. Adjusted EBITDA has stepped down each quarter, from 7.3% of revenue in Q3 to 6.5% in Q4 and 5.2% now. Adjusted EPS has slid from $0.12 to $0.11 to $0.05 over the same period. The customer base explains why. Active accounts fell 19% to 98,000, with Americas customers down 23.7% and consultants down 16.7% overall. Management cited fewer orders, smaller order sizes, macro pressure, and MindBody GLP-1 attrition, partly offset by the LoveBiome acquisition. Improved year-over-year retention metrics are a modest positive, but they have not yet stopped account erosion.
What did change is that CEO Terrence Moorehead has moved from listening mode to a defined roadmap. The plan includes:
- repositioning LifeVantage as a "next generation nutraceutical" brand;
- a Protandim NRF2 campaign built around protection against environmental toxins;
- a new North American digital platform in Q2 of calendar 2027;
- a consultant business suite with CRM and AI tools in Q3 of calendar 2027;
- a cost reset to fund reinvestment.
The call preserved a credible strategic narrative, but it also effectively pushed the recovery window out. Last quarter, the CFO had hoped for a trend turn by fiscal Q3–Q4. The relevant milestones now sit in mid-to-late 2027, and management conceded that results "won't change overnight." The switch to a calendar fiscal year, with a six-month transition period, adds noise to comparisons in the meantime.
The balance sheet buys time but not unlimited flexibility. Operating cash flow turned positive at $0.5 million, versus $2.3 million used a year ago, helped by working-capital release. The company remains debt-free, and the call indicated the $0.05 dividend was maintained. Still, cash slipped to $13.7 million from $14.9 million, and buybacks were halted after $459K in Q4. Capex is running near $1 million per quarter for the platform rebuild while revenue contracts. Bears have legitimate ammunition here: the company is funding a multi-year rebuild from a shrinking base with no formal guidance for a second straight call.
Investor sentiment remained negative but improved slightly, moving to -0.127 from -0.168, which is not a meaningful vote of confidence. Shares closed at $5.29, down 11.8% from the $6.00 open after the August report and about 9.9% below the 200-day moving average of $5.87. The Earnings Whispers trend signals are uniformly negative, consistent with a stock the market has steadily marked down through the quarter.
The bottom line is that LifeVantage delivered an adjusted EPS beat that flatters the quarter. The underlying story is a steeper sequential revenue decline, compressing EBITDA margins, a recurring MindBody write-down, and no guidance. The new strategy is more concrete, and cash generation turned positive, but the key catalysts are now 2027 events. Until account trends stabilize, the turnaround remains a plan rather than a result.
Read our earnings preview for LifeVantage Corporation: https://www.earningswhispers.com/article/LFVN/22645
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-02 | |
| Oct-29 | |
| Oct-26 | |
| Oct-12 | |
| Sep-18 | |
| Aug-28 | |
| Aug-27 | |
| Aug-27 | |
| Aug-21 | |
| Aug-13 | |
| Aug-11 |
