Digital Turbine Beats And Raises Revenue Again, But Holds EBITDA Guidance As Margins Compress
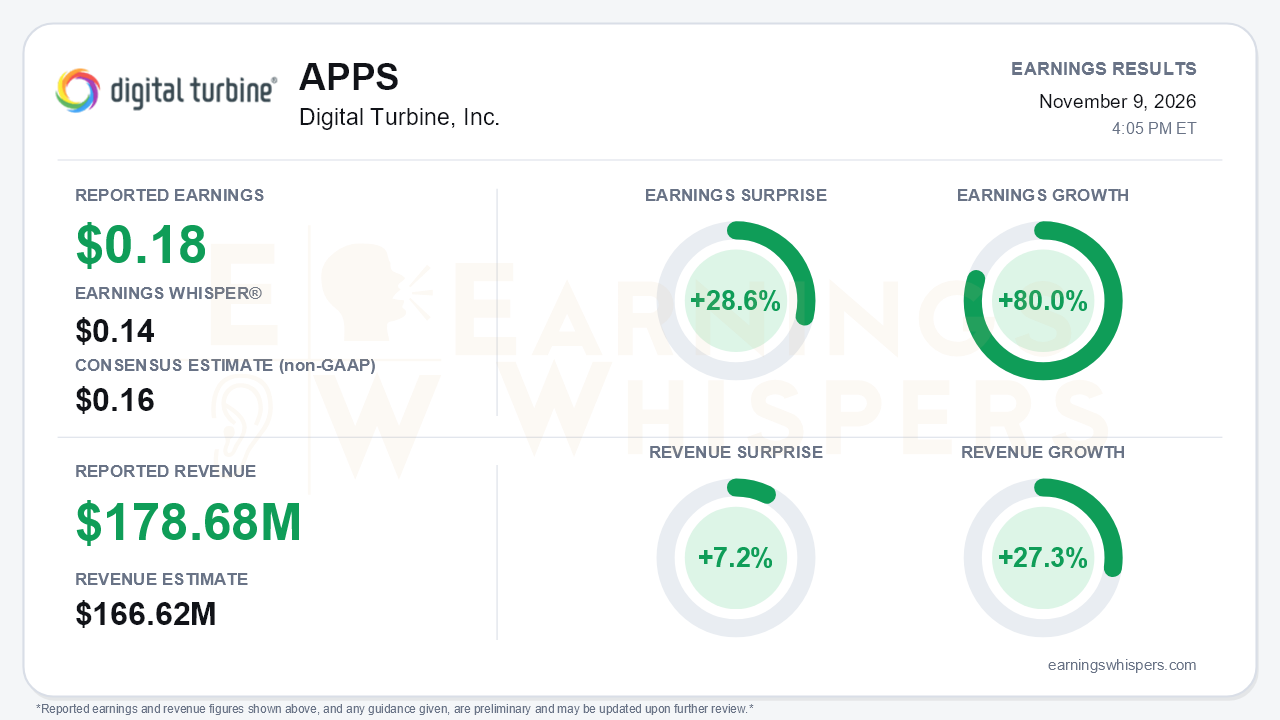
Digital Turbine (NASDAQ: APPS) delivered another clean headline beat for its fiscal second quarter. Non-GAAP earnings of $0.18 per share beat expectations by 28.6% and grew 80.0% year over year, while revenue of $178.68 million topped consensus of $166.62 million by 7.2% and rose 27.3%. Management raised fiscal 2027 revenue guidance for the second straight quarter, to $670-$690 million from $650-$670 million, a cumulative $40 million above the initial outlook. That is the bullish story. The central tension is that adjusted EBITDA guidance stayed at $145-$155 million. The company is now forecasting more revenue with no more profit, which means each incremental dollar of sales is arriving at a thinner margin.
The quality of the beat deserves scrutiny. Revenue growth held at Q1's pace rather than accelerating, and profitability moved backward sequentially. Non-GAAP EPS slipped to $0.18 from $0.19 in Q1. Adjusted EBITDA fell to $39.8 million from $42.5 million, and the margin contracted to 22.3% from 25.6%. Year-over-year EBITDA growth slowed to 46% from 69%. Non-GAAP gross margin dropped to 43%, down from 49.4% in Q1 and 47% a year ago, as revenue share climbed to 49% of net revenue from 45%. Management attributed the compression to a mix shift toward gross-revenue products.
The GAAP swing also needs context. Net income of $10.3 million, or $0.06 per diluted share, reversed a $21.4 million loss a year ago, but about $6.9 million of gains helped. Those included a $4.7 million gain on the sale of a dormant exchange inherited from AdColony and a $2.2 million unrealized derivative gain. The release also disclosed a revision to the June quarter: revenue-share expense had been understated by $3.5 million. The company called the adjustment immaterial, but it is a detail worth noting while an interim CFO transition is still under way.
Beneath the margin pressure, the operating picture shows real momentum, particularly in the legacy carrier business. On Device Solutions revenue rose 20% to $115.6 million, accelerating from 15% in Q1 and 5% in Q4 despite DRAM-related pressure on global device volumes. The App Growth Platform grew 42% to $63.5 million, but that is a clear deceleration from 56% in Q1 and 57% in Q4 as comparisons toughen. Brand growth cooled to roughly 40% from more than 70%. International ODS growth also eased to about 50% from about 80%. Management's tone was more energized. It cited five diversified growth drivers and described a turnaround in performance advertising through its own DSP since the last call, which it credited to AI and first-party data.
The catalyst list grew. Management cited:
- a new Tier 1 European operator partnership expected to launch within fiscal 2027;
- first revenue from Orange in the December quarter;
- the use of Ignite as a distribution layer for AI agents, e-commerce, and rewards;
- the Epic v. Google outcome and EU rulings, which it framed as opening alternative app-distribution channels;
- the hiring of Daniel Lenz, a former public-company CFO/COO, as CFO later in November.
The balance sheet kept repairing itself. Net leverage fell to 2.3x from 2.5x in Q1 and more than 4x a year ago. Cash rose to $51.6 million, and first-half free cash flow reached $21.8 million versus $8.4 million a year earlier. The offset is that management plans incremental data and AI spending in the second half, aimed at fiscal 2028 and beyond. That spending is the explicit reason the EBITDA range did not move, so bears have legitimate ammunition on near-term margins. One more item deserves caution: the non-gaming share of DTX spend was cited at about 40%, versus 80% on the Q1 call, which may be a definitional inconsistency.
Investors entered the report cooler than the fundamentals might suggest. Earnings Whispers sentiment slipped from essentially neutral (0.0129) to modestly negative (-0.1152). Shares at $11.30 are down 5.4% since the open after the August report, so the prior beat-and-raise did not carry the stock higher over the quarter. Even so, the stock sits 47.6% above its $7.65 200-day moving average, meaning the market has already rewarded much of the turnaround over the longer run. The trend readings are mixed. Sequential growth and momentum are positive, while AVWAP remains negative, consistent with a stock that has rerated but stalled recently.
The bottom line is that Digital Turbine preserved a credible growth story: double-digit gains in both segments, a third consecutive revenue raise, and steadily falling leverage. However, the quarter showed that growth is getting more expensive. Gross margin, EBITDA margin, and sequential EPS all moved lower, and flat profit guidance signals more of the same in the second half. Upcoming quarters will show whether the Orange and EU operator launches, plus the AI investments, can restore operating leverage. Until then, the revenue beat comes with a margin question that investors are unlikely to overlook.
Read our earnings preview for Digital Turbine, Inc.: https://www.earningswhispers.com/article/APPS/21367
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 34 min | |
| 3 hours | |
| 8 hours | |
| 8 hours | |
| 9 hours | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-05 | |
| Oct-30 | |
| Oct-26 | |
| Oct-19 | |
| Oct-16 | |
| Oct-15 | |
| Oct-07 |
