American Shared Hospital Services Must Show Growth Can Fund A Strained Balance Sheet
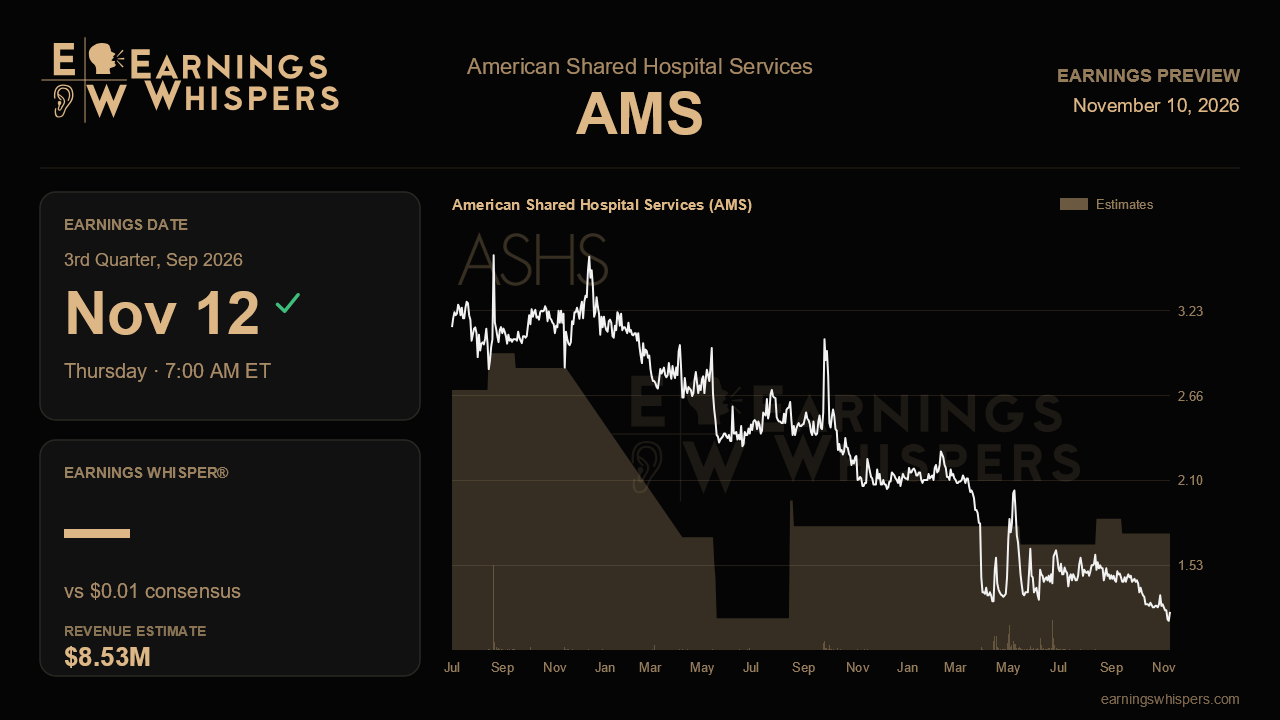
American Shared Hospital Services heads into its September-quarter report with an awkward split personality. The operating business finally started growing again last quarter, with revenue up about 19% and cash piling up. Yet the stock has lost nearly a quarter of its value since then, because the company is also operating under a bank forbearance agreement that calls for pursuing a sale of all or part of the business. The question for this report is whether the revenue recovery is strong and profitable enough to give the company leverage in whatever comes next, or whether it is simply papering over a weakening financial position.
The Street is looking for revenue of roughly $8.5 million, about 19% above the $7.2 million posted a year ago and only a hair above last quarter's $8.4 million. Consensus calls for earnings of about a penny per share, a swing from the 7 cent loss in the prior quarter. No formal guidance is on the table, so that modest profit estimate effectively rests on one assumption: that last quarter's one-time hits, chiefly a $909,000 allowance against older Rhode Island receivables and about $285,000 in legal costs, do not recur. Given that investors have already pushed back on a pattern of unwelcome surprises, a clean quarter would carry more weight than the size of the bottom line itself.
The growth story has specific moving parts worth checking. Direct patient services jumped 40% last quarter to $4.9 million, and proton beam revenue rebounded 22% after a dismal prior year, helped by the extended Orlando lease. International volumes in Peru improved after an equipment upgrade, and a new Gamma Knife partnership in Guadalajara adds another leg. Holding total revenue near $8.5 million would confirm that these gains are durable rather than a one-quarter bounce. Offsetting that, domestic Gamma Knife leasing remains under pressure from a lapsed customer contract, so any further erosion there would undercut the claim that the overall mix is improving.
Profitability is the harder test. Adjusted EBITDA slipped to about $1.3 million last quarter from roughly $1.7 million a year earlier even as revenue climbed, and gross profit dipped too. That pattern suggests the newer revenue streams carry thinner margins or higher costs. The year-ago September quarter produced about $1.9 million in adjusted EBITDA, a demanding comparison. If revenue grows near 19% while EBITDA again falls year over year, the narrative of operating improvement weakens considerably. Cash flow matters just as much: the company generated $4.4 million of operating cash in the first half and lifted cash to $6.8 million. Sustaining that build is crucial while roughly $15.5 million is owed to Fifth Third under a maturity extended to mid-2027.
Beyond the numbers, the release should clarify the strategic picture. Investors will want any update on the sale process required by the forbearance terms, how the $2 million subordinated loan from an entity formed by the Executive Chairman fits into liquidity, whether the Rhode Island radiation and proton projects are progressing toward approval, and whether the interim CEO and CFO arrangements are moving toward permanence. Silence on these points would likely be read unfavorably.
The market has already rendered a harsh verdict. At $1.22, shares trade well below their 200-day average of $1.59 and sit near the bottom of a post-earnings range of $1.14 to $1.63, a band that has shifted lower than the prior quarter's. That leaves room for relief if the quarter is tidy, but little patience for another charge. Ultimately, the report hinges on whether accelerating revenue can translate into stable EBITDA and continued cash generation. If it does, the company enters any sale discussion from a position of improving strength. If margins keep sliding, the growth story looks far less valuable to shareholders.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-10 | |
| Nov-09 | |
| Aug-13 | |
| Aug-13 | |
| Aug-06 | |
| May-22 | |
| May-14 | |
| May-14 | |
| May-12 | |
| Mar-31 | |
| Mar-31 | |
| Mar-24 | |
| Nov-13 |
