Elmet Crushes Estimates And Turns Into A Tungsten Platform, But Commodity Prices Are Doing More Of The Lifting
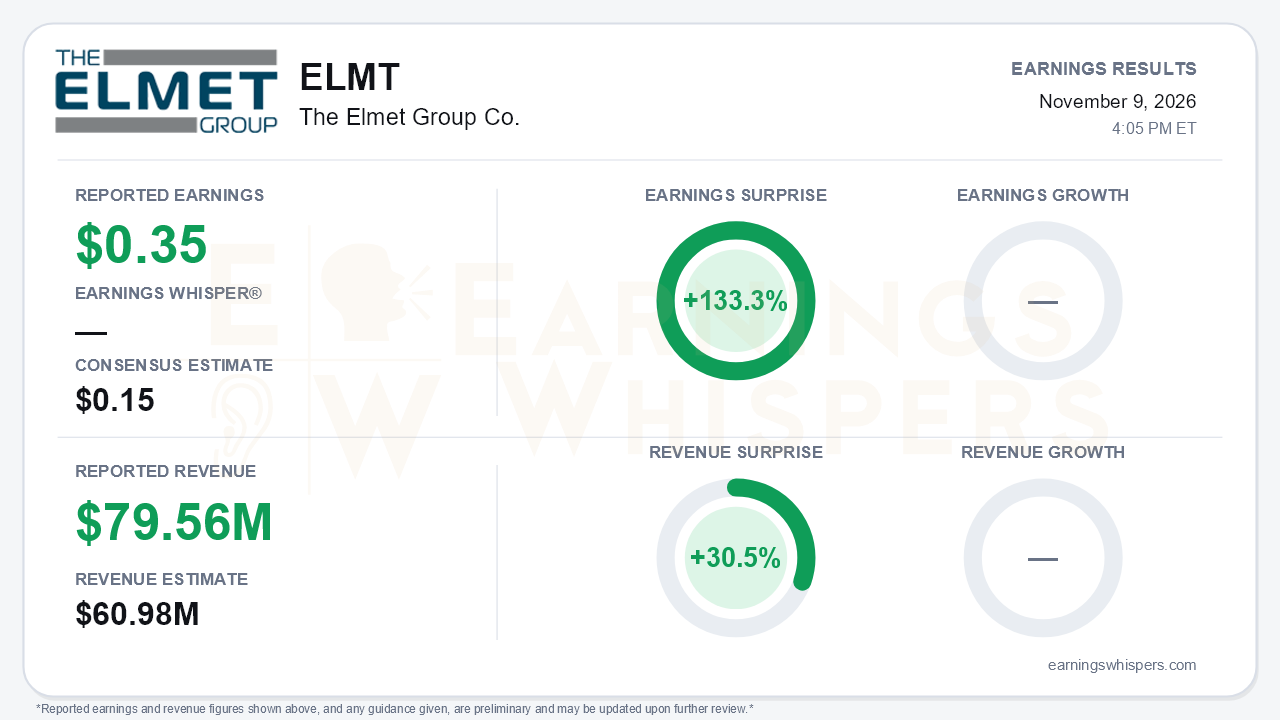
The Elmet Group (NASDAQ: ELMT) delivered a decisive beat in its third fiscal quarter. Adjusted EPS of $0.35 topped the $0.15 consensus by 133.3%. Revenue of $79.56 million beat the $60.98 million estimate by 30.5%. Growth also accelerated: revenue rose 55.6% year over year, up from 35.2% in the second quarter. Adjusted EBITDA more than doubled to $17.0 million from $8.9 million in Q2. The central tension is what drove that acceleration. Management attributed roughly 70% of Q3 revenue growth to higher tungsten and molybdenum prices, up from about 45% in Q2. Shipments excluding price grew only about 15%. This is a spectacular quarter, but a more commodity-dependent one than the headline implies.
The margin story follows the same pattern. Gross margin reached 31.3%, compared with 25.0% in Q2 and 21.7% a year earlier. That already exceeds the roughly 30% level management described last quarter as a four-to-five-year target. According to the CFO, about 600-650 basis points of the year-over-year gain came from price and 350-400 basis points from operations. The operational portion beat management's own expectations and deserves credit. Still, most of the margin expansion would be exposed to a reversal in metal prices.
GAAP results were cleaner than in recent periods. Net income was $8.3 million, or $0.24 per diluted share, versus a $4.5 million loss in Q2 and $0.08 a year ago. The adjusted figures still need context:
- Adjusted earnings excluded $2.1 million of stock-based compensation and $0.9 million of transaction costs.
- The company changed its adjusted definitions to strip out equity fair-value gains, which reduces comparability with prior periods.
- The release headline cites a 21.7% adjusted EBITDA margin, while the reconciliation table shows 21.3%.
Cash flow is the clearest weak spot. Inventory more than doubled to $152.8 million from $69.7 million at year-end. That drove nine-month operating cash outflow from continuing operations to $60.7 million, and a credit facility refinancing remains pending.
The bigger change is strategic, and here the call preserved a credible long-term growth story. The Department of War committed $450 million, with $200 million drawn, through redeemable preferred stock and warrants. The Defense Logistics Agency awarded a framework with a ceiling of up to $2 billion, of which $161.9 million is already funded and sitting in backlog. Elmet also:
- created a third division, Elmet Refining and Trading, which the CFO framed as a 'couple hundred million' revenue run-rate opportunity at current pricing;
- invested $125 million in Masan;
- signed a Tungsten West offtake for more than 1,000 metric tons a year;
- allocated about $150 million to restarting the Blue Moon Springer complex, targeted for the first half of 2029;
- earmarked $165 million to expand U.S. capacity, with that capacity expected online in the second half of 2028;
- agreed to acquire Osram's Schwabmünchen metal operations, with closing expected in Q1 2027.
Record backlog of $347.4 million, up from $131.5 million in Q2, gives real visibility. However, nearly half of the backlog increase came from the DLA award. In addition, $52.7 million of the $98.1 million CMC/EMP backlog gain was tied to material prices. Program wins in NextGen Interceptor, Patriot and Standard Missile, along with counter-drone demand from Echodyne, add genuine volume support.
Bears have legitimate ammunition, starting with execution risk. The integration plan runs to 2031 with heavy capital spending. Management expects Schwabmünchen to dilute margins and reach positive cash flow only by year three. Management also declined to guide ERT revenue for 2027 because of the Tungsten West ramp, and the company offered no formal financial guidance. DFARS-driven orders and multi-year munitions flowdown were again described as not yet evident and remain dependent on appropriations. Government warrants for up to 19.9% of the company imply meaningful dilution and add governance rights.
Investor sentiment has shifted sharply. It fell from a roughly neutral 0.04 before the report to -0.61, a substantial move into negative territory. That contrasts with price action. Shares at $21.99 are up 17.1% from the open after the August report and sit 22.8% above the 200-day moving average of $17.90. The stock has been treated well, but expectations around commodity exposure, dilution and execution appear to have soured. The AVWAP trend reading remains negative.
The bottom line is that Elmet beat estimates by a wide margin, accelerated revenue and earnings growth, and transformed itself into a government-backed, vertically integrated tungsten platform with record backlog. The quality of the beat deserves scrutiny, though. Price increasingly explains the growth, underlying volume is rising only about 15%, working capital is ballooning, and the strategic build-out stretches years into the future. Investors now own a larger, better-funded story whose near-term earnings power is closely tied to tungsten prices.
Read our earnings preview for The Elmet Group Co.: https://www.earningswhispers.com/article/ELMT/22794
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-09 | |
| Nov-03 | |
| Nov-03 | |
| Oct-23 | |
| Oct-09 | |
| Sep-30 | |
| Sep-30 | |
| Sep-29 | |
| Sep-25 | |
| Sep-24 | |
| Sep-23 | |
| Sep-23 | |
| Sep-22 | |
| Sep-22 |
