Atour Misses As Share-Based Pay Hits GAAP Profit, While Retail Lifts Guidance And The Hotel Engine Slows
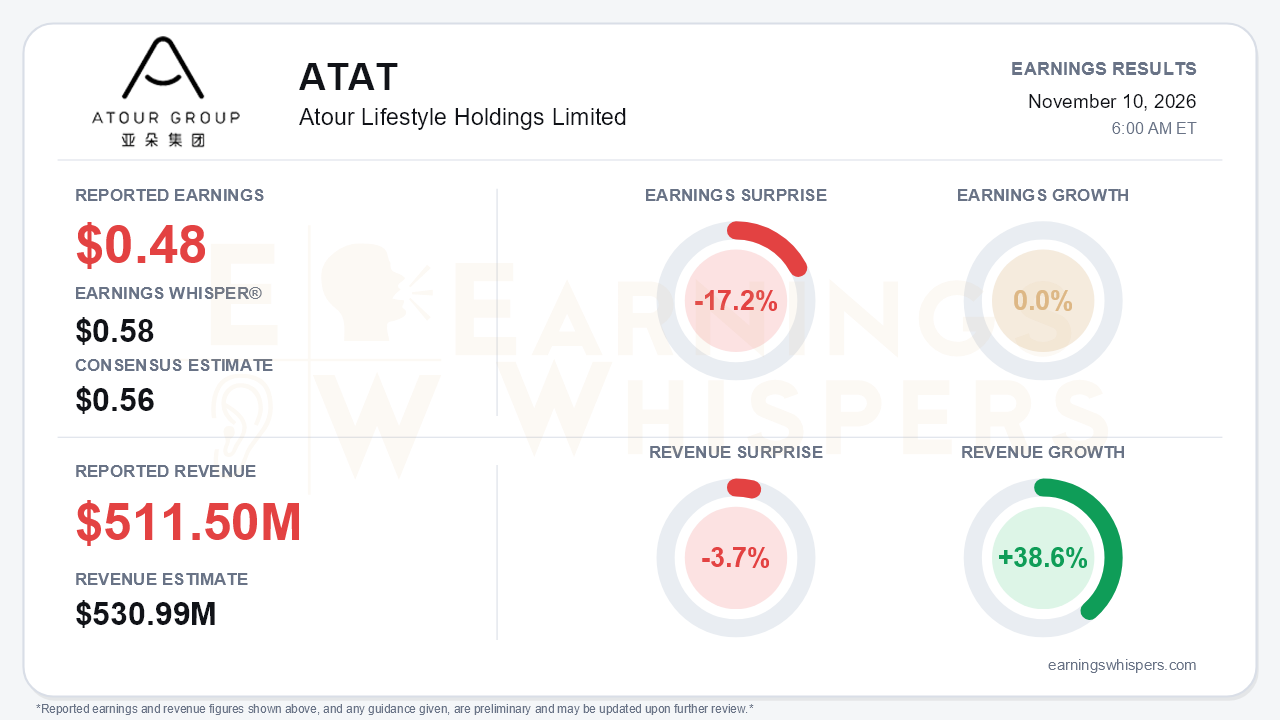
Atour Lifestyle (NASDAQ: ATAT) delivered a third-quarter report in which the guidance improved but the quarter itself did not. Earnings of $0.48 per share missed the $0.56 consensus and the $0.58 Earnings Whisper number by 17.2%, and were flat year over year. Revenue of $511.5 million missed consensus by 3.7%. Earnings Whispers puts revenue growth at 38.6% on a dollar basis, while the company reported 30.5% growth in renminbi to RMB3.43 billion. Management raised full-year revenue guidance to growth of 33% to 35%, the third straight increase. That increase is driven almost entirely by retail, while the hotel franchise that underpins the business is decelerating. That is the central tension.
The miss deserves context. GAAP net income fell 5.5% to RMB448 million, mainly because share-based compensation jumped to RMB167 million from just RMB13 million a year ago. RMB138 million of that sat in G&A. Excluding that charge, adjusted net income rose 26.2% to RMB615 million and adjusted EBITDA grew 28.8% to RMB883 million.
The add-back does not clean up everything:
- Selling and marketing rose to 15.4% of revenue from 13.5% as the company spent to build retail brands and online channels.
- Government subsidy income largely disappeared.
- Income tax expense climbed to RMB264 million, partly because the PRC-booked stock compensation is non-deductible.
- Operating income edged up only to RMB664 million from RMB651 million, despite RMB800 million of added revenue.
- Management said adjusted net margin of 17.9% was still down 0.7 points year over year, citing retail mix and organizational investment.
Retail remains the growth engine. The release shows retail revenue up 61% to RMB1.36 billion. The call analysis cites growth closer to 51%, and those figures should be reconciled. Either way, retail growth has eased from the 63% pace cited for the second quarter. Even so, management lifted full-year retail growth guidance to 50%-55%, up from 40% last quarter and 25%-30% at the start of the year. Product momentum supports that view: the Deep Sleep Pillow Pro 4.0 topped RMB100 million in sales within 17 days, and comforter revenue grew more than 70%. Retail gross margin of 52.1% improved sequentially but slipped year over year.
The hotel side is where bears have legitimate ammunition:
- **Manachised revenue growth** slowed to 20.4%, from 32.8% in the second quarter and 51.9% in the first.
- **Systemwide RevPAR** of RMB373 was essentially flat year over year.
- **Same-hotel results** for properties open more than 18 months were weaker. RevPAR fell to RMB356.6 from RMB372.2, with both occupancy and ADR lower.
- **The pipeline** shrank to 778 hotels from 811. Management acknowledged that franchisees are more cautious and quality projects are scarce.
- **No 2027 RevPAR guidance** was offered.
There are offsets. Quarterly openings accelerated to 128 from 101 in the second quarter. Management reaffirmed targets of roughly 480 openings and 80 closures. Newer brand iterations are posting higher RevPAR, and hotel gross margin improved 0.6 points to 37.9%.
Forward catalysts are tangible. They include a planned new upscale brand, a joint membership program with a retail-ecosystem partner, and a goal of taking Atour Light to 1,000 hotels. Capital returns are aggressive: a second 2026 dividend of about $69 million brings year-to-date shareholder returns above $260 million, more than 110% of 2025 net income. That generosity carries a cost. Net cash fell to roughly RMB2.5 billion from RMB3.7 billion last quarter. Rising payables and falling current deferred revenue also flatter the picture less than headline cash flow suggests.
The market setup is more complicated than the miss implies. Investor sentiment was slightly negative heading into the report and essentially unchanged from the prior quarter, so expectations were not euphoric. The stock carried more volatility than its net change shows. Shares slid to a 52-week low of $30.07 on October 28, then rebounded 18.8% to $35.73. That leaves them 4.9% above the open following the August report and just 2.1% above the 200-day moving average, near the upper part of the quarter's range. The Earnings Whispers trend readings lean positive, with sequential growth and AVWAP favorable while price and momentum are neutral. The late-October rally suggests buyers were already leaning toward the retail story. The guidance raise appears to have brought the outlook closer to existing Street estimates rather than well beyond them.
The bottom line is that Atour's quarter was weaker than its guidance. The GAAP miss was amplified by a surge in stock compensation, and adjusted profit growth remains solid. Retail strength is credible enough to justify a third guidance increase. However, same-hotel RevPAR is declining, manachised growth is decelerating, and the pipeline is shrinking. Those trends erode the asset-light hotel model that funds the dividends and buybacks. Until hotel fundamentals stabilize, Atour is increasingly a retail growth story attached to a maturing hotel chain.
Read our earnings preview for Atour Lifestyle Holdings Limited: https://www.earningswhispers.com/article/ATAT/22684
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-02 | |
| Oct-27 | |
| Aug-20 | |
| Aug-20 | |
| Aug-19 | |
| Aug-06 | |
| May-13 | |
| May-13 | |
| May-13 | |
| May-13 | |
| May-12 |
