Novanta Beats On Q3 And Bookings, But A Stockport Halt Cuts Margins And Q4 Earnings Growth To 0-5%
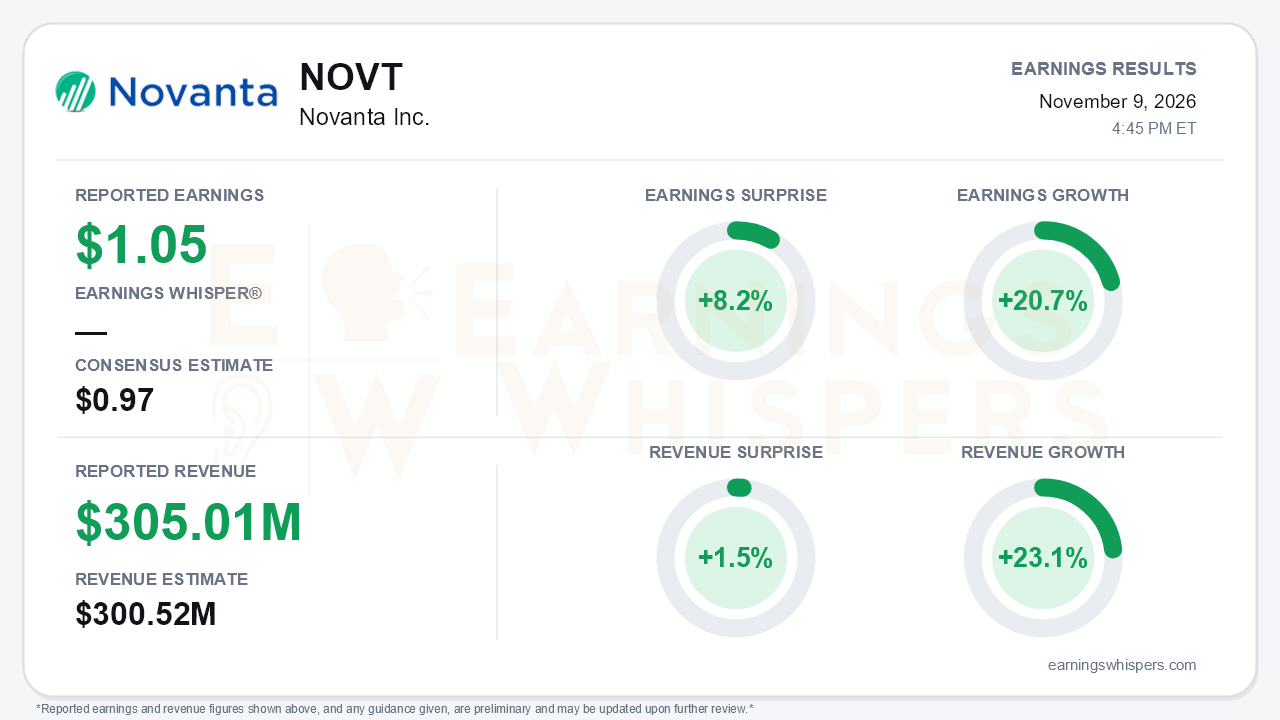
Novanta delivered a clean third-quarter beat. The trouble is the outlook that came with it. Adjusted EPS of $1.05 topped the $0.97 consensus by 8.2% and grew 20.7% year over year. Revenue of $305.01 million beat by 1.5% and rose 23.1%. Both figures also cleared management's own guidance ranges of $0.95-$1.00 and $300-$304 million. Yet the company guided below estimates, trimmed full-year EPS and gross margin targets, and pointed to a sharp slowdown in fourth-quarter earnings growth. That is the central tension: demand is strengthening while near-term margin execution is slipping.
The quality of the beat deserves scrutiny on two fronts. First, more than half of the reported revenue growth was bought. The Riverpoint Medical acquisition contributed about $33 million, or 13.3 points of growth, leaving organic growth at 9.9%. That is still a strong number, and it continues an acceleration through the year: roughly 2% in the year-ago fourth quarter, 3% in Q1, 9% in Q2 and about 10% now. Second, the GAAP picture looks very different from the adjusted one. GAAP diluted EPS fell to $0.05 from $0.30, and GAAP operating income dropped to $13.9 million from $21.8 million. The drivers were $21.4 million of intangible amortization and $19.2 million of acquisition-related costs tied to the $1.2 billion deal. Cash generation was a genuine bright spot. Operating cash flow jumped to $39.3 million from $8.5 million, and management now expects a record of roughly $200 million for the year.
Demand indicators were the strongest part of the report.
- **Bookings:** up 29% (18% excluding Riverpoint), with a 1.08 book-to-bill.
- **Backlog:** $543 million, with core backlog up 14%.
- **New products:** revenue up 23% in the quarter, and design wins up 63%.
- **Automation Enabling Technologies:** revenue grew 16%, ahead of its 12-14% guide, and GAAP gross margin widened to 50.2% from 47.3%.
The Medical Solutions segment is where the weakness sits. Organic growth there was only about 3%. Precision Medicine declined 5% after Novanta exited a lower-margin life sciences business, and management does not expect it to return to growth until late 2027. Medical adjusted gross margin slipped to 43.9% from 45.3%.
Margins are the bigger problem, and this is the second consecutive quarter of disappointment. Consolidated adjusted gross margin of 47.0% missed the roughly 48% guided on the prior call. The cause is the Stockport, U.K. facility. An end-user test finding on lithography products halted shipments until the first quarter of 2027, on top of redundant factory costs. Management expects about a 200-basis-point hit to fourth-quarter gross margin, taking it to roughly 46%. As a result:
- Full-year gross margin guidance fell to about 46.5% from the 47% held since the start of the year.
- Full-year adjusted EPS guidance was trimmed to $3.66-$3.71 from $3.68-$3.74, partly due to higher performance-based stock compensation.
- Fourth-quarter organic growth is guided to just 5-7%.
- Fourth-quarter adjusted EPS guidance of $0.91-$0.96 implies only 0-5% growth, a steep deceleration from this quarter's 20.7%.
Management's tone stayed confident, but the language shifted from "trajectory is up" to an explicit "we own that" on margins.
The call did preserve a credible growth story beyond the next quarter. Management's preliminary 2027 framework calls for more than 15% reported revenue growth, more than 20% adjusted EBITDA growth, and at least 100 basis points of gross margin improvement, with hints of upside on margin. Specific catalysts include:
- Riverpoint lifting recurring consumables to about 25% of revenue.
- A multi-indication arthroscopy fluid management system in regulatory submission, with a leading surgical OEM launch targeted for early 2027.
- Air bearing spindles sold out for two years, with doubled China capacity expected to be fully ramped by April 2027.
- A servo-drive supply partnership with a humanoid robotics developer.
Bears have legitimate ammunition, though. Net debt swung from $121 million of net cash at year-end to $689 million, leaving net leverage at 2.2x. The release also flags the need to fund a Riverpoint milestone payment. Rare-earth and electronic component supply is tightening further.
The market had already been skeptical heading into the print. Shares at $145.98 are down 13.9% since the open following the August report. They sit only 2.5% above the 200-day moving average of $142.46, leaving little technical cushion. Investor sentiment, already slightly negative, deteriorated further from -0.09 to -0.19. That is a meaningful but not dramatic shift, and it suggests expectations were fading rather than building. Price and AVWAP trend readings remain negative, while sequential growth and momentum readings are positive. That split mirrors the divide between a weakening stock and improving reported fundamentals.
The bottom line is that Novanta's third quarter validated the demand side of the story, with accelerating organic growth, strong bookings and a constructive 2027 framework, while undermining confidence in near-term margin delivery. A second straight gross margin miss, a factory-specific shipment halt and a flat-to-low-single-digit fourth-quarter EPS outlook give investors reason to discount the beat. The case now rests on whether Stockport resolves on schedule in early 2027 and whether the promised 100-plus basis points of margin expansion materializes. Until then, the stock's proximity to its 200-day average and souring sentiment reflect a market that wants proof of execution, not just strong orders.
Read our earnings preview for Novanta Inc.: https://www.earningswhispers.com/article/NOVT/22653
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 5 hours | |
| Nov-09 | |
| Nov-09 | |
| Nov-02 | |
| Oct-20 | |
| Oct-13 | |
| Aug-28 | |
| Aug-07 | |
| Aug-05 | |
| Aug-05 | |
| Jul-27 | |
| Jul-14 | |
| Jun-22 | |
| Jun-09 |
