Legend Biotech's Big EPS Beat Masks Slowing Carvykti Growth And An Effective Guide-Down For Q4 And 2027
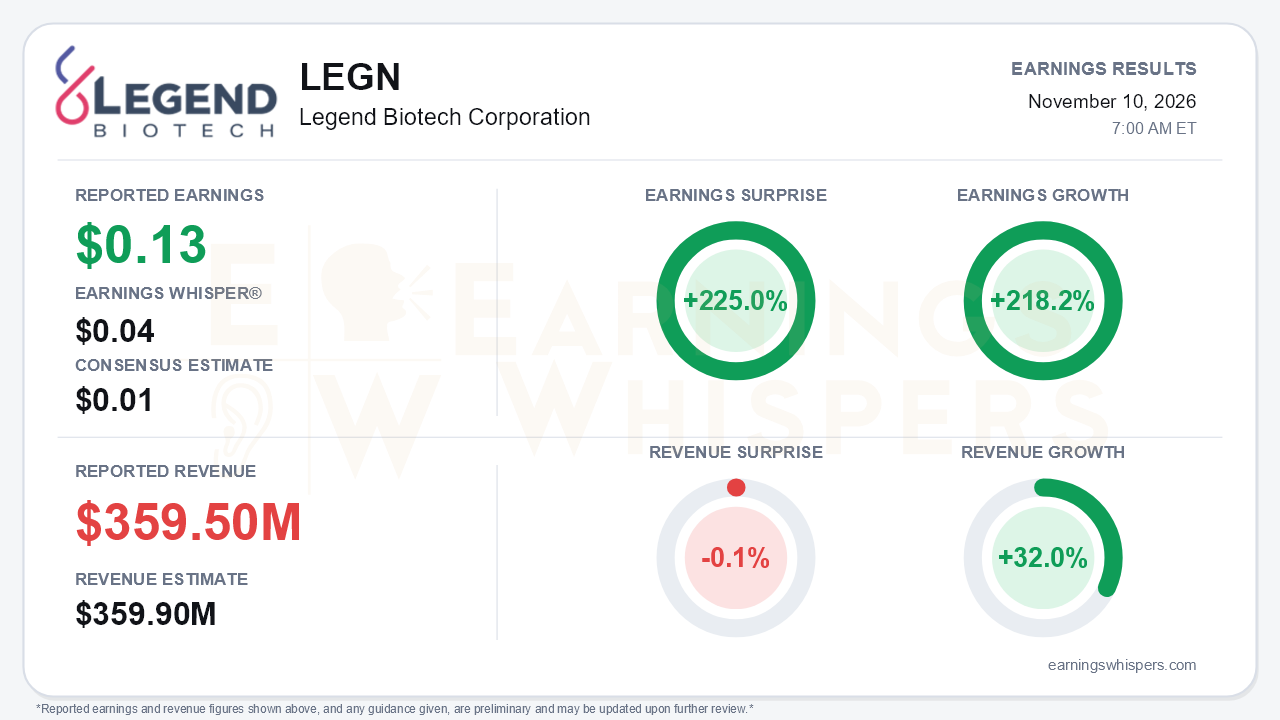
Legend Biotech posted a large earnings beat in the third quarter, but the details point to a franchise that is slowing. The company reported earnings of $0.13 per share, well above the $0.01 consensus and the $0.04 Earnings Whisper number, a 225.0% surprise. Earnings grew 218.2% year over year as Legend swung from a net loss of $39.6 million to net income of $51.7 million. Revenue of $359.5 million rose 32.0% but came in essentially in line, 0.1% below the $359.9 million consensus. The central tension is that the profit line looked strong while the CARVYKTI growth curve bent noticeably. Management then told investors that Street forecasts for Q4 and 2027 sit at the high end of its internal scenarios.
The quality of the beat deserves scrutiny. Administrative expenses fell to $14.8 million from $34.7 million, mainly because forfeited unvested equity awards triggered a reversal of previously recognized share-based compensation. Share-based compensation was a net $9.6 million credit in the non-IFRS reconciliation, compared with a $15.0 million expense a year ago. On the call, management put the credit at about $24 million. Excluding it, underlying operating margin was about 6%, down from 15% in the second quarter. R&D also fell $17.9 million as cilta-cel trial dosing wound down, which helps profitability but is not a revenue driver. Adjusted net income of $55.6 million, or $0.14 per share, was a sharp reversal from last year's $18.7 million adjusted loss, but it declined sequentially from roughly $63 million in Q2. Operating cash flow was negative $35.9 million for the quarter. Cash and time deposits fell to $853 million from about $965 million as Legend paid down J&J advanced funding, which dropped to $44.1 million from $319.1 million at year-end.
The deceleration is what changed the story. CARVYKTI net trade sales reached about $710 million, up 36% year over year. Growth has slowed every quarter, from 66% in Q4'25 to 62%, 50% and now 36%. The U.S. was the weak spot: sales grew 19%, down from 32% in Q2 and 36% in Q1, and were flat sequentially. Ex-U.S. growth stayed strong at 86% but slowed from 128%. Management's commitments have narrowed along the way. In Q1 it promised sequential growth in both the U.S. and international markets. Q2 trimmed that to global growth only, and this call offered no U.S. commitment. The CFO cited slower U.S. earlier-line share gains and ex-U.S. launch delays, while still expecting double-digit growth in 2027.
There is a credible bull narrative, and it rests on margins and positioning. Gross margin on net product sales reached 58%, against guidance for the lower-50% range. Fourth-quarter guidance was raised to the high-50% range on manufacturing efficiencies, and full-year adjusted profitability was reaffirmed. Earlier-line use keeps rising: second- and third-line patients made up 50% of U.S. apheresis in Q3, versus 41% in Q1'26 and 29% a year earlier. September's NCCN update recommends referral to a CAR-T capable center at first relapse and prefers CAR-T over T-cell engagers when both are viable. CARTITUDE-2 Cohort A five-year data showed half of patients alive and progression-free without further treatment. The pipeline also advanced. The LB2501 in vivo CAR-T IND was cleared ahead of schedule, and its ASH abstract showed complete responses in all eight patients at dose level 2 with no dose-limiting toxicities. Bears have legitimate ammunition, however:
- bispecifics such as Tecvayli and Talvey are gaining ground in earlier lines;
- competing BCMA CAR-T anito-cel data are coming at ASH;
- the CARTITUDE-5 readout slipped to 2027 at the soonest;
- the in vivo BCMA program remains gated by J&J collaboration terms.
The market setup is more complicated than the surprise implies. Investor sentiment improved meaningfully into the report, moving from -0.30 to +0.08, a shift from skepticism to modest optimism. Shares were $24.29 in the latest pre-report snapshot, up 11.6% from the open after the August report. That price is about 9.6% above the 200-day moving average and within 0.5% of the inter-earnings high of $24.42, set the day before results. The stock had rallied 44% from its September 16 low. Momentum and AVWAP trend readings were positive heading in. In short, the stock entered the print near the top of its range, with expectations rebuilding just as management signaled consensus is too optimistic.
The bottom line is that Legend delivered a headline profit beat and real progress on margins, earlier-line adoption and the in vivo pipeline. But the earnings surprise leaned on a one-time compensation reversal. The more durable signals are a fourth straight quarter of slower CARVYKTI growth, flat U.S. sales and a soft guide-down for Q4 and 2027. With shares running near their inter-earnings high and sentiment newly positive, investors will need evidence that NCCN-driven earlier-line demand can re-accelerate U.S. sales before the beat translates into a stronger growth story.
Read our earnings preview for Legend Biotech Corporation: https://www.earningswhispers.com/article/LEGN/22700
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 8 hours | |
| 10 hours | |
| Nov-04 | |
| Nov-03 | |
| Nov-03 | |
| Oct-27 | |
| Oct-15 | |
| Oct-01 | |
| Sep-25 | |
| Sep-15 | |
| Sep-15 | |
| Sep-15 | |
| Sep-10 | |
| Sep-01 |
