Harvard Bioscience Beats On The Top Line, But An EBITDA Guidance Cut Shows Growth Is Getting More Expensive
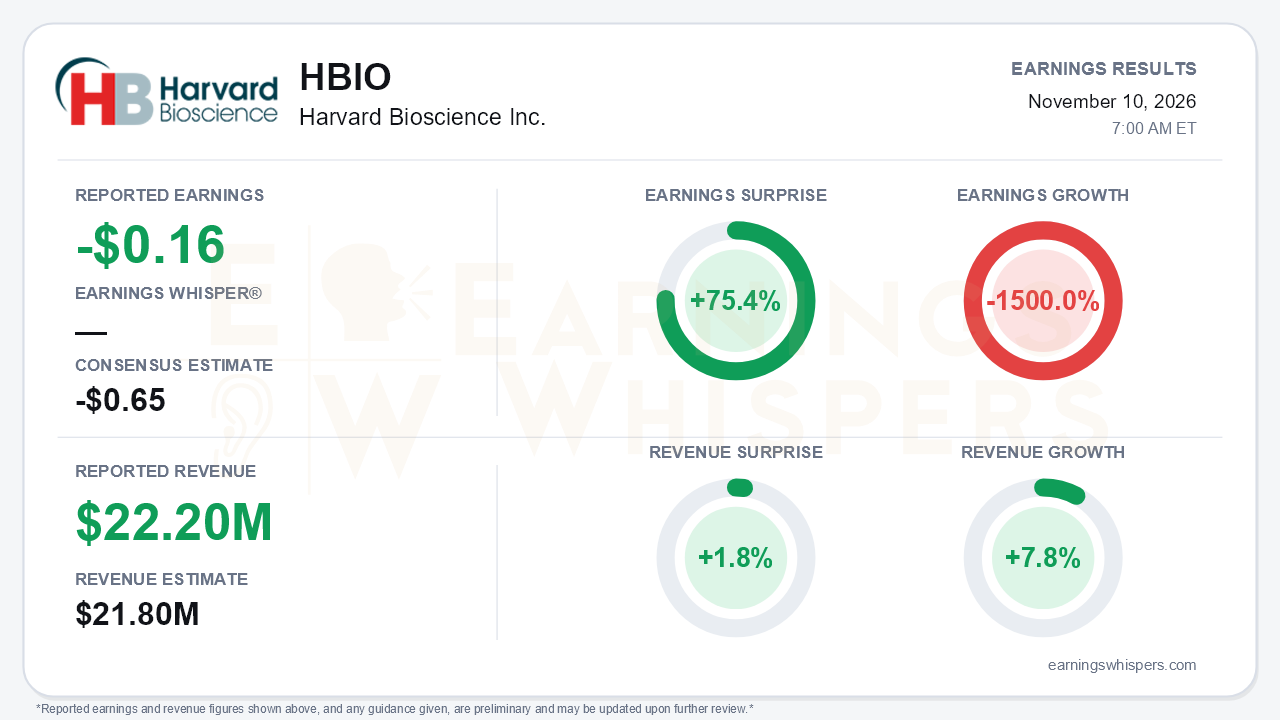
Harvard Bioscience (NASDAQ: HBIO) reported a narrower-than-expected third-quarter loss of $0.16 per share. That beat the consensus estimate of a $0.65 loss by 75.4%, though by Earnings Whispers' measure earnings fell 1500.0% from a year ago. Revenue rose 7.8% to $22.2 million, 1.8% above the $21.8 million consensus and toward the upper end of management's $21.0-$22.6 million guide. The beat is real, but it is not the main story. Management cut full-year adjusted EBITDA growth guidance to a range of -1% to +4%, down from the 6%-10% it had held since the fourth-quarter 2025 call. The central tension is that the company is selling more but keeping less of each dollar.
The quality of the quarter deserves scrutiny. On its own reporting, the company posted a GAAP loss of $0.58 per share and an adjusted loss of $0.06. Both differ from the normalized $0.16 figure, so investors should be clear about which basis they are comparing. Either way, the trend is unflattering:
- **Net loss:** widened to $2.6 million from $1.2 million.
- **GAAP operating result:** swung to a $1.15 million loss from a small profit.
- **Gross margin:** fell to 55.4% from 58.4%. Adjusted gross margin slipped to 57.1% from 59.2%, at the low end of the 56%-58% range.
- **Adjusted EBITDA:** declined to $1.8 million from $2.0 million despite higher sales, as the margin compressed to 7.9% from 9.6%.
- **Operating expenses:** sales and marketing rose 17%, and restored compensation added roughly $0.8 million. Restructuring charges tied to Project Viking also climbed.
- **Interest expense:** rose to $1.8 million from $1.3 million, eating further into results.
Revenue momentum and margin momentum are moving in opposite directions. Growth hit 8% after 11% in the second quarter, following a first-quarter decline. The Q4 revenue guide of $23.7-$25.5 million implies roughly 4% growth at the midpoint, a further deceleration even as the full-year 3%-5% target was reaffirmed.
The growth engines are clearly identifiable:
- **China:** revenue jumped 31%, building on 29% in the second quarter and just 3% in the first. All three localized BTX product lines are now shipping there.
- **APAC:** revenue rose 29%.
- **Americas:** revenue grew 9% on CRO strength. Fisher Scientific North America sales have more than doubled year to date.
The problem is that these channels carry thinner margins. Management explicitly blamed the EBITDA cut on stronger-than-expected sales of lower-margin CMT products and a heavier mix of distribution and China revenue. Meanwhile, the weaker spots are higher-quality business:
- Europe fell 5% (3% in constant currency) on soft academic demand.
- The academic recovery management flagged earlier in the year has not materialized.
- Telemetry growth cooled to mid-single digits from double digits.
- Recurring revenue edged down to about 54% of sales.
The forward case rests heavily on execution. Project Viking, the company's manufacturing consolidation, has moved five of eight lines and is slated to finish by the end of the first quarter of 2027. Management expects $3 million of savings in 2027 and roughly $4 million annually, and is now targeting about 60% gross margin next year. A GMP bioproduction version of BTX is expected to fully launch by mid-2027. A planned asset-based revolver to refinance the $10 million term loan A should reduce interest costs and the exit fee.
The fourth-quarter guide is demanding. It calls for adjusted gross margin of 59%-61% and adjusted EBITDA of $3.8-$4.2 million, nearly matching the $4.2 million generated in the first nine months combined. Bears have legitimate ammunition on the balance sheet:
- Cash fell to $4.9 million.
- Net debt rose to $35.1 million.
- Stockholders' equity shrank to $5.1 million.
- Nine-month operating cash flow was negative $0.6 million, versus positive $6.8 million a year earlier, as inventory built.
The market setup is more complicated than the surprise implies. Shares closed at $9.09 before the report, up 42.0% from the $6.40 open following the August release. They sat within 2.5% of a 52-week high of $9.32 set the day before earnings and roughly 61% above the 200-day moving average. The stock entered the print near the top of its inter-earnings range, having already priced in much of the revenue recovery. Supporting momentum and AVWAP trend readings are positive. Investor sentiment, however, was essentially neutral to slightly negative at -0.06, suggesting the rally was not built on euphoric expectations. That cuts both ways: there is less crowded optimism to unwind, but also no strong conviction cushion if the margin story disappoints.
The bottom line is that Harvard Bioscience delivered a credible top-line quarter and a comfortable beat, but the guidance cut changes the character of the recovery. Revenue is growing in lower-margin channels, growth is set to slow in the fourth quarter, and liquidity is tight relative to the debt load. After a 42% run to 52-week highs, the investment case now depends less on demand and more on whether Project Viking and the refinancing can deliver the margin rebound management is promising for 2027.
Read our earnings preview for Harvard Bioscience Inc.: https://www.earningswhispers.com/article/HBIO/22849
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-06 | |
| Aug-11 | |
| Aug-11 | |
| Aug-11 | |
| Aug-11 | |
| Jul-28 | |
| May-20 | |
| May-12 | |
| May-12 |
