TTEC Beats On Margins And Cash, But Shrinking Revenue And A Heavy Debt Load Keep The Stock Under Pressure
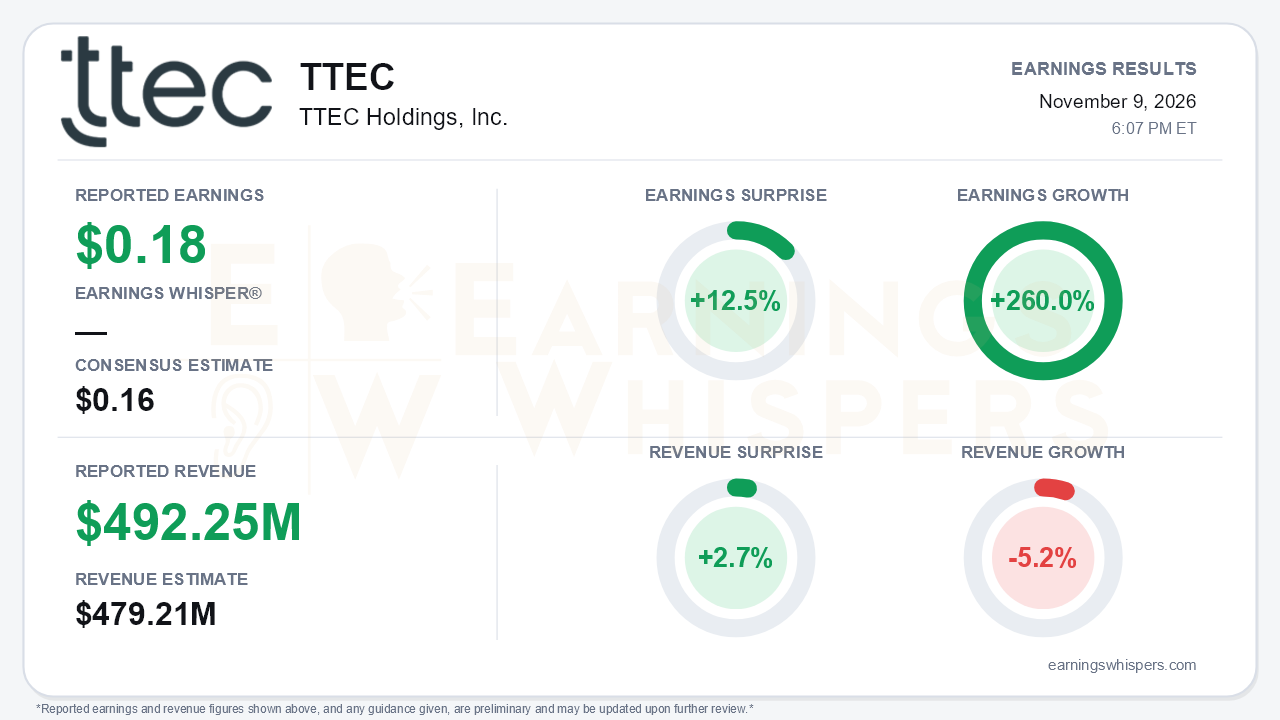
TTEC Holdings delivered the clean execution quarter it needed after a difficult second quarter. Earnings Whispers puts third-quarter earnings at $0.18 per share, ahead of the $0.16 consensus by 12.5% and up 260.0% from a year ago. Revenue of $492.25 million beat the $479.21 million consensus by 2.7% but still fell 5.2% year over year. That is the central tension. Profitability, cash generation and leverage all improved sharply, yet the top line is still contracting. Investors have so far refused to give the turnaround credit, sending the stock down roughly 30% since the last report.
The quality of the beat holds up better than the headline figure alone suggests, though the per-share numbers need careful reading. The company's own non-GAAP EPS was $0.22, versus $0.12 a year ago and $0.03 in the second quarter. That figure excludes $2.5 million of expenses tied to an alternative capital structure, along with restructuring, stock compensation and intangible amortization. On a GAAP basis, TTEC still lost $0.06 per diluted share, or $0.10 attributable to stockholders, though that was a much smaller loss than the $0.23 a year earlier. The operating gains are real. GAAP operating margin roughly doubled to 4.7% from 2.4%, and adjusted EBITDA rose to $51.5 million, a 10.5% margin, from 8.4% a year ago and 8.7% in the second quarter. Free cash flow swung to a positive $27.9 million from negative $9.6 million. A punishing 140.7% effective tax rate, which reflects the U.S. valuation allowance, continues to keep GAAP results in the red.
Beneath the headline, the margin story belongs mainly to Engage. Engage's non-GAAP operating margin jumped to 6.7% from 3.8% in the second quarter, driven by right-shoring, pruning of underperforming programs and cost control. Nearshore and offshore delivery reached 42% of revenue year to date, up from 36% in 2025. Engage revenue still fell 6.8%, but that was a clear improvement from the 12.1% decline in the second quarter. Management also reversed its earlier warning that new deals "start smaller," saying average new-logo deal size is up 56% year to date. Digital revenue was flat at $122.1 million after an 8.5% decline last quarter. Within Digital, the high-growth practices expanded 28%, backlog coverage climbed to 99% of guidance from 76% in the first quarter, and hyperscaler-related work now makes up 73% of the pipeline. Management's tone shifted noticeably, from a quarter that "fell short" to "this quarter we delivered."
The forward picture is steadier but not stronger. TTEC reaffirmed full-year guidance of $1.94 billion to $1.99 billion in revenue and $0.79 to $0.99 in non-GAAP EPS. With $0.40 of non-GAAP EPS booked through nine months, that outlook depends on a meaningful fourth-quarter step-up. Management also steered Engage profitability toward the low-to-middle end of its range, a soft trim that follows the second-quarter cut. Engage backlog coverage of 99% trails last year's 102%, and trailing-twelve-month retention eased to 92% from 93%. On the positive side, the credit facility now runs to November 2028, removing a near-term refinancing overhang. The Digital strategic-alternatives process with PJT Partners is reportedly drawing high interest and could be the most consequential catalyst for the balance sheet. Still, net debt of $743.6 million and 3.63x leverage remain heavy. Emerging AI-disclosure rules, including California's law taking effect January 1, also add uncertainty to client automation programs.
The market setup is more complicated than the surprise implies. Shares sat at $1.40 heading into the report, down 29.5% from the $1.98 open after the August release and 36.5% below the $2.20 200-day moving average. Investor sentiment remains negative but improved modestly, rising to -0.25 from -0.29. That suggests expectations were low rather than newly hopeful. The Earnings Whispers trend readings lean negative, with momentum and AVWAP still deteriorating even as price trend and sequential growth have stabilized to neutral.
The gap between operating progress and equity performance comes down to the capital structure. Each dollar of free cash flow is going toward debt reduction rather than shareholder returns. Net debt has fallen from $825 million at year-end, but at the current share price, equity remains a thin layer on top of that debt. Bears have legitimate ammunition in the declining revenue, softening Engage retention and the elevated tax drag. Bulls can now point to two consecutive quarters of moderating revenue declines, a materially stronger margin base and an asset-sale option.
The bottom line is that TTEC delivered a convincing margin-and-cash quarter and removed its most immediate financing risk, but it has not yet shown that revenue can stop shrinking. Until Engage revenue stabilizes, or the Digital review produces a deleveraging transaction, the stock will likely continue to trade on balance-sheet risk rather than on improving execution.
Read our earnings preview for TTEC Holdings, Inc.: https://www.earningswhispers.com/article/TTEC/22847
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 4 hours | |
| Nov-09 | |
| Nov-09 | |
| Nov-04 | |
| Nov-03 | |
| Oct-20 | |
| Oct-06 | |
| Sep-28 | |
| Sep-24 | |
| Sep-22 | |
| Sep-22 | |
| Aug-24 | |
| Aug-17 | |
| Aug-13 |
