Gladstone Investment Misses As Core Income Slips Below Its Payout, While Record Deployment And The SFEG Exit Shift The Story To Gains And Growth
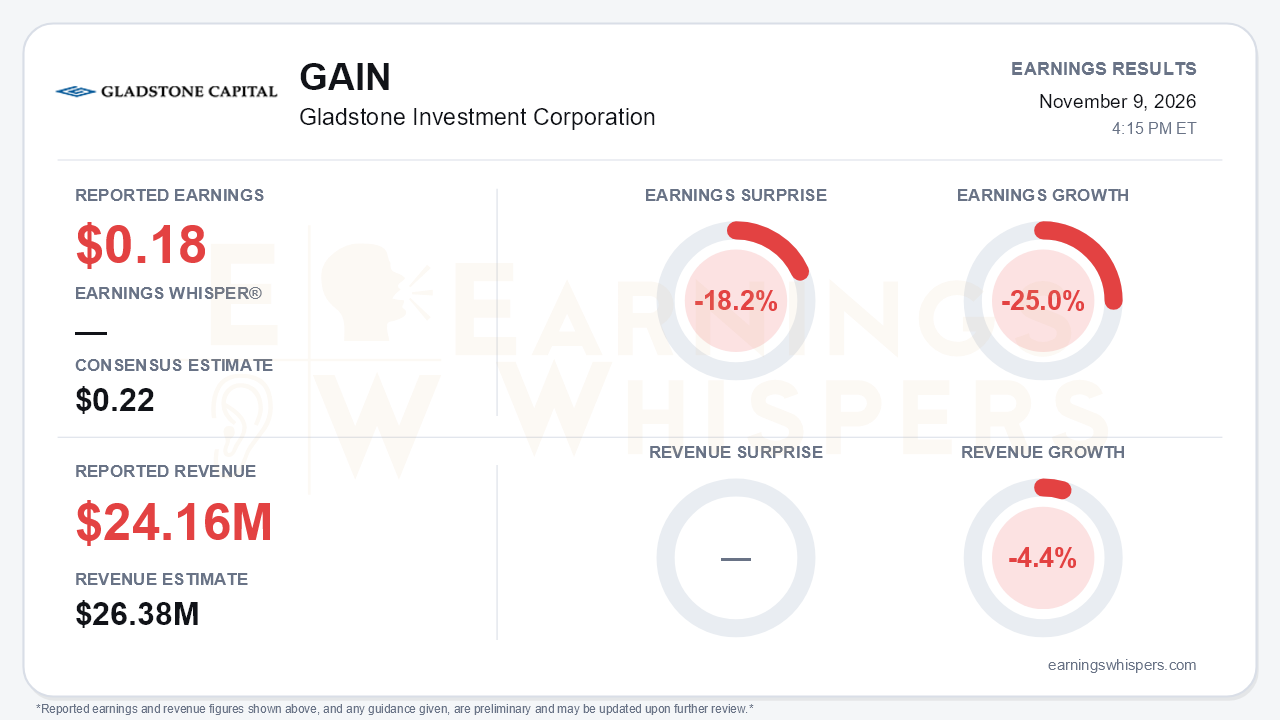
Gladstone Investment (NASDAQ: GAIN) delivered a clear miss on the income line in its fiscal second quarter. Adjusted net investment income was $0.18 per share against a $0.22 consensus, an 18.2% shortfall, and earnings fell 25.0% year over year. Total investment income of $24.16 million missed the $26.38 million consensus by 8.4% and declined 4.4% from a year ago. The central tension is that the business is expanding faster than at almost any point in its history while the earnings that fund the regular distribution are moving the other way. Adjusted NII has now gone from $0.21 to $0.20 to $0.26 to $0.18 over the last four quarters. Excluding the success-fee-boosted June quarter, the trend has drifted lower, and the latest print sits well below the $0.24 quarterly regular payout.
The quality of the quarter deserves careful reading because GAAP and adjusted figures diverge sharply. GAAP NII collapsed to $0.12 from $0.40. That move was distorted in both directions by capital-gains incentive fee accounting: the company accrued $2.4 million this quarter after reversing $5.6 million in the June quarter, and the swing pushed net expenses up 55% to $19.3 million. Those accruals are not contractually due, so the adjusted measure is the better gauge of core earnings. Even that measure weakened for two reasons. Success fee income fell by $5.6 million, which management notes is lumpy, and interest expense rose $1.0 million on heavier credit-facility borrowing. A $1.4 million gain in interest income only partly offset those pressures. Below the income line the picture was healthier. Net unrealized appreciation of $12.2 million, compared with $18.8 million of depreciation last quarter, lifted NAV per share to $16.43 from $16.24.
The call made clear that the operating story is about deployment, not near-term income. GAAP NII fell 70% while the business itself was growing quickly. GAAP invested $156.5 million in the quarter, including new platforms DHE and Extrude Hone and add-ons at Global GRAB and Detroit Defense. Year-to-date investment reached roughly $206 million through eight months, ahead of a $183 million three-year annual average, and management characterized the year as on track for a record. Interest-bearing principal rose to $734 million from $706 million, and the weighted yield edged up to 13.0%. Extrude Hone closed on September 30, so its contribution begins next quarter. McFarlane Toys, a $56.1 million investment, was added in November, and management teased another potentially large deal. Credit improved as well: non-accruals fell to 0.5% of fair value from 1.0%, and two of those positions are expected to be exited.
The largest catalyst is the SFEG exit. Management described it as GAIN's biggest ever, at an enterprise value above $400 million. The $54.6 million debt position was repaid at par in October. Roughly 85% of the $167 million equity fair value is expected over the coming months, and management signaled a supplemental distribution, with the amount not yet determined. That is the counterweight to the coverage problem. Realized gains, rather than recurring income, are likely to drive shareholder returns in the near term. There are caveats. About $25 million of the SFEG value sits in escrow with uncertain timing. Spillover income slipped to $0.50 per share from $0.56. Leverage also stepped up meaningfully: asset coverage fell to 189% from 209%, and debt-to-equity rose to roughly 1.1x from 0.88x. Adjusted credit-facility availability stood at just $80.4 million before the SFEG proceeds arrived. Management also flagged energy costs, inflation, defense-funding policy and a competitive M&A market as watch items.
Investors had already been cooling on the name. Earnings Whispers sentiment remained positive but weakened, slipping to 0.40 from 0.51. Shares at $15.09 are down 8.3% since the open after the August report and sit about 1.8% below the 200-day moving average of $15.37. The stock also trades below the newly reported $16.43 NAV, which suggests the market is discounting the earnings shortfall more than it is rewarding book-value gains. The Earnings Whispers price and AVWAP trend readings are negative, while momentum remains positive. That mix fits a stock caught between a weakening income print and an improving pipeline.
The bottom line is that GAIN's quarter was weak on the metric most income investors watch and strong on nearly everything that should matter over the next few quarters. Bears have legitimate ammunition: adjusted NII missed, fell short of the distribution for a second time in three quarters, and leverage rose to fund the growth. The bull case rests on execution. Proceeds from SFEG need to arrive largely as expected, and record deployment, including Extrude Hone and McFarlane Toys, needs to lift interest income enough to restore coverage. Until adjusted NII climbs back toward $0.24, the stock's discount to NAV is likely to reflect skepticism about the durability of the payout rather than doubts about portfolio value.
Read our earnings preview for Gladstone Investment Corporation: https://www.earningswhispers.com/article/GAIN/22628
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-09 | |
| Nov-09 | |
| Nov-06 | |
| Nov-05 | |
| Nov-02 | |
| Oct-30 | |
| Oct-28 | |
| Oct-13 | |
| Sep-30 | |
| Sep-28 | |
| Sep-21 | |
| Sep-16 | |
| Sep-10 | |
| Aug-07 |
