Ambiq Micro's Growth Accelerates To 110% And Q4 Guide Jumps, But Rising Spending Keeps Breakeven Out Of Reach
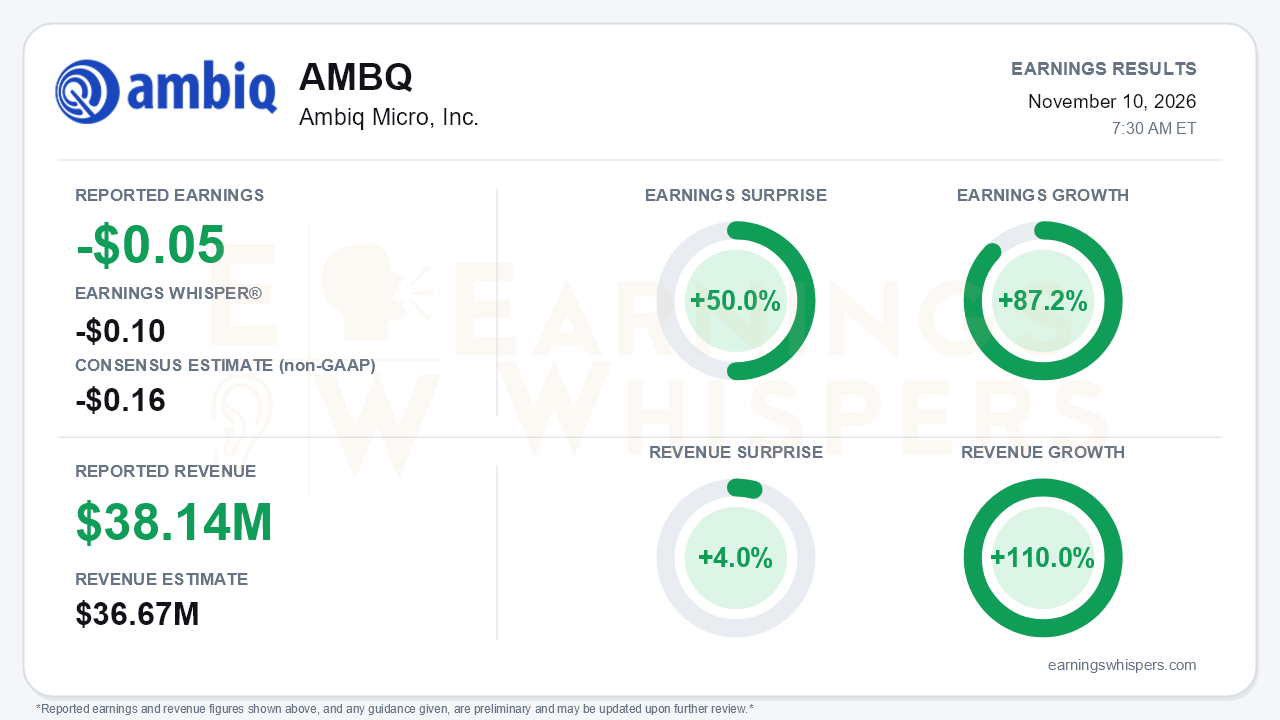
Ambiq Micro delivered a clean beat and a guidance raise. The company reported a non-GAAP loss of $0.05 per share against a consensus estimate of -$0.16 and an Earnings Whisper number of -$0.10, a 50.0% surprise. Revenue of $38.14 million topped the $36.67 million consensus by 4.0% and grew 110.0% year over year. Earnings improved 87.2% from a year ago. More important than the beat is the trajectory. Revenue growth has accelerated from 59.3% in the first quarter to 89.7% in the second and now 110%. Management also guided fourth-quarter sales to $43.5 million to $44.5 million, roughly $6 million above the level implied in August. That makes Q4 the seventh straight sequential gain, in a quarter the company had expected earlier in the year to be seasonally soft. The central tension is that the top line keeps outrunning expectations while the path to profitability does not get much shorter.
The quality of the quarter is better than many small-cap beats. Non-GAAP gross margin reached 48.7%, above the 46.5% to 47.5% guide and up from 47.2% in Q2, 46.2% in Q1 and 45.5% a year ago. GAAP gross margin expanded 440 basis points to 46.7%. Growth was also broadening. Seven customers each generated more than $1 million in quarterly sales, versus three a year ago. The active customer base grew about 50%, and sales outside major customers rose more than 270%. The non-GAAP net loss narrowed to $1.2 million from $1.8 million in Q2 and $5.0 million in Q1. On a GAAP basis, however, the net loss of $7.1 million was essentially unchanged from Q2. GAAP operating loss of $10.0 million was flat with a year ago, as stock-based compensation nearly doubled to $4.0 million and total operating expenses rose 57%.
Spending is the clearest constraint. Non-GAAP operating expense climbed 72.9% year over year to $22.8 million, with non-GAAP R&D up about 90%. The Q4 outlook calls for $25.5 million to $26.5 million, reflecting tape-out costs for Atomiq110 and Apollo340. The fourth-quarter non-GAAP loss guide of $0.09 to $0.03 per share brackets the Q3 result. Even with sales stepping up roughly 15% sequentially, the loss is not guaranteed to keep narrowing. Management has not guided 2027 operating expenses, so the breakeven timeline remains vague. Working capital is also absorbing cash. Inventories rose to $30.1 million from $16.9 million at year-end and receivables more than doubled, pushing nine-month operating cash burn to $25.4 million from $15.6 million. The $363 million cash balance, built largely on a $245 million follow-on, makes this a matter of efficiency rather than solvency.
The call added genuinely new catalysts:
- A customer deployed the first Ambiq-developed AI model, for a voice use case, opening a potential software and model revenue stream.
- Ambiq won a design with a leading cloud-based physical security provider for an AI glass-break sensor.
- An industrial predictive-maintenance partnership serving U.S. energy operators is expected to generate revenue in 2027.
- Management made an unusually early call for strong 2027 growth, helped by rising ASPs as customers migrate to Apollo 5.
Bears have legitimate ammunition, though:
- Supply constraints left some short-lead-time Q4 demand unfilled and are forcing reliance on expedites.
- Input-cost pressure caps Q4 gross margin at roughly flat sequentially.
- China rose to 17.3% of sales from 6.7% a year ago.
- Non-wearables are expected to remain only mid-single digits of revenue through 2027, reaching low double digits only in 2028. That is a slower diversification curve than the AI design-win narrative suggests.
The market setup is more complicated than the surprise implies. Shares opened at $65.70 after the August report, peaked at $73.08 in late September, then collapsed to $34.96 on November 5. They rebounded to $45.77 ahead of this release, still 30.3% below the post-August open, 37.4% below the quarter high and 14.9% below the 200-day moving average of $53.81. Investor sentiment slid from a mildly positive 0.18 to roughly neutral at -0.01. That is a meaningful cooling but not outright pessimism. The 31% bounce off the low shows buyers had already started to step back in. The Earnings Whispers trend readings are mixed, with momentum positive but AVWAP still negative, consistent with a stock rebuilding from a sharp drawdown.
The bottom line is that Ambiq produced the kind of quarter growth investors look for: accelerating revenue, a margin beat, broader customer concentration and a fourth consecutive increase to the full-year outlook, now about $140 million. What it did not deliver is operating leverage. Expenses are rising nearly as fast as gross profit, supply limits are capping upside, and 2027 spending is undefined. With the stock well off its highs and sentiment reset to neutral, expectations are less stretched than in September. Re-earning a premium likely requires evidence that this growth can eventually translate into profits rather than just larger revenue.
Read our earnings preview for Ambiq Micro, Inc.: https://www.earningswhispers.com/article/AMBQ/22683
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-10 | |
| Nov-02 | |
| Oct-20 | |
| Oct-07 | |
| Aug-11 | |
| Aug-11 | |
| Aug-11 | |
| Jul-29 | |
| Jul-28 | |
| Jun-25 | |
| Jun-23 | |
| Jun-22 | |
| May-12 | |
| May-12 |
