TOYO Faces Visibility Test As Ethiopia Detentions Cloud Post-Guidance Earnings Outlook
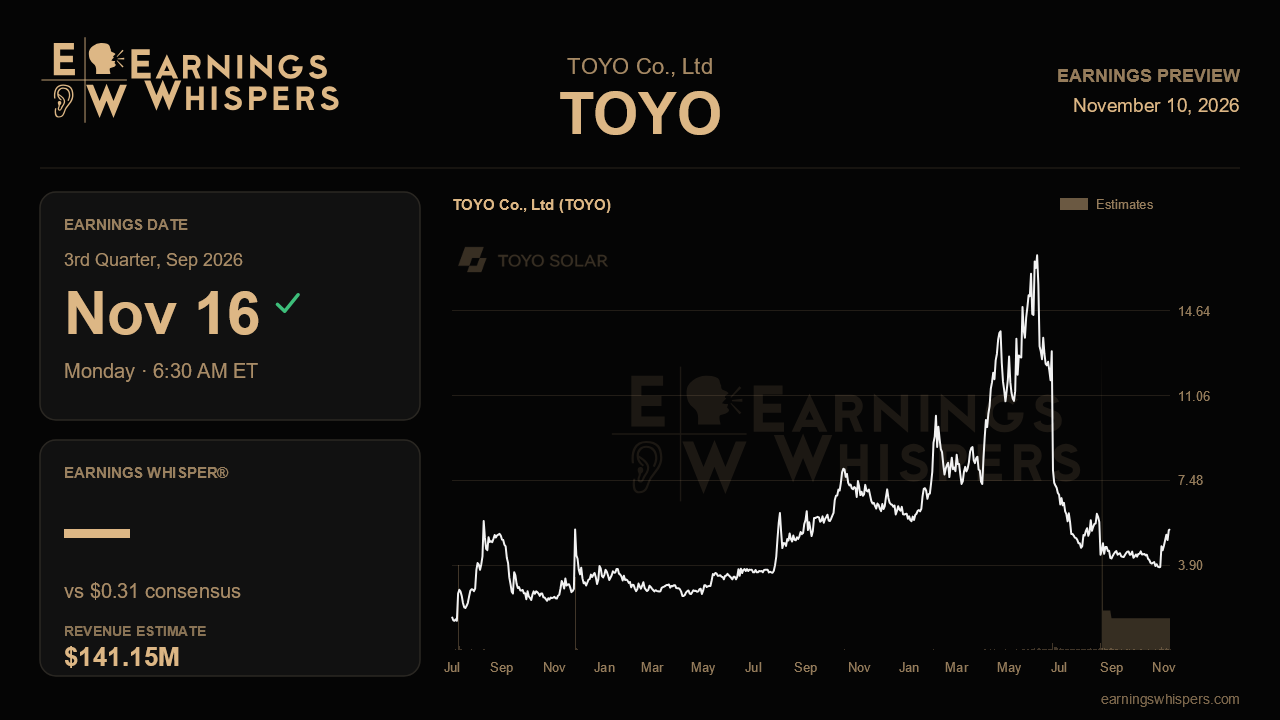
When a company pulls full-year guidance it had reaffirmed only three months earlier, the next report becomes less about the quarter itself and more about whether management can rebuild trust. That is the position TOYO is in heading into its September-quarter results on November 16. The solar cell and module maker has rarely looked healthier on paper, with margins far above year-ago levels and a balance sheet that has turned the corner. However, customs detentions of shipments from its Ethiopia plant and a Commerce Department anti-circumvention inquiry left management unwilling to put numbers on the rest of 2026. This report is the first real look at how much those overhangs actually cost.
The Street is looking for earnings of $0.31 a share on revenue of $141.2 million. That is an unusual combination. Revenue would rebound roughly 19% from the $118.2 million booked last quarter and land close to the first-quarter level, yet profit per share would fall from $0.45. In other words, analysts appear to expect shipments to recover as detained product clears customs, while assuming margins give back some ground, whether from mix, detention-related costs or pricing. The full-year picture tells a similar story. The current $1.90 consensus sits well below the abandoned target of $2.39 to $2.65, and because first-half earnings already account for most of that $1.90, the Street is effectively modeling a much weaker second half than the company originally envisioned.
The operating questions follow directly from last quarter's call. Management framed the Ethiopia detentions as a timing issue rather than a demand problem. A sequential rebound in revenue, particularly in solar cell volumes, which drove the second-quarter decline, would support that view. Flat or lower cell shipments would suggest the detentions are proving stickier than expected. Gross margin is the second test. First-half margin reached 32.5%, compared with 16.6% a year earlier, and holding near 30% would show the profitability gains are structural rather than a product of favorable timing. Watch, too, whether operating cash flow stays positive after a strong $61.4 million first half, since working capital can swing sharply when inventory piles up behind customs holds.
There is also a constructive story management will want to advance. The August Section 232 proclamation sets minimum import prices near $0.38 per watt for modules and offers duty offsets tied to US investment, which fits the company's planned $357 million heterojunction cell plant in Humboldt, Texas. Progress on shifting Ethiopia's polysilicon supply fully to US sources by the fourth quarter could matter for both the customs review and the anti-circumvention case. Any clarity on 45X credit eligibility would be a bonus. New CFO Harada's first full quarter adds another layer, as investors will gauge whether disclosure becomes more or less forthcoming.
Market positioning is conflicted. The stock has climbed about 20% since the last report while the S&P 500 slipped, yet that gain came off a collapse. Shares traded as high as $17.43 in the prior quarter and now sit at $5.42, well below the 200-day average of $7.90. They are pressing against the post-earnings high of $5.56, so a convincing report could trigger a technical breakout from the $3.71 to $5.56 range. Sentiment, meanwhile, has grown more bearish than it was ahead of the last report, suggesting skepticism remains despite the bounce.
Ultimately, the quarter hinges on whether TOYO can show that its Ethiopia shipments are flowing again at healthy margins. If revenue recovers and management offers even a rough frame for the year, the guidance withdrawal starts to look like caution rather than a warning. If cell volumes stay depressed or the regulatory reviews remain unresolved with no timeline, the long-term US manufacturing thesis will have to carry a stock that has little near-term visibility to lean on.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-09 | |
| Nov-02 | |
| Oct-29 | |
| Oct-07 | |
| Sep-28 | |
| Sep-28 | |
| Sep-23 | |
| Sep-21 | |
| Sep-03 | |
| Aug-19 | |
| Aug-19 | |
| Aug-19 | |
| Aug-12 | |
| Aug-07 |
