Harrow's Record Quarter Is Overshadowed By A Halved EBITDA Outlook And A Steep Q4 Revenue Hurdle
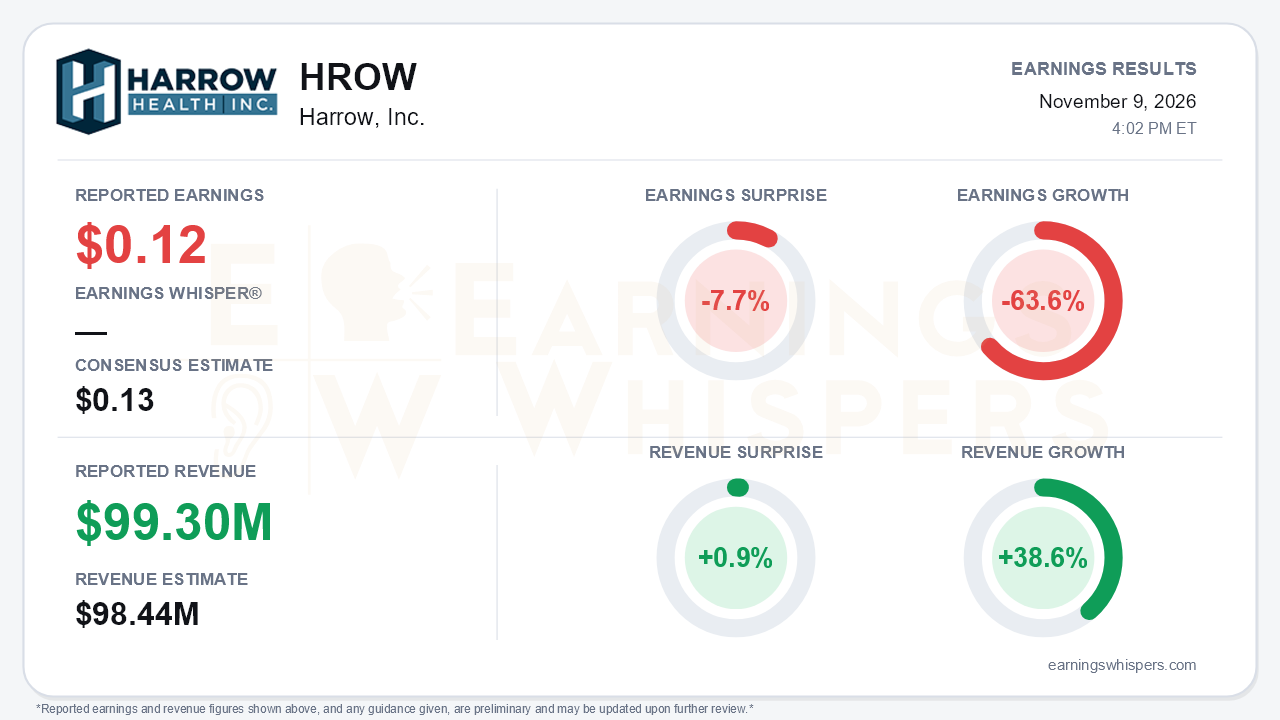
Harrow (NASDAQ: HROW) delivered the revenue acceleration it had promised, but the more consequential news was what it cost. Third-quarter revenue reached a record $99.3 million, up 38.6% year over year and 0.9% above the $98.44 million consensus. Earnings of $0.12 per share missed the $0.13 consensus by 7.7% and fell 63.6% from a year ago. Reported GAAP diluted EPS was $0.25, but that figure includes a $5.0 million one-time litigation settlement gain, so it overstates the underlying earnings power. The central tension is clear. The top line is inflecting, yet management cut its full-year Adjusted EBITDA guidance roughly in half, from $80-$100 million to "more than $40 million." That range had been reiterated on every prior call this year.
The sequential revenue progression is genuinely strong: $44.2 million in Q1, $70.7 million in Q2 and $99.3 million in Q3. Branded products contributed $83.5 million, up 62%, and now make up about 84% of sales. VEVYE was the standout at a record $39.7 million, up from $29.4 million in Q2 and $20.9 million in Q1. Revenue grew 35% sequentially while prescriptions grew 17%, a sign that payer-mix economics are improving rather than volume alone driving the gain. TRIESENCE posted record unit demand of 20,022, more than double the year-ago level.
The profit picture is less convincing. Adjusted EBITDA swung to $21.2 million from a $1.2 million loss in Q2, but it was still below the $22.8 million earned a year ago on far less revenue. Operating income slipped to $11.5 million from $14.7 million because spending outran growth:
- SG&A rose to $53.1 million from $35.9 million.
- R&D roughly tripled to $10.3 million.
Gross margin recovered to 75% from 71% in Q2. However, it was flat year over year and short of the high-70s level management had pointed to last quarter, with compounding margins and mix cited as drags. Nine-month Adjusted EBITDA stands at just $7.3 million versus $37.8 million a year ago.
The new guidance asks investors to believe in a very large fourth quarter. Management reaffirmed $350-$365 million in revenue, which implies roughly $136-$150 million in Q4, a 37%-51% sequential step-up. It also guided to more than $33 million of Q4 Adjusted EBITDA. CEO Mark Baum acknowledged the revenue target "will require strong execution" and called the EBITDA outlook a floor. He attributed the cut to the first-half shortfall plus deliberate spending:
- accelerating the G-MELT NDA, now expected before year-end versus 1H27 previously;
- advancing development programs;
- integrating TYRVAYA, which closed October 1, added about 40 reps and is guided to contribute more than $30 million in 2027.
Additional tailwinds include a third VEVYE coverage win of 2026, covering 10+ million lives effective January, the launch of the HarrowRx prescribing platform, and IHEEZO's seasonally strongest quarter.
Bears have legitimate ammunition beyond the guidance cut:
- **QUELL trial miss:** The Phase 4 study of IHEEZO failed its primary non-inferiority endpoint (55.2% vs. 59.7%), and management is leaning on secondary tolerability data.
- **IHEEZO demand:** Unit demand dipped about 5% sequentially to 62,210.
- **BYOOVIZ launch:** Ordering ran behind the internal model, with accounts described as wide but shallow.
- **License risk:** A 10-Q disclosure flags that the TYRVAYA deal may breach the VEVYE license with Novaliq. Discussions with the licensor are ongoing.
- **Balance sheet:** Cash fell to $75.3 million from $83.9 million at Q2 after the $30 million TYRVAYA upfront payment. Notes payable sit near $293 million against stockholders' equity of only $28.8 million. Nine-month operating cash flow was an outflow of $27.4 million versus an inflow of $35.5 million a year earlier.
This leveraged profile leaves little room for a Q4 stumble.
The market had already turned skeptical before the report. Shares were at $27.47, down 29.6% from the $39.00 open after the August report and about 27% below the 200-day moving average of $37.81. Investor sentiment remained negative and weakened modestly, from -0.31 to -0.37, consistent with an audience that had grown wary of repeated EBITDA reaffirmations. The Earnings Whispers trend signals are split: price and AVWAP trends are negative while sequential growth is positive. That split mirrors the fundamental divide between improving revenue momentum and a deteriorating profit trajectory.
The bottom line is that Harrow showed real commercial traction, led by VEVYE pricing and volume, TRIESENCE demand and a pipeline that is moving faster. However, the halved EBITDA outlook, the QUELL miss, the Novaliq license question and a stretched balance sheet undercut the credibility of the profit story. The reaffirmed revenue guide rests on a record-shattering fourth quarter, so Q4 execution is now the decisive test of whether this quarter marks an inflection or another reset.
Read our earnings preview for Harrow, Inc.: https://www.earningswhispers.com/article/HROW/22636
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-09 | |
| Nov-09 | |
| Nov-02 | |
| Nov-02 | |
| Nov-02 | |
| Oct-26 | |
| Oct-05 | |
| Sep-30 | |
| Sep-01 | |
| Aug-20 | |
| Aug-11 | |
| Aug-10 | |
| Aug-10 | |
| Aug-06 |
