Bitdeer Misses On The Bottom Line As Record Revenue And A $2.9 Billion AI Backlog Run Into A Funding Squeeze
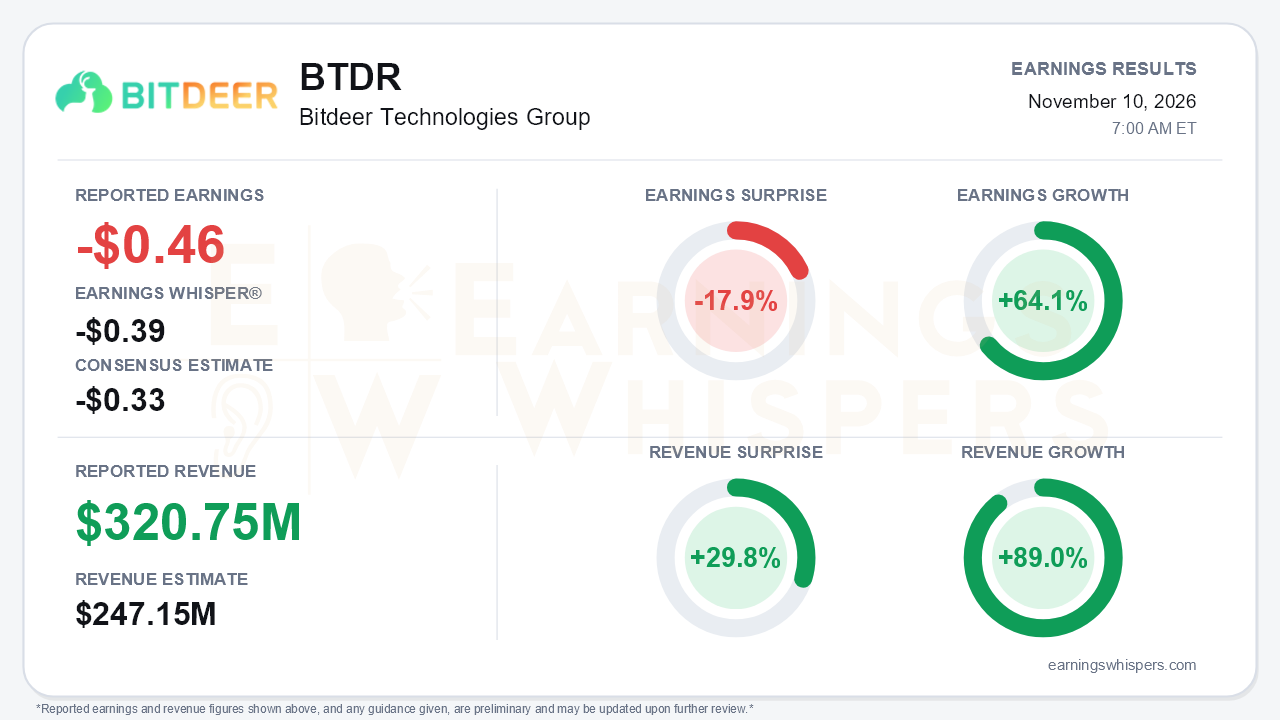
Bitdeer Technologies Group's third quarter delivered the operating inflection bulls have been waiting for, wrapped inside a loss that was worse than expected. The company lost $0.46 per share, missing the -$0.33 consensus by 17.9% and falling short of the -$0.39 Earnings Whisper. Revenue told a very different story. Sales reached a record $320.75 million, beating the $247.15 million consensus by 29.8% and rising 89.0% year over year. Earnings Whispers' normalized comparison shows 64.1% year-over-year earnings growth. Investors should note, however, that on a GAAP basis the net loss widened to $125.5 million from $30.1 million. Revenue growth is clearly accelerating, from $188.9 million in Q1 to $228.8 million in Q2 to $320.7 million now. The central tension is that Bitdeer is converting growth into contracts faster than it is converting capital into cash.
The quality of the miss deserves context. Roughly $54.6 million of the GAAP loss came from a non-cash fair-value hit on Bitcoin-denominated borrowings from a related party. Interest expense also rose to $34.3 million from $20.2 million, and a $9.5 million loss on repurchasing a membership customer's Rockdale capacity added to the pressure. Strip out the fair-value noise and the business still lost money: the adjusted loss was $87.3 million versus $33.4 million a year ago. Depreciation of $125.8 million, more than triple last year's level, explains much of that gap as the SEALMINER fleet moved from inventory onto the balance sheet. Gross margin of 3.4% compares poorly with 23.4% a year ago but is a genuine turn from gross losses in Q2 and Q1. Adjusted EBITDA more than doubled sequentially to $69.6 million, a 21.7% margin, up from $31.1 million in Q2 and $14.4 million in Q1.
The call preserved a credible growth story, and the AI business is starting to look like a real franchise rather than an option. AI Cloud revenue rose 46% sequentially to $20.4 million and swung to a roughly 15% gross margin from a gross loss in Q2. Annualized run-rate revenue reached about $86 million, versus $43 million two quarters ago. The AI Cloud backlog now stands at roughly $2.9 billion. Malaysia's A102 site is sold out on five-year commitments worth more than $800 million, and A201 is over 70% contracted for more than $1.7 billion. Adding the $4.7 billion Tydal lease brings contracted AI revenue to about $7.6 billion. That lease carries a no-fee termination right at year ten. Mining also scaled: BTC mined rose 43% sequentially to 3,855, self-mining hash rate reached 82.3 EH/s, and fleet efficiency improved to 15.4 J/TH.
Bears have legitimate ammunition on the balance sheet. Third-quarter capex reached $478 million, and unrestricted cash fell to $163.7 million from $456.8 million in Q2. Borrowings now total $1.95 billion. Operating cash flow was barely positive at $6.0 million, and only because customer prepayments lifted deferred revenue by $263.8 million. Equity issuance slowed to $58 million from $457 million, so the next leg depends on project-level financing for Tydal and A102 closing on schedule. That financing is arriving in a market where management acknowledged lenders are tightening and differentiating by structure. Execution signals were also mixed:
- Knoxville slipped to Q4 2027, Wenatchee to H2 2028 and Fox Creek to Q4 2027.
- Norway permitting is slowing.
- Clarington remains tied up in litigation.
- Remaining Tydal capex was cited inconsistently, at roughly $250–350 million in prepared remarks versus about $500 million in Q&A.
- Management deferred 2027 guidance and AI Cloud margin targets to the fourth-quarter report.
- Mining capex was trimmed to $200 million or less, with slower investment flagged for 2027 amid tight TSMC wafer supply.
The market setup is more complicated than the revenue surprise implies. Shares opened at $11.12 after the August report and sat at $6.61 heading into this release, down 40.6%. The stock trades about 42% below its $11.46 200-day moving average and about 52% below its September 21 high of $13.66. It made a 52-week low of $5.03 on November 5 and has bounced roughly 31% since. Investor sentiment deteriorated meaningfully over the quarter, falling from -0.14 to -0.44. Trend readings are split: sequential growth and momentum are positive while price and AVWAP remain negative. That split reflects improving operations set against a stock the market has been actively de-risking.
The bottom line is that Bitdeer's quarter was operationally stronger than the EPS miss suggests. Accelerating revenue, a sharp EBITDA ramp, a positive gross margin and multibillion-dollar AI contracts all point the right way. But the investment debate has shifted from whether demand exists to whether the company can fund and deliver capacity on time. Until the Tydal and Malaysia financings close and fourth-quarter guidance clarifies 2027 economics, liquidity and execution risk are likely to weigh as heavily as the backlog.
Read our earnings preview for Bitdeer Technologies Group: https://www.earningswhispers.com/article/BTDR/22688
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-05 | |
| Nov-02 | |
| Oct-29 | |
| Oct-27 | |
| Oct-20 | |
| Oct-20 | |
| Oct-19 | |
| Oct-19 | |
| Oct-12 | |
| Oct-09 | |
| Oct-09 |
