908 Devices Beats As Growth Accelerates To 35%, But Concentration, Mix Shifts And A Softer Profit Path Complicate A Record Quarter
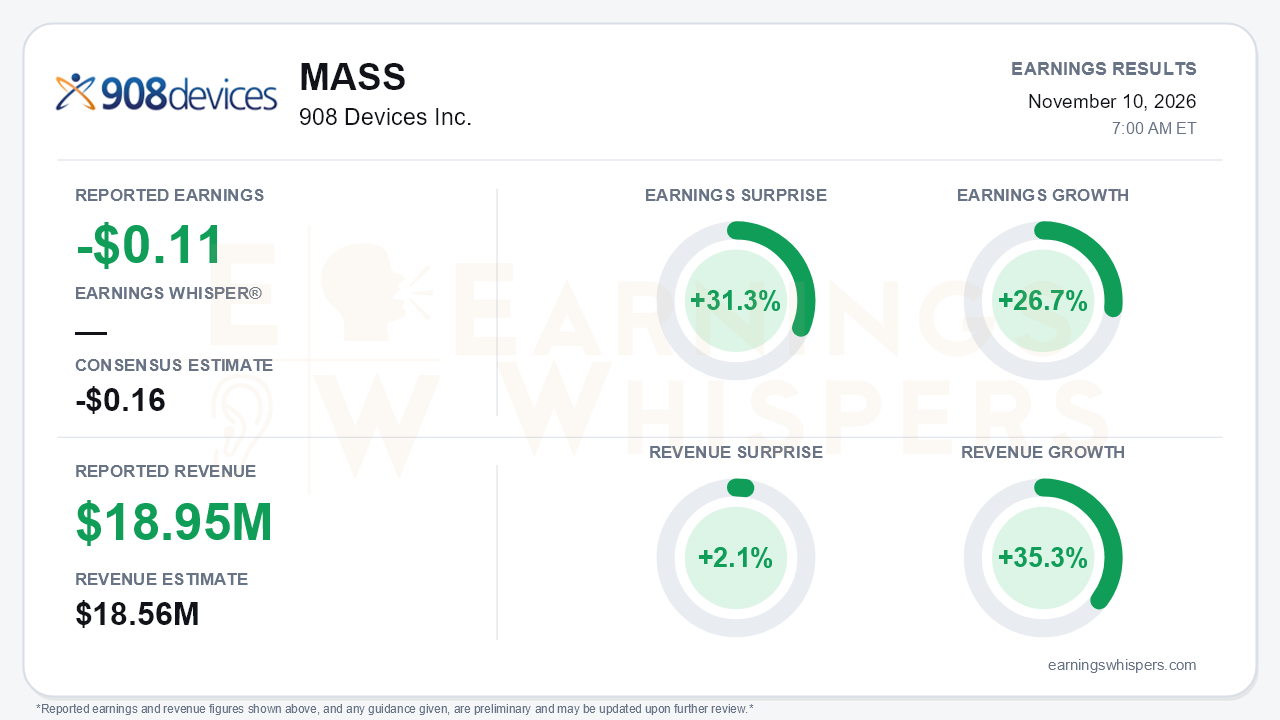
908 Devices (NASDAQ: MASS) delivered its strongest top-line quarter of the year. It reported a loss of $0.11 per share against a consensus estimate of -$0.16, a 31.3% earnings surprise. Revenue of $18.95 million beat the $18.56 million consensus by 2.1% and grew 35.3% year over year. That is a clear acceleration from 14% growth in the first quarter and 23% in the second. Device placements hit a record 308 units, and management raised the low end of its 2026 revenue outlook for the third consecutive call. The central tension is that the growth story improved sharply while the profitability story did not. Several of the quarter's best features also came from sources that are lumpier and less durable than the headline suggests.
The quality of the earnings beat deserves scrutiny. GAAP net loss from continuing operations narrowed to $4.6 million from $14.9 million, and earnings grew 26.7% year over year. Most of that improvement came from an accounting swing, however. Last year's quarter absorbed a $10.7 million charge for the change in fair value of contingent consideration, while this quarter booked a $0.3 million benefit. Strip that out and the operating picture looks very different:
- Adjusted EBITDA was a $1.7 million loss, versus $1.8 million a year ago, barely better despite nearly $5 million of additional revenue.
- Selling, general and administrative expense rose $2.8 million to $12.0 million, absorbing most of the incremental gross profit.
- GAAP gross margin held at 53% and adjusted gross margin at 58%. The call noted the adjusted figure was down roughly 40 basis points on a lower-margin international mix.
The weighted share count also rose to 41.1 million from 36.1 million, diluting the per-share comparison.
The call showed how the revenue base is shifting:
- **International strength.** International revenue doubled to 40% of sales, helped by an Asia-Pacific Protector order worth about $4 million, a European defense framework agreement above $2 million, and a competitive displacement.
- **NIRLab ramp.** The acquired NIRLab platform shipped about 100 units in its first full quarter, up from about 35, and contributed roughly $1.2 million. Management is targeting more than $5 million in 2027.
- **Domestic weakness.** U.S. state and local revenue fell about 20% year over year and shrank to roughly 25% of the mix, from more than half in the second quarter.
- **Concentration.** Two customers accounted for about 41% of quarterly revenue.
- **Recurring revenue.** The recurring share slid to 27% from 31% in the second quarter and 35% for fiscal 2025, and service and contract revenue was essentially flat at $3.2 million.
The growth acceleration is real, but it leans on large, episodic orders rather than a broadening recurring base.
Guidance reinforces that read. The full-year range moved to $68.5-70.0 million from $68.0-70.0 million, and handheld guidance rose to $65.5-67.0 million. The narrowing is modest, though. The midpoint implies only about 20% fourth-quarter growth, and reaching the high end depends on large Viper and mass spectrometry deals plus customer funding timing. Management also softened its profitability framing. The adjusted EBITDA loss is now expected to fall roughly one-third from 2025 including NIRLab, versus the earlier 'cut in half' goal. The earlier target of 100 basis points of gross margin expansion now looks out of reach.
The Army AVCAD opportunity, once assumed at $2-3 million, remains excluded from guidance. That opportunity is now positioned as a 2027 commercial-off-the-shelf path, with the MX-908 in testing and potential margins in the mid-to-high 50s. Management's tone shifted toward previewing three 2027 drivers: AVCAD, NIRLab scaling, and the next-generation MX-908, which is targeted for early-access shipments by year-end. Those are credible catalysts, but they sit beyond the current guidance window.
Investors positioned aggressively ahead of the print. Earnings Whispers sentiment swung from slightly negative (-0.09) before the August report to an extremely bullish 1.07, a reading pushed to the very top of the scale. Shares rose 26.9% from the $9.07 open after the prior report to $11.51 entering this release. That leaves the stock about 36% above its 200-day moving average. It also sits nearly 14% below the $13.35 52-week high set on October 6, so the stock had already given back part of its autumn run. Sequential growth and momentum trend readings are positive, while AVWAP remains negative. That mix is consistent with a stock that rallied hard and then cooled. With sentiment this elevated, the bar for incremental upside is higher than the earnings surprise alone implies.
The bottom line is that 908 Devices delivered a genuine growth acceleration, record placements, and a third straight guidance raise. Bears still have legitimate ammunition:
- The GAAP improvement is largely accounting-driven.
- Adjusted EBITDA barely moved.
- Revenue is increasingly concentrated and international.
- Recurring mix is slipping.
- Management quietly lowered its profitability ambitions.
With $99.1 million in cash and no debt, the company has time to prove its 2027 catalysts. With sentiment near euphoric levels and implied fourth-quarter growth decelerating, execution on those catalysts now matters more than the beat itself.
Read our earnings preview for 908 Devices Inc.: https://www.earningswhispers.com/article/MASS/22701
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-10 | |
| Nov-04 | |
| Nov-03 | |
| Oct-27 | |
| Sep-01 | |
| Aug-12 | |
| Aug-12 | |
| Aug-11 | |
| Aug-10 | |
| Jul-29 | |
| Jul-28 | |
| Jun-02 | |
| May-28 | |
| May-06 |
