Liquidia's Record YUTREPIA Quarter Is Overshadowed By A Settlement That Narrows The Label To PAH, Uses Most Of Its Cash, And Ends The $1B Target
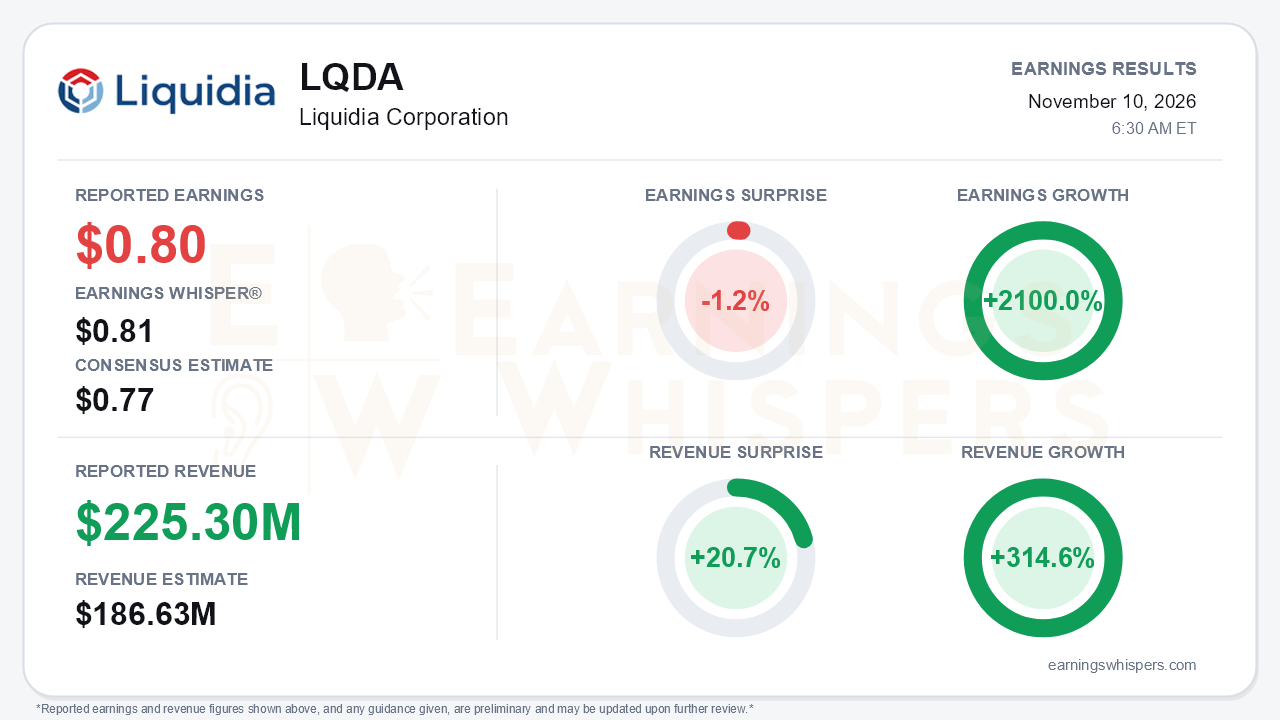
Liquidia Corporation (NASDAQ: LQDA) delivered the strongest commercial quarter in YUTREPIA's short history, yet the most important development came after quarter-end. Adjusted earnings of $0.80 per share topped the $0.77 consensus but fell just short of the $0.81 Earnings Whisper number, a 1.2% miss against the whisper. Revenue told a cleaner story. Sales of $225.3 million beat the $186.63 million consensus by 20.7% and grew 314.6% from a year ago. Earnings rose 2100.0% year over year. The headline beat, however, sits alongside a settlement with United Therapeutics that restricts YUTREPIA to PAH, commits $380.7 million in cash, and quietly retired the $1 billion 2027 revenue target management had repeated on every prior call. That is the central tension: the ramp is real, but the size of the opportunity it is ramping toward just got smaller.
The operating results themselves were excellent. YUTREPIA net product sales reached $222.7 million, up 31% sequentially, extending a climb from $90.1 million in the fourth quarter of 2025 to $129.9 million in Q1 and $170.4 million in Q2. Adjusted EBITDA rose for a fifth straight quarter to $140.5 million, up from $96.3 million in Q2. The implied margin expanded to roughly 63% from about 57%, as gross margin held near 94% and SG&A fell to 26% of revenue from 33%. The quality of the quarter still deserves some scrutiny. Paid patient demand was $212.2 million, modestly below reported net sales. GAAP results were swamped by a $389.7 million litigation charge, producing a net loss of $236.3 million, or $2.64 per share, after net income of $74.7 million in Q2. The balance sheet now shows a stockholders' deficit of $25.4 million. Pre-settlement cash of $396.1 million looks robust until set against the $380.7 million owed in installments through April 2027.
The call explained why investors are focused beyond Q3. The settlement followed a September 30 Delaware ruling that YUTREPIA infringed a United Therapeutics PH-ILD patent. Liquidia agreed not to appeal, filed to strip PH-ILD from the label, and stopped promoting that indication. Existing PH-ILD patients are grandfathered with no payer contract changes. New PH-ILD patients, however, are now off-limits, and management had described that indication as roughly half of new scripts in earlier calls. There are early signs of strain. October's daily referral rate was only about 75% of the Q3 pace, which management attributed to a competitor's dear-HCP letter that confused prescribers. Management characterized that level as a floor, but it remains unproven. Physician attestation requirements and possible reauthorization friction for grandfathered patients early in the year add modest further risk.
There are genuine offsets. October patient shipments hit a launch-high, conversion of referrals to starts stayed above 87%, and the prescriber base grew to about 1,300 from about 1,100 in Q2. More than 70% of September referrals carried a PAH diagnosis, suggesting the business was already tilting toward the indication it retains. The settlement carries no ongoing royalty, so once the final April 2027 payment is made, PAH economics accrue fully to Liquidia. The pipeline also broadened:
- the SPRINT dosing study;
- a selexipag-switch study;
- the RE-WARM trial in SSc-RP, which received Fast Track designation;
- an L606 pivotal PAH study starting in 2027 alongside Re-Spire in PH-ILD, targeting a 2029 filing;
- a planned PH-COPD pivotal study.
The release cautions, though, that the settlement does not extend to non-PAH indications or new treprostinil products. Management said it does not view the PH-ILD patent as a barrier for L606, but that is a company assertion rather than a resolved question. Formal 2027 guidance has been deferred to early January.
The market has already absorbed much of the damage, though not all of it. Shares opened at $83.64 after the August report and now trade at $47.87, down 42.8%. The stock collapsed to a 52-week low of $22.31 on October 1, immediately after the ruling, and has since rebounded about 115% from that low as the settlement removed the worst-case disruption scenario. Even so, shares remain 12% below their 200-day moving average of $54.38 and nearly 45% below the inter-earnings high. Investor sentiment slipped from mildly positive (0.17) to roughly neutral (-0.02), a meaningful cooling consistent with the CEO's own concession that Liquidia is now a "show-me story." The Earnings Whispers trend readings are largely positive on sequential growth, momentum, and AVWAP, while the price trend remains negative, reflecting a strong business attached to a damaged chart.
The bottom line is that Liquidia proved YUTREPIA can generate substantial profits, with a 20.7% revenue beat and expanding EBITDA margins. It also paid a steep price for certainty: a PAH-only label, most of its cash pile, and the loss of a headline growth target. Bears have legitimate ammunition in the October referral slowdown and the deferred guidance. The January 2027 outlook will be the real test of how much growth survives the narrower label.
Read our earnings preview for Liquidia Corporation: https://www.earningswhispers.com/article/LQDA/22795
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-08 | |
| Nov-03 | |
| Nov-03 | |
| Oct-16 | |
| Oct-14 | |
| Oct-14 | |
| Oct-14 |
?? Under the Radar: Liquidia Stock Soars After Settling Patent Fight
LQDA +26.59%
The Wall Street Journal
|
| Oct-14 | |
| Oct-14 | |
| Oct-14 | |
| Oct-14 |
