EquipmentShare Crushes Q3 Estimates As Rental Growth Accelerates To 49%, But Leverage And Cash Burn Keep A Battered Stock In Show-Me Mode
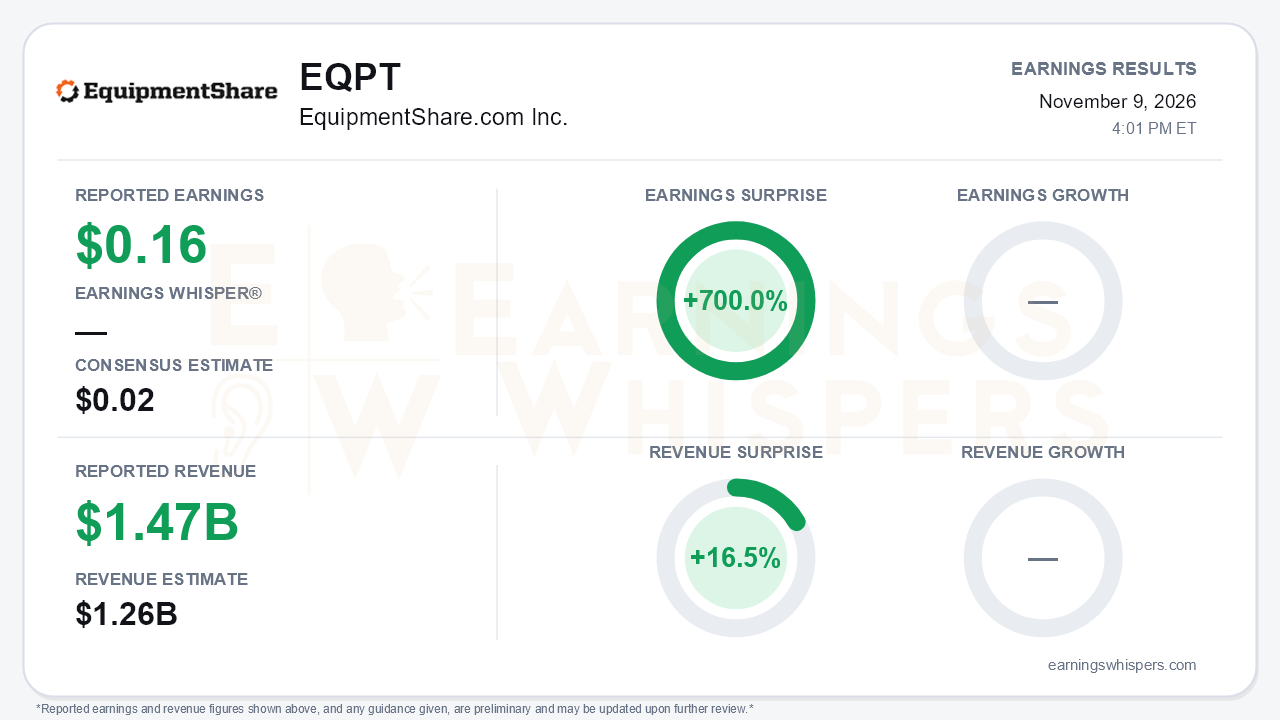
EquipmentShare delivered the kind of quarter that is hard to argue with on the headline. Adjusted EPS of $0.16 beat the $0.02 consensus by 700.0%, and revenue of $1.468 billion topped the $1.26 billion estimate by 16.5%. More important than the size of the beat was the direction of growth. Rental Segment revenue rose 49% to $1.113 billion, up from 39% growth in the second quarter and 37% in the first. That came on only 32% growth in managed fleet OEC, so revenue is growing well ahead of the fleet. The central tension is that the operating story keeps strengthening while the balance sheet and cash profile still give skeptics plenty to work with, and the stock has been trading on the skeptics' side.
The quality of the beat deserves some scrutiny. GAAP net income was $20 million, or $0.03 per diluted share, versus $6 million a year ago. The $0.16 adjusted figure excludes $26 million of stock compensation tied to the IPO Founders Awards. Total revenue growth of 55% was also flattered by the Sales segment, where revenue jumped 76% on a $139 million increase in OWN Program placements. Sales to outside customers actually fell by $12 million, and the segment's adjusted EBITDA margin slipped to 15% from 18%. The rental engine is the real story. Segment adjusted EBITDA rose 52% to $491 million, and margin reached 44%, up about 70 basis points year over year and 130 basis points sequentially. Below the operating line the picture is less clean. Interest expense climbed to $88 million from $75 million, other income fell to $7 million from $26 million, and nine-month operating cash flow was a $179 million outflow as receivables grew by $437 million.
The call reinforced the acceleration narrative. Fleet placed on rent for the first time reached roughly $900 million, versus more than $750 million in Q2 and about $550 million a year earlier. Full-year guidance has now been raised for a third time. Rental revenue growth is guided to roughly 43%, up from 27% originally, and adjusted core EBITDA to about $2.2 billion at the midpoint, up from $1.8-1.9 billion. The release frames total revenue at $5.81-6.05 billion, and management said it sees an opportunity to outperform. The year-end OEC target rose $400 million to about $11.5 billion, which management said will be funded through oversubscribed OWN sales rather than higher net capex. Management's tone has shifted from describing its guide as conservative to openly flagging fourth-quarter upside and citing visibility into 2027-28.
The forward catalysts are substantive. EquipmentShare signed a multi-year Cummins agreement to expand its natural-gas generation fleet to nearly 1 GW and flagged more OEM power partnerships, with impact possibly starting late in Q4. It also has T3 products scaling into 2027, including touchless access control with production described as sold out for about two years. Management guided to roughly $400 million of standalone Q4 free cash flow. It also laid out a mature-state model of about $4 billion in core EBITDA and $1.25 billion in annual free cash flow from the existing 408 locations.
Bears still have legitimate ammunition. Mature-site TTM margins dipped to 54% from 55%. Ancillary services, fuel and delivery, and re-rent created about 310 basis points of rental margin drag, which was masked by SG&A leverage. Full-year net rental capex of roughly $1 billion is now above the original $759-839 million guide, and getting there depends on Q4 OWN sales. Leverage needs careful reading. The release highlights net leverage falling to 3.4x from 3.7x a year ago, but that figure rose from 3.0x in Q2. Liquidity also fell to about $2.3 billion from a pro forma $2.8 billion. Management additionally cited soft local markets, tight OEM supply, and data-center moratorium risk in Texas and New York, with data centers representing about 10% of exposure.
The market has not been rewarding the fundamental acceleration. Shares at $16.21 are down 22.4% from the $20.89 open following the August report and sit 24.4% below the 200-day moving average of $21.43. Investor sentiment remained negative but improved modestly, rising to -0.0531 from -0.1186. That reads more like reduced pessimism than conviction. The Earnings Whispers trend readings are mixed, with momentum positive while AVWAP remains negative.
The bottom line is that EquipmentShare's rental business is accelerating, margins are expanding, and guidance keeps moving higher, which is a stronger operating trajectory than the stock's decline implies. The market's hesitation centers on capital intensity, rising sequential leverage, and negative operating cash flow. Delivering the promised Q4 free cash flow and holding net capex near guidance are now the proof points that matter most.
Read our earnings preview for EquipmentShare.com Inc.: https://www.earningswhispers.com/article/EQPT/22622
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-10 | |
| Nov-09 | |
| Nov-09 | |
| Nov-02 | |
| Oct-29 | |
| Oct-22 | |
| Oct-19 | |
| Oct-19 | |
| Oct-09 | |
| Oct-08 | |
| Sep-29 | |
| Sep-25 | |
| Sep-24 | |
| Sep-15 |
