Cellectar Matches The Consensus Loss, But Slipping Timelines And A Tight Runway Leave The Funding Bridge Exposed
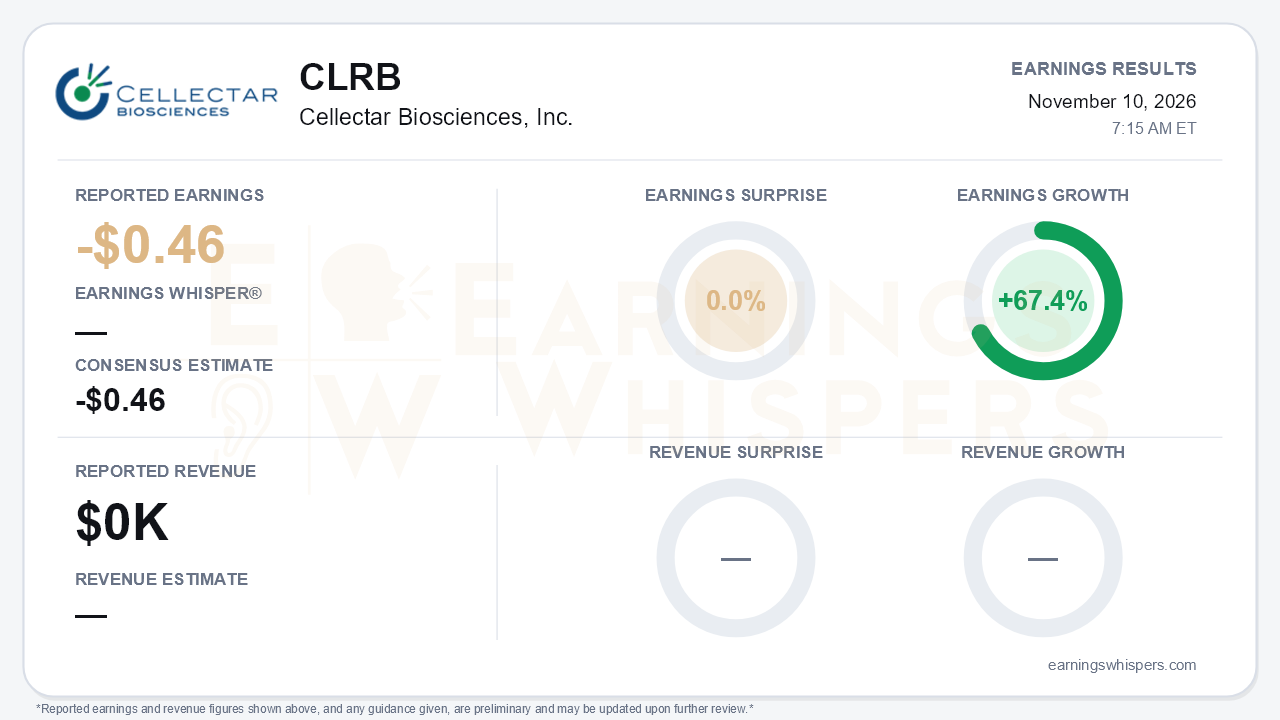
Cellectar Biosciences (NASDAQ: CLRB) reported a third-quarter loss of $0.46 per share, exactly matching the consensus estimate, with no revenue. Earnings Whispers measures earnings growth at 67.4% year over year, but the improvement comes almost entirely from the share count. The net loss nearly doubled to $8.0 million from $4.4 million, while weighted-average shares rose more than fivefold to 17.5 million from 3.2 million. The in-line print is not the story. The real development is that the iopofosine I 131 regulatory plan remains intact on paper while its timelines continue to drift, and the company's financing bridge depends on milestones and share-price conditions the stock is nowhere near meeting.
The quality of the quarter is that of a company moving into late-stage spending. R&D expense climbed to $5.4 million from $2.5 million a year earlier, driven by the start of the Phase 3 confirmatory trial in Waldenström macroglobulinemia (WM) and the CLR 125 triple-negative breast cancer study. The sequential trend is steeper than the annual one:
- R&D rose from $3.0 million in the first quarter to $4.6 million in the second and $5.4 million in the third.
- The net loss widened from $5.7 million to $6.9 million to $8.0 million over the same three quarters.
- Cash fell to $24.6 million from $34.0 million at the end of the second quarter.
Management still says cash funds operations only into the second quarter of 2027, a runway that has not moved since the first-quarter call.
The clinical data have been consistent and supportive. In the immediately post-BTK-inhibitor subgroup (n=24), iopofosine produced an 87.5% overall response rate, a 79.2% major response rate, a 100% clinical benefit rate and a 16-month median duration of response. The only Grade 3 or higher adverse events were cytopenias. The company also reported a single diffuse large B-cell lymphoma case with a complete response lasting more than eight years. Execution signals are also constructive. Phase 3 site activation is running at five to six months versus a typical nine to 12, and a new Phase 1b dosimetry study gives Cellectar an unblinded look at first- and second-line patients. Management framed that study as a route toward NCCN positioning and competition with BTK inhibitors in harder-to-treat frontline subsets.
The calendar, however, keeps sliding:
- First-patient dosing in Phase 3 has moved from "late Q4 2026" to "late 2026 or early 2027" and now to the first quarter of 2027.
- Expected U.S. approval has shifted from the second half of 2027 to late 2027 or early 2028.
- The European conditional marketing authorization filing, once targeted for the third quarter of 2026, is deferred about nine months because of U.S. most-favored-nation pricing concerns.
- CLR 125 interim data slipped from mid-2026 to the San Antonio Breast Cancer Symposium.
No single delay is fatal, but the pattern matters because the funding structure is tied to these dates. Tranche A warrant proceeds depend on enrolling the first Phase 3 patient before the warrants expire in July 2027. They also require a volume-weighted average price of at least $3.45 plus liquidity conditions. With shares at $1.28, that threshold is far away. The FDA's enrollment threshold for accelerated approval is also undefined; management is targeting 5% to 15% enrollment at the time of action. Bears have legitimate ammunition here: a rising burn, a runway ending around the NDA window, and warrant funding that requires both clinical execution and a share price roughly 2.7 times the current level.
The market has priced that tension harshly. Shares are down 49% from the $2.51 open after the August report and sit about 50% below the 200-day moving average of $2.57. The stock set a 52-week low of $1.11 on November 5, just days before the report, and remains only about 15% above it. Investor sentiment nonetheless improved meaningfully, moving from -0.17 to +0.08. That shift suggests the selling may have run ahead of investor pessimism, or that the ASH presentations and NDA timing are drawing renewed interest. The Earnings Whispers trend signals remain mostly negative, with price, sequential growth and AVWAP readings weak and only momentum positive.
The central tension is that the science and the regulatory plan look steadier than the balance sheet and the calendar. Upcoming catalysts could change the tone: three ASH posters including the first public Phase 3 design, CLR 125 data at SABCS, several Phase 3 sites expected active by year-end, and an NDA planned for the first half of 2027. Each further slip, however, pushes the funding question closer to the edge of the runway.
The bottom line is that Cellectar delivered an in-line quarter whose 67.4% earnings growth reflects dilution rather than operating improvement. The investment debate now hinges on whether the company hits Q1 2027 dosing and a 1H 2027 NDA on time, and whether it can secure capital on acceptable terms with the stock trading far below its warrant hurdle.
Read our earnings preview for Cellectar Biosciences, Inc.: https://www.earningswhispers.com/article/CLRB/22690
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-10 | |
| Nov-04 | |
| Nov-03 | |
| Nov-02 | |
| Oct-27 | |
| Oct-15 | |
| Sep-29 | |
| Aug-17 | |
| Aug-13 | |
| Jul-30 | |
| Jul-15 | |
| Jun-01 | |
| May-14 | |
| May-14 |
