BrainsWay Misses On EPS, But Margin Expansion And A Swelling Backlog Make The Shortfall Look Like Noise In A Stock Priced For Trouble
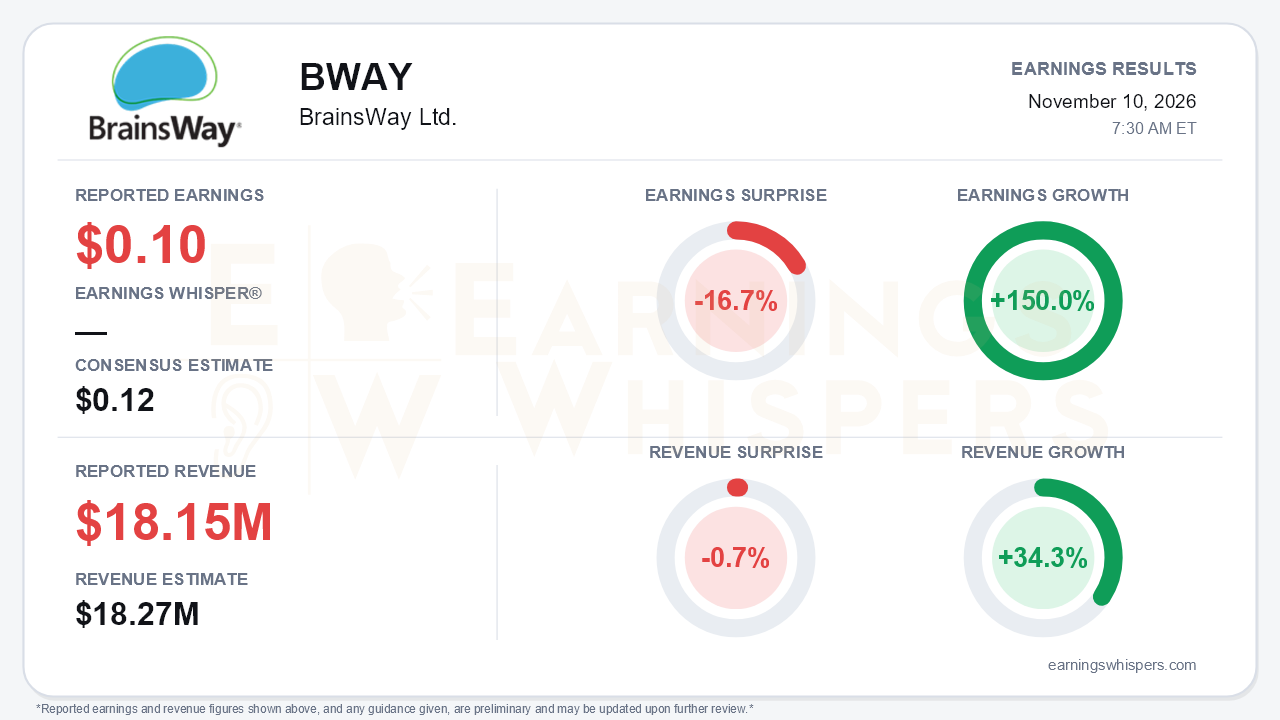
BrainsWay (NASDAQ: BWAY) missed on the headline but showed a business that is getting stronger. The company reported third-quarter earnings of $0.10 per share, short of the $0.12 consensus by 16.7%. Revenue of $18.15 million missed the $18.27 million estimate by 0.7%. Even so, earnings grew 150.0% from a year ago and revenue rose 34.3%. Management also moved full-year 2026 guidance to the upper end of its ranges and flagged potential to modestly exceed them. That is the central tension: a small miss against expectations in a quarter where nearly every operating indicator improved.
The quality of the quarter is better than the EPS miss suggests, though the earnings line deserves scrutiny. The normalized $0.10 figure differs from the company's IFRS results. On an IFRS basis, diluted EPS was $0.05, up from $0.04, and net income rose 42% to $2.2 million. Operating income, by contrast, rose 107% to $2.6 million.
The gap between operating and net income came from below the operating line:
- Finance income fell to $0.3 million from $1.1 million a year earlier.
- Finance expense, tied to periodic loan valuation, rose to $0.7 million.
At the operating level, the picture is clean:
- Gross margin jumped to 78% from 75% in both Q2 and the year-ago quarter. Management attributed the gain to bill-of-materials savings and the end of royalty payments, and called it sustainable into 2027.
- Adjusted EBITDA nearly doubled to $3.9 million, a 21% margin versus 15% a year ago.
- Operating cash flow was $6.2 million, compared with $1.4 million last year.
The weak spot is spending. Operating expenses rose 29%. R&D climbed 47% and G&A 39%, and share-based compensation more than doubled. Management said roughly $1 million of Q3 costs were one-time.
Growth is holding steady rather than accelerating. Revenue growth of 34% compares with 35% in both Q1 and Q2, so the top line is essentially on a plateau, not speeding up. The leading indicators are still climbing, though:
- **Shipments:** 130 Deep TMS systems, up 44%, following 117 in Q1 and 125 in Q2. The installed base now stands at about 2,080 systems.
- **Backlog:** Remaining performance obligations reached $85 million, up 31%, extending a steady progression from $70 million at year-end, $75 million in Q1 and $80.4 million in Q2.
- **Orders:** Management cited a book-to-bill ratio of roughly 1.3-1.4x.
- **Deferred revenue:** Current deferred revenue rose to $16.8 million from $10.6 million at year-end.
Together these point to demand running ahead of recognized revenue.
Reimbursement remains the most important catalyst. Coverage for the SWIFT accelerated protocol now exceeds 70 million U.S. lives. That is up from about 57 million at Q2 and well ahead of the 40-50 million year-end target set in Q1. Management said about half of new demand requests involve SWIFT. OCD coverage expanded to roughly 118 million lives, and the OCD coil base crossed 1,000. International revenue is growing 50-100%.
On 2027, management offered preliminary framing rather than formal guidance. It expects opex growth of 15-20%, with most incremental revenue falling to EBITDA.
Bears still have legitimate ammunition:
- FDA clearance for comorbid PTSD/MDD, which the Q1 call targeted for before year-end, remains in review.
- Orders from partnerships such as the new Inland Psychiatric collaboration are lumpy, and their meaningful contribution has been deferred to 2027.
- The minority stakes in MSO-style providers, including $3 million more into Radial Health, tie up capital in early-stage ventures.
- The guidance change is a steer to the top end, not a formal raise.
The market setup is more complicated than the surprise implies. Shares entered the report at $11.64, down 26.4% since the open after the August report. That leaves them about 16% below the 200-day moving average of $13.90 and a third below the $17.40 52-week high set on August 12. The stock touched an inter-earnings low of $10.50 on November 5 and sits only about 11% above it. Investor sentiment collapsed over the period, from a mildly positive 0.12 to a deeply negative -0.71. Expectations were therefore depressed heading into the print. The Earnings Whispers trend readings reflect the same split between fundamentals and price: sequential growth and momentum are positive, while price and AVWAP trends remain negative.
The bottom line is that BrainsWay's EPS and revenue misses are narrow, while the underlying trend is strong. Margins expanded, cash generation improved, backlog keeps building and reimbursement is outrunning management's own targets. The stock has been treated as if something broke, but the release shows no sign that anything did. The open questions are whether flat-lined 34-35% revenue growth can re-accelerate as backlog converts, and whether the PTSD clearance arrives. Until then, sentiment this negative leaves room for the fundamentals to matter more than the miss.
Read our earnings preview for BrainsWay Ltd.: https://www.earningswhispers.com/article/BWAY/22689
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-10 | |
| Nov-02 | |
| Nov-02 | |
| Oct-28 | |
| Oct-26 | |
| Oct-19 | |
| Oct-13 | |
| Sep-08 | |
| Aug-27 | |
| Aug-12 | |
| Aug-12 | |
| Aug-11 | |
| Jul-29 | |
| Jul-20 |
