Aviat Networks Misses As Supply Constraints And Margin Erosion Overshadow Record Bookings
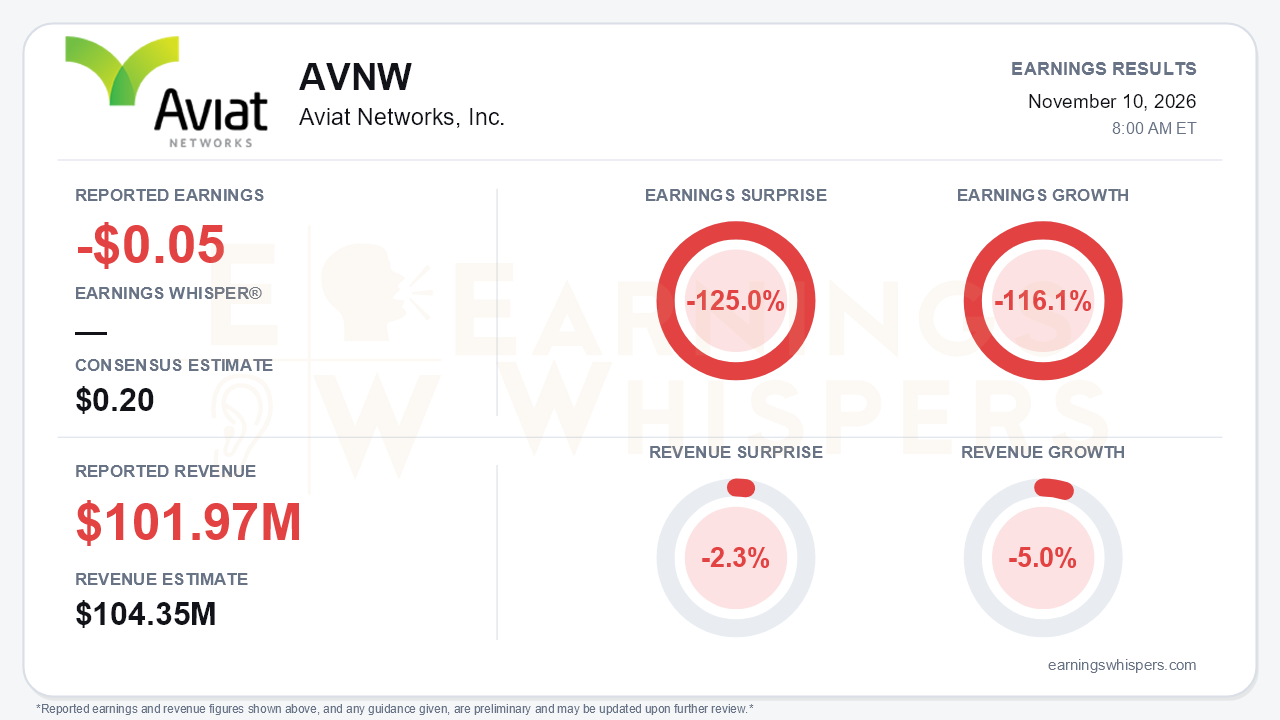
Aviat Networks delivered a quarter with two very different stories. Demand is the strongest it has been in some time, but Aviat could not convert it into revenue or margin. By Earnings Whispers' normalized measure, Aviat posted a fiscal first-quarter loss of $0.05 per share. Consensus expected a $0.20 profit, so the result was a 125.0% negative surprise, and earnings fell 116.1% from a year ago. Revenue of $101.97 million missed the $104.35 million consensus by 2.3% and declined 5.0% year over year. The normalized figure sits between the company's two reported numbers: a GAAP loss of $0.22 per share and non-GAAP earnings of $0.12, down from $0.43 a year earlier. On any of the three bases, profitability deteriorated sharply. Meanwhile, bookings topped $150 million, a first-quarter record and up 75% from a year ago. That is the central tension: Aviat is gathering orders far faster than it can ship them profitably.
The quality of the quarter deserves scrutiny, starting with gross margin. Non-GAAP gross margin fell to 29.6%, versus 33.8% a year ago, 30.9% in the fiscal fourth quarter, and roughly 31.7% expected by analysts. The release attributed the decline to regional and product mix. The call added that about 170 basis points came from component expediting costs, which is a direct cost of chasing scarce supply. Cost discipline softened the damage but could not offset it. Non-GAAP operating expenses fell 7.5% to $26.2 million. Even so, non-GAAP operating income halved to $3.9 million, and adjusted EBITDA slid to $6.0 million (5.9% of revenue), down from $9.1 million a year ago and $11.9 million last quarter. Revenue also fell sequentially, from $120.9 million in the prior quarter. This was a step backward, not merely a soft comparison.
The call made clear that supply, not demand, is now the gating factor. Management cited:
- about $8 million of lost revenue from electronic component shortages, worsened by competition with hyperscalers for parts;
- about $2 million lost to flooding at a Thailand contract manufacturer.
The demand side looked genuinely robust:
- Book-to-bill exceeded 1.5.
- Backlog rose about $70 million, or 19%, from the $367 million year-end level.
- Aprisa bookings grew 61%, ahead of the company's earlier target of more than 50%, driven by North American utilities.
- Bookings rose year over year in every region outside APAC.
The MDU program has steadily scaled, from a small initial order to an eight-figure order, then a $25-30 million order, and now a $35-40 million follow-on plus additional orders. Management reaffirmed a roughly $100 million annual opportunity and expects a full ramp in the March quarter. The first BEAD-related orders also arrived, a program that had been carried at zero in guidance a few quarters ago.
Guidance requires careful reading. Earnings Whispers characterizes it as lowered in line with estimates. Management widened the fiscal 2027 revenue range to $450-475 million from $455-470 million, cutting the low end while raising the top and holding the midpoint. Adjusted EBITDA guidance remained $50-55 million. Beneath that, Aviat is walking away from $25-30 million of low-margin APAC revenue, likely India, after failing to agree on price. Management expects the exit to lift gross margin by 1-2 points, and it is counting on MDU and broader demand to fill the gap. The math is demanding. Starting from $6.0 million of first-quarter EBITDA, the plan requires a steep back-half ramp. Management also acknowledged that some September MDU revenue could slip into fiscal 2028.
The balance sheet absorbed the supply push. Operating cash flow was negative $6.3 million after Aviat paid down $26 million of payables to secure components. Cash fell to $55.4 million from $72.8 million, and net debt rose to $30.5 million from $24.2 million, even though total debt declined $11.1 million. One positive offset is that unbilled receivables fell for a fourth straight quarter, to $75.1 million.
Investors were already skeptical heading into the report. Earnings Whispers sentiment became more negative, falling from -0.07 to -0.19. That is a meaningful deterioration, though still only modestly bearish in absolute terms. Shares closed at $19.13 before the release, down 16.9% since the open following the August report and about 9.3% below the 200-day moving average of $21.09. The stock had fallen from an inter-earnings high of $24.00 on August 27 to a low of $16.81 on November 5, and it entered earnings roughly 14% above that low. Price and AVWAP trend readings remain negative, consistent with a market that has been discounting execution risk for months.
The bottom line is that Aviat's quarter was weak on every reported profitability measure, with margins hurt by expediting costs and revenue capped by supply constraints. Record bookings, a 19% backlog build, MDU scaling, and first BEAD orders give the company a credible growth story that bears cannot dismiss. Still, the burden of proof has shifted to execution. Aviat must secure components, recover gross margin toward the low-30s, and convert backlog fast enough to justify an unchanged EBITDA outlook that now depends heavily on the back half of the year.
Read our earnings preview for Aviat Networks, Inc.: https://www.earningswhispers.com/article/AVNW/22686
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-10 | |
| Nov-02 | |
| Oct-30 | |
| Oct-23 | |
| Oct-20 | |
| Oct-13 | |
| Oct-09 | |
| Oct-05 | |
| Aug-27 | |
| Aug-27 | |
| Aug-26 | |
| Jun-30 | |
| Jun-22 | |
| May-26 |
