Ampco-Pittsburgh's Cash Surge Outshines A Thin Earnings Quarter As EBITDA Momentum Cools And More Weight Shifts To Q4
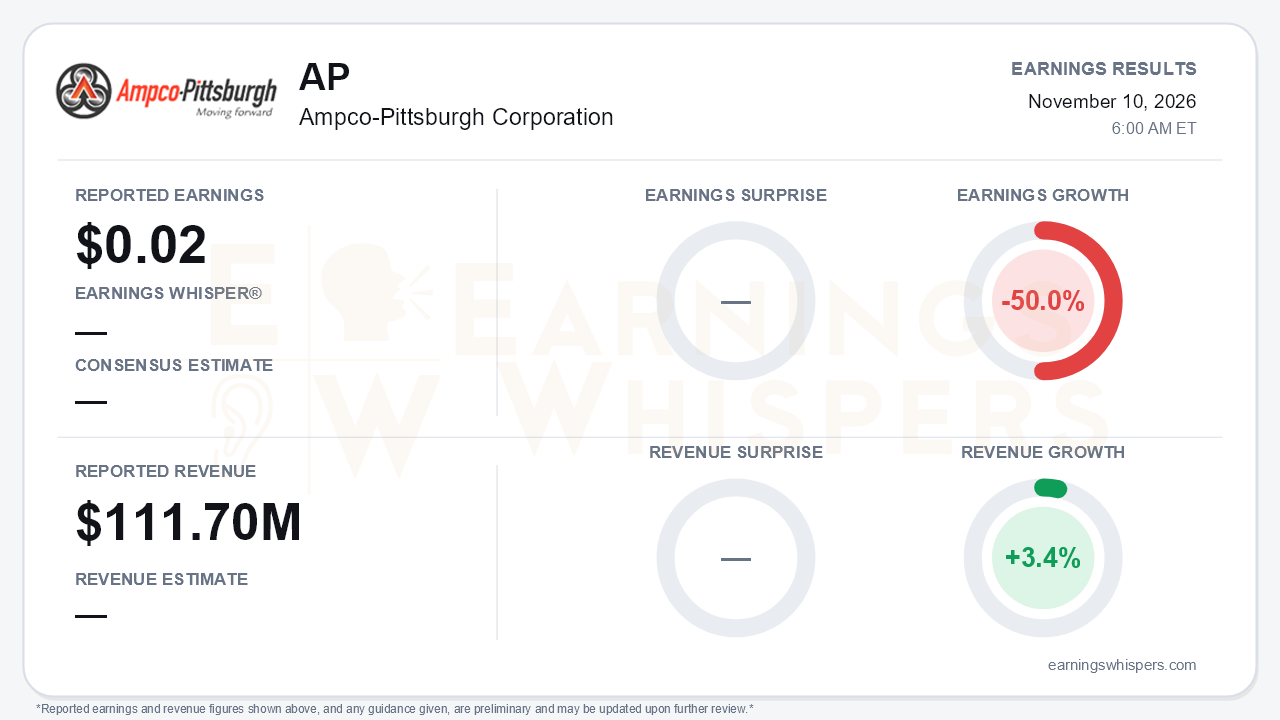
Ampco-Pittsburgh's third quarter was a balance-sheet story more than an earnings story. The company reported earnings of $0.02 per share on revenue of $111.7 million. Revenue grew 3.4% year over year, but earnings fell 50.0% on Earnings Whispers' normalized basis. No consensus estimate was available, so there is no meaningful surprise to measure.
The reported GAAP comparison looks very different from the normalized one. On a GAAP basis, net income attributable to Ampco swung to $0.5 million, or $0.02 per share, from a loss of $2.2 million, or $0.11 per share, a year earlier. That prior-year loss, however, included $3.1 million, or $0.15 per share, of costs to exit the U.K. cast roll operations. The normalized decline reflects that the underlying bottom line did not improve as much as the GAAP swing suggests.
The quality of the quarter deserves scrutiny. Operating income rose to $4.6 million from $1.1 million, but much of that gain came from the absence of prior-year exit costs and $2.4 million of accelerated depreciation. Management said the operating gains were largely offset by higher corporate costs and foreign exchange losses. Two line items show this clearly:
- **Corporate costs:** the adjusted corporate loss widened to $3.2 million from $2.3 million.
- **Other items:** other expense of $0.4 million replaced $0.7 million of other income a year ago.
Adjusted EBITDA rose just 2% to $9.4 million, and margin slipped to 8.4% from 8.5%.
The segment picture is more encouraging. Forged and Cast Engineered Products sales fell 4% to $68.9 million because the closed U.K. plant dropped out of the comparison. Excluding that facility, segment sales rose about 10%. Adjusted operating income rose 9% to $7.7 million, lifting margin to 11.2% from 9.9%, which supports management's claim that the 2025 restructuring and the Sweden ramp are paying off. That improvement came despite an extended outage at the Burgettstown 5,000-ton forge press, where an inspection uncovered base issues. Air and Liquid Processing revenue rose 17% to $42.8 million after being flat in Q2, driven by:
- custom air handling systems;
- power-generation pumps;
- U.S. Navy programs.
Segment profit grew a slower 9%, and margin compressed to 11.3% from 12.2% on product mix.
The central tension is that cash and orders strengthened while earnings momentum cooled from Q2's inflection. Adjusted EBITDA growth decelerated to 2% from 22% in Q2. Consolidated margin fell to 8.4% from 9.5% sequentially, and ALP profit growth slowed to 9% from 34%. Backlog slipped sequentially to $379.5 million from $385.4 million, although it remains up $50.6 million since year-end. The call indicated that ALP backlog growth versus year-end narrowed from 39% to 29%. The release also conceded that some forged and cast activity once expected in 2026 now extends into 2027. Management did not explicitly restate its Q2 framing of a significantly stronger second half. First-half adjusted EBITDA was $17.8 million against Q3's $9.4 million, so delivering on that framing would require a strong fourth quarter.
Cash generation is where the quarter genuinely impressed:
- Operating cash flow rose $15.5 million to $21.8 million.
- Free cash flow reached $19.7 million versus $4.6 million a year ago.
- Net debt fell $19.5 million in the quarter to $111.0 million.
- Debt reduction totals roughly $13.3 million year to date, according to the call, already above the $8 million to $10 million full-year target set in May.
Management described the working-capital gains, including better customer terms and larger upfront deposits, as sustainable. It also cautioned that further improvement will be gradual, which suggests Q3's cash surge should not be extrapolated. Forward catalysts are tangible. ALP booked $31 million of orders in October, including $21 million for power-generation heat exchangers. Navy-funded equipment is adding capacity, and the press repairs position the company for a busier 2027. The balance sheet remains a constraint, with $9.3 million of cash and $31.5 million of total liquidity.
Market context is limited. Shares opened at $9.40 after the August report, above a 200-day moving average now at $8.77. Without current price or sentiment data, it is unclear how investors have positioned into this print.
The bottom line is that Ampco-Pittsburgh delivered a credible restructuring and deleveraging quarter wrapped around an underwhelming earnings result. The GAAP swing to profit flatters the trend, and normalized earnings fell by half. EBITDA growth stalled, backlog dipped, and some forged-products demand slipped into 2027. Strong cash conversion, debt reduction ahead of target and October's power-generation orders keep the 2027 story intact. Execution in Q4 now carries more of the burden of proof than it did after the second quarter.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 9 hours | |
| 12 hours | |
| 13 hours | |
| 15 hours | |
| Nov-02 | |
| Sep-22 | |
| Sep-16 | |
| Sep-16 | |
| Aug-11 | |
| Aug-11 | |
| Aug-11 | |
| Aug-11 | |
| Aug-03 | |
| Jul-08 |
