Jerash's Profits Jump 300% On Margin Strength, But A Capacity Ceiling Is Capping Growth
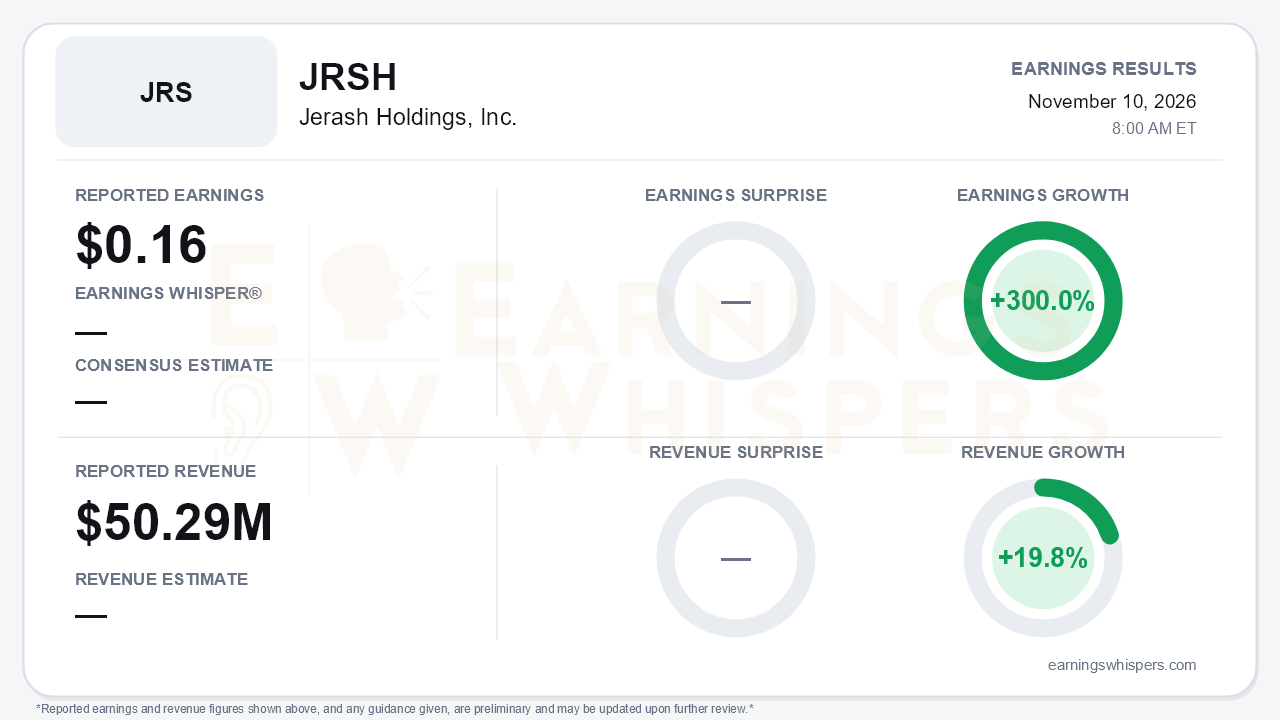
Jerash Holdings (NASDAQ: JRSH) delivered the most profitable quarter in its recent run, but the report also shows a hard limit on how fast the business can grow. Fiscal second-quarter earnings came in at $0.16 per share, up 300.0% from $0.04 a year earlier, on revenue of $50.29 million, up 19.8%. No consensus estimate or Earnings Whisper was available, so the cleaner benchmark is management's own guidance. Revenue landed inside the $49-51 million range. Gross margin beat the 14-15% target by a wide margin. That is the central tension: profitability is outrunning expectations, while top-line growth keeps slowing because the factories are full.
The margin beat was substantial. Gross margin reached 18.2% in the release (the call cited roughly 18.1%), up 320 basis points from 15.0% a year ago and above the 16.4% posted in the first quarter. Management credited:
- a richer mix of higher-margin U.S. shipments;
- automation gains;
- tighter wastage controls;
- raw materials bought early in the quarter.
Operating income nearly tripled to $3.1 million, from $1.1 million, and rose from $2.6 million in Q1. Pretax income roughly quadrupled to $2.56 million. Below the operating line, the earnings also got help. Jordan's corporate tax concession, which cut the rate from 20% to 10%, pulled the effective tax rate down to 15.7% from 24.3%. Management had projected 25-30% just a few quarters ago. The underlying operating improvement is real, but part of the EPS surge reflects a lower tax bill rather than better execution.
The quality of the margin beat deserves scrutiny. On the call, the CFO could not separate durable efficiency gains from the boost provided by early raw-material purchases. The third-quarter outlook implies some of that benefit will fade. Management guided gross margin to 16-17%, citing:
- higher transportation costs for imported raw materials amid regional shipping disruptions;
- costs of onboarding new workers.
That range is still above the prior quarter's 14-15% guide, which makes it effectively a raise. It nonetheless signals a step down from Q2's peak.
Cash generation improved sharply. Six-month operating cash flow was $7.5 million, versus $318,000 a year ago, and cash and restricted cash rose to $16.9 million from $12.5 million at fiscal year-end. Much of that came from working capital: inventories fell by about $6.6 million, partly offset by a $3.2 million increase in advances to suppliers. That pattern fits the early-buying explanation. It also suggests the cash swing may not repeat at the same scale.
Demand is not the problem. Facilities are fully booked with confirmed orders through June 2027, up from December 2026 two quarters ago. Customers are being asked to push excess demand into later quarters. The pipeline expanded on the call:
- a 5.35 million-piece order from Hansel, up from roughly 3 million plus a 1.3 million-piece follow-up previously;
- trial production for a Korean apparel conglomerate described as much bigger than Hansel;
- an initial trial order with an iconic American lifestyle brand.
The constraint is supply, and here the news weakened. Phase one of the capacity expansion now targets about 8% by December, versus roughly 15% by the end of calendar 2026 previously. Phase two is now 15-20% by September 2027, versus 20-25% by mid-2027. A planned two-shift trial at one factory offers some near-term relief.
Those cuts explain the growth trajectory. Year-over-year revenue growth has decelerated from 46.6% to 26.7% to 19.8%, and the Q3 guide implies about 17-22%. Sequential revenue is stuck near $50 million.
The call also left two loose threads. Interest costs are rising from the facility mortgage and supply-chain financing. The Urban Outfitters and other brand wins highlighted last quarter went without an update.
Market context is thin. No sentiment reading or current price was supplied. Shares opened at $5.26 after the August report, comfortably above the current 200-day moving average of $4.31, so the stock entered this quarter trading above its longer-term trend. Without a current quote, it is unclear how much of the earnings ramp was already reflected in the price.
The bottom line is that Jerash is converting a sold-out order book into sharply higher margins and earnings, with a timely tax break amplifying the result. Bears still have legitimate ammunition. The margin peak may partly reflect one-time purchasing, and revenue growth is decelerating against a capacity ceiling that management just pushed further out. Until new capacity actually arrives, earnings growth depends more on holding margins than on volume, which makes the 16-17% third-quarter margin guide the key number to watch.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-05 | |
| Oct-28 | |
| Sep-11 | |
| Aug-20 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 | |
| Aug-07 | |
| Aug-07 | |
| Jul-30 | |
| Jul-21 | |
| Jun-15 |
