ACCESS Newswire Beats On Cost Cuts, But Shrinking Press Release Volume And A Lower Subscriber Target Leave Its Growth Story In Doubt
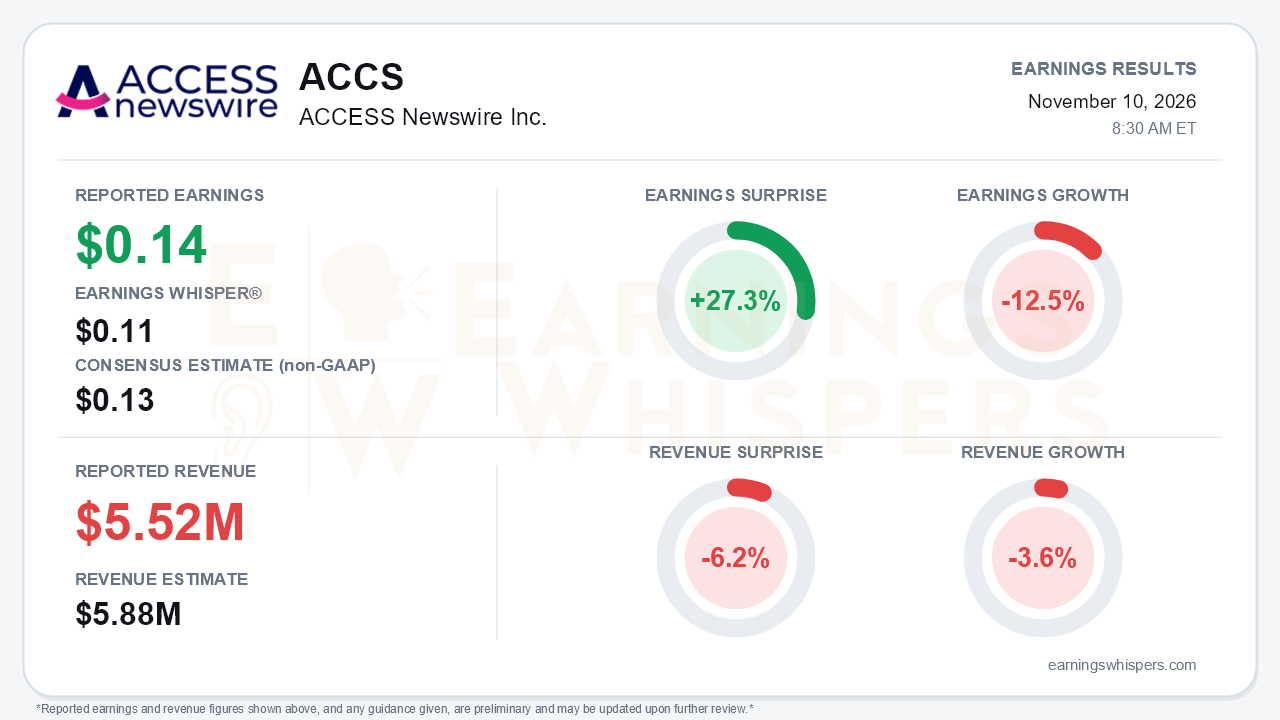
ACCESS Newswire delivered a third-quarter beat on profitability while the core business got smaller. Non-GAAP earnings of $0.14 per share topped the $0.13 consensus and the $0.11 Earnings Whisper number, a 27.3% surprise, but still fell 12.5% from a year ago. Revenue of $5.52 million missed the $5.88 million consensus by 6.2% and declined 3.6% year over year. That is the central tension. Margins and cash flow are improving because management is cutting costs, while demand for the company's main product is deteriorating.
The quality of the beat deserves scrutiny. Gross margin rose to 75% from 73% in Q2, but the company attributed much of that gain to lower distribution costs tied to lower volumes through variable-rate partners. In effect, part of the margin improvement came from shrinking volume. Operating expenses fell to $4.3 million from $4.5 million a year ago. Some of that came from lower non-recurring and bad debt expense. Some came from lower product development expense, which reflected higher capitalized software costs: $303,000 year to date versus $23,000 last year. Adjusted EBITDA of $829,000, or 15% of revenue, was a clear sequential improvement from 11% in Q2. It was still below the $933,000, or 16%, reported a year ago. On a GAAP basis, the company lost $0.02 per share from continuing operations, compared with a $0.01 loss in the prior-year quarter. Cash generation was the cleanest positive. Adjusted free cash flow was $375,000, up from $50,000 in Q2 and from negative $418,000 a year ago, and nine-month adjusted free cash flow reached $1.4 million.
The operating trends changed sharply from the prior quarter. Core press release volume fell 15% sequentially and 12% year over year. Last quarter, sequential volume grew about 10% and core revenue rose 2% year over year. Management blamed an industry-wide slowdown and also cited competition from earned-media and pitching vendors that are drawing small-business budgets away from paid releases. Higher revenue per release, helped by Insights & Analytics, social monitoring, and PRO, only partly offset the volume decline. The subscription metrics were more troubling:
- **Subscribers:** The count grew to 1,213, but management cut its year-end target to 1,300-1,350 from the 1,500 set earlier in the year.
- **ARR per subscriber:** Average ARR per subscriber fell for a second straight quarter, to $12,331 from $12,718 in Q2. Year-over-year growth slowed to 6% from 15%. In Q2, management had said this metric would hold steady in Q3.
- **Deferred revenue:** It edged down to $5.0 million.
- **Content Studio:** The product, promised on the Q2 call for early Q4 with an expected 10-15% subscription uplift, went unmentioned.
- **Retention and net revenue retention:** Neither metric was updated.
The tone of the call shifted from growth investment to defense. In October, management restructured across sales, development, editorial, and operations. The company expects more than $1.5 million in annualized savings, about $300,000 of it in Q4. It also expects sales and marketing spending to fall in 2027. The margin framing softened to "mid-teens" Adjusted EBITDA from the earlier "mid to high teens," and the Q2 target of "higher 70s" gross margin remains unmet. On the product side, the company launched SPOT AI pre-distribution agents, with paid add-ons such as LLM visibility scoring and an earnings audit. It also introduced a $249-per-month small-business tier targeting roughly $6,000-6,500 in ARR. That tier could add subscribers, but it will likely dilute ARR per subscriber further. Bears have legitimate ammunition here: the cost cuts touch the very sales and development teams needed to deliver the promised "return to top-line growth in 2027." That goal is an aspiration, not formal guidance.
Capital return is also a factor. The company completed a $1 million buyback and the board approved a new plan. It is funding that from a modest base: about $3.0 million in cash against roughly $1.9 million in notes payable.
The market had already priced in much of the damage. Shares fell 50.7% from the $6.83 opening after the August report to $3.37. They hit a 52-week low of $3.21 on November 5, just days before the release, and now sit nearly 48% below the 200-day moving average of $6.47. Investor sentiment remained negative but improved meaningfully, rising to -0.34 from -0.85. That suggests expectations had become extremely depressed rather than hopeful. The price trend and AVWAP readings remain negative, consistent with a stock still under clear distribution.
The bottom line is that ACCESS Newswire produced a profitability beat with a shrinking top line. Margin, EBITDA, and cash-flow gains came largely from cost discipline and lower volume-driven expenses, not from demand. The lower subscriber target, falling ARR per subscriber, double-digit volume declines, and a missing product launch all weaken the growth narrative. With the stock already cut in half and sentiment less negative, the bar is low. Credibility now depends on whether SPOT, the small-business tier, and the restructuring can stabilize revenue before cost savings run their course.
Read our earnings preview for ACCESS Newswire Inc.: https://www.earningswhispers.com/article/ACCS/22848
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 10 hours | |
| 13 hours | |
| Nov-04 | |
| Nov-03 | |
| Nov-02 | |
| Oct-15 | |
| Sep-18 | |
| Sep-03 | |
| Aug-31 | |
| Aug-11 | |
| Aug-11 | |
| Aug-04 | |
| May-14 | |
| May-13 | |
| May-12 |
