TriSalus Misses Again And Cuts Guidance A Third Time, Overshadowing A Sequential Rebound And Favorable 2027 Reimbursement
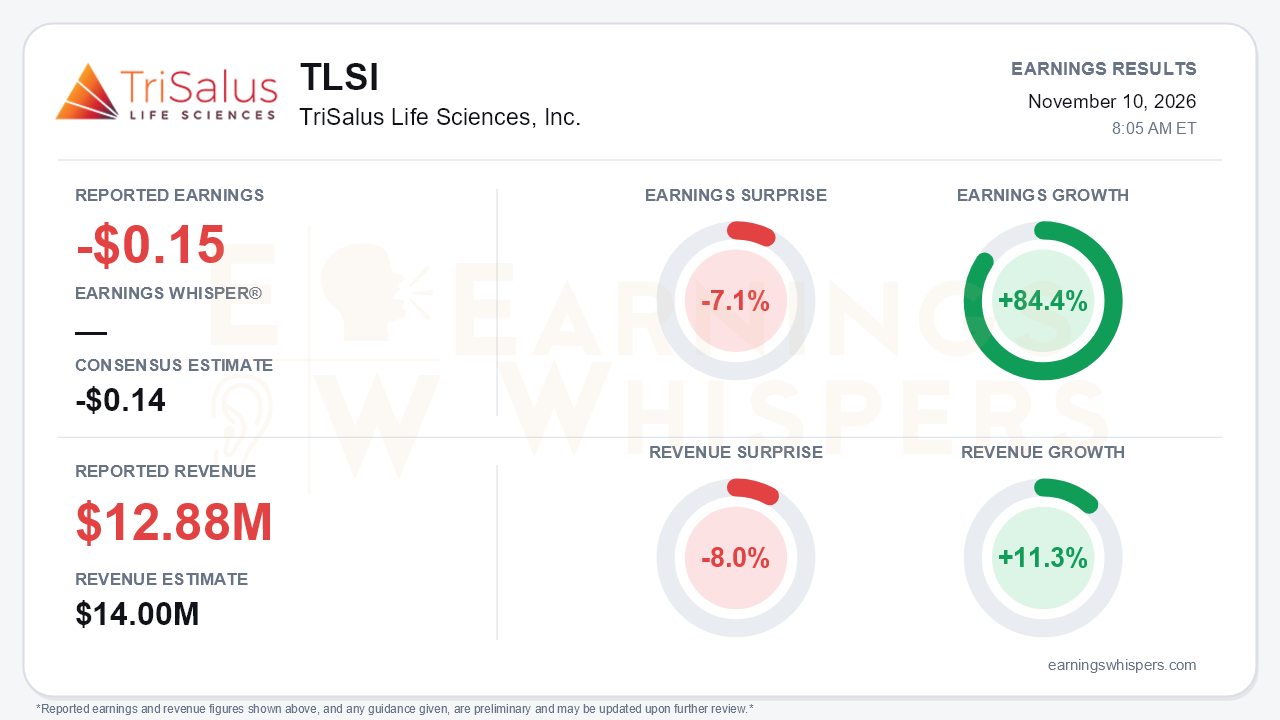
TriSalus Life Sciences (NASDAQ: TLSI) delivered a third quarter that improved on the second quarter but still fell short of Wall Street, and it then cut full-year guidance for the third consecutive call. The company lost $0.15 per share on revenue of $12.88 million. Consensus was a loss of $0.14 on $14.0 million in revenue, so EPS missed by 7.1% and revenue missed by 8.0%. Revenue grew 11.3% year over year, a clear acceleration from Q2's 1.7% growth and Q1's year-over-year decline. Sequentially, revenue rose 13% from $11.4 million. The central tension is that the business is recovering from a weak first half, but not nearly fast enough to justify the growth story management was telling investors as recently as August. Full-year 2026 revenue guidance is now $46 million to $48 million, or 2% to 6% growth. The prior range was $54 million to $57 million, and the original range was $60 million to $62 million, which implied growth in the mid-30s.
The 84.4% year-over-year EPS improvement looks impressive but says little about operations. Net loss attributable to common stockholders fell to $8.9 million from $41.3 million. Almost all of that swing reflects roughly $30.5 million of charges tied to last year's preferred-stock conversion, along with a share count that rose to 58.5 million from 43.1 million. The operating picture is more modestly positive. Gross margin rose to 86.2% from 83.5% on lower unit costs, though it slipped from 86.8% in Q2. Operating loss narrowed to $7.7 million from $9.0 million. Adjusted EBITDA loss improved to $4.7 million from $5.4 million a year ago and $7.1 million in Q2. Those gains came partly from cuts to R&D, which fell to $3.2 million from $5.7 million, while sales and marketing spending rose to $10.7 million from $6.8 million to support a field force that has more than doubled.
That sales expansion is the crux of the problem. Management admitted rep productivity is ramping slower than anticipated. The shortfall is concentrated in roughly a third of the field, about eight expansion territories. On the Q2 call, management had described those reps as "right on track" and promised a stronger fourth quarter. A new headwind also surfaced: a faster-than-expected shift toward super-selective Y90 procedures in small distal vessels, which legacy TriNav could not address. There were genuine positives. Ordering accounts grew double digits, September was the strongest month of the year for accounts and units, and rep attrition was described as virtually nil. Even so, the revised guidance implies fourth-quarter revenue roughly flat to up about $2 million sequentially, which is weaker than a typical seasonal step-up. Management's tone shifted from confident ramp language to defensive explanation.
The catalysts for 2027 are real and arguably the best part of the report:
- **TriNav Advance:** The device received FDA clearance in September after earlier delays and directly addresses the distal-vessel gap. It is only in limited release, however, and contributes nothing to the Q4 guide.
- **Hospital reimbursement:** CMS's final 2027 hospital outpatient rule raises the C8004 mapping payment to roughly $20,910. The release cites a prior rate of about $11,794, while the call cited about $11,874.
- **Office-based reimbursement:** CMS set national office-based payment under G0577 at about $13,800, above the proposed level. That opens an office-based lab channel slated for 2027.
- **Clinical data:** Interim PROTECT data in thyroid artery embolization remain on track for Q1 2027.
The risk is that the market has heard "wait for next year" before. 2027 guidance was deferred, and management would commit only to "meaningful double-digit growth," not the 25% to 30%-plus pace of the past.
The balance sheet adds pressure. Cash stood at $41.1 million, down from $46.3 million in Q2 and $56.6 million in Q1. Nine-month operating cash burn was $21.9 million, and the company carries $32.4 million in long-term debt. Its own risk language flags revenue requirements tied to accessing additional credit-facility funding, a meaningful issue for a company whose revenue targets keep moving lower.
Investors were already bracing for disappointment. Earnings Whispers sentiment deteriorated sharply, from -0.33 after the prior report to -0.80. Shares fell 34.8% from the $4.94 post-August open to $3.22, sit 25.9% below the 200-day moving average of $4.35, and closed the pre-report session essentially at the inter-earnings low of $3.21. That is 45.5% below the August 13 high of $5.91. The sequential growth trend reading is positive, consistent with the Q2-to-Q3 rebound, but price and AVWAP trends remain negative.
The bottom line is that TriSalus showed a business that has stopped decelerating on a quarterly basis, with better margins, narrower losses, and genuinely favorable reimbursement and product tailwinds for 2027. However, a third straight guidance cut, a missed promise on sales-force productivity, and steady cash burn have badly damaged management credibility. Bears have legitimate ammunition, and the stock's position at its lows shows that investors now want to see execution before they credit the 2027 story.
Read our earnings preview for TriSalus Life Sciences, Inc.: https://www.earningswhispers.com/article/TLSI/22712
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 1 hour | |
| 5 hours | |
| Nov-03 | |
| Oct-29 | |
| Oct-20 | |
| Sep-23 | |
| Sep-22 | |
| Aug-31 | |
| Aug-07 | |
| Aug-06 | |
| Aug-05 | |
| Jul-29 | |
| Jul-16 | |
| Jun-10 |
