Summit Midstream Crushes Estimates And Lifts Its Growth Outlook Again, But Thinning Cash Flow And Expiring Piceance Support Temper The Beat
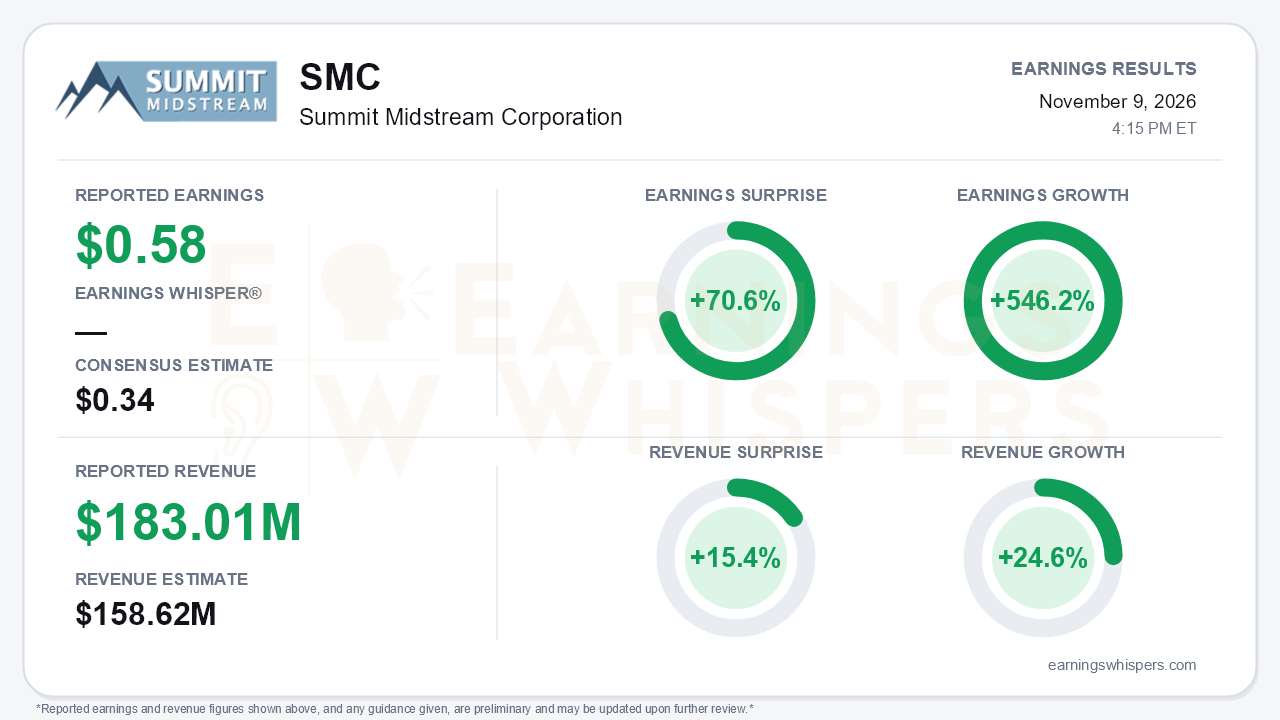
Summit Midstream Corporation (NYSE: SMC) delivered a decisive beat for the third quarter. Diluted earnings were $0.58 per share, against a consensus estimate of $0.34, a 70.6% surprise. Revenue of $183.01 million topped the $158.62 million consensus by 15.4% and grew 24.6% year over year. Earnings grew 546.2% from a year earlier, a swing from a $0.13 per-share loss in the year-ago quarter to solid GAAP profitability. Management paired the results with a second consecutive guidance raise, lifting 2026 Adjusted EBITDA to $250 million to $260 million from $235 million to $255 million. It also introduced a multi-year growth framework far more ambitious than anything it has previously offered. The operating story is accelerating. The central tension is that cash generation is moving the other way, and the stock has not given management the benefit of the doubt.
The quality of the EPS beat deserves scrutiny. GAAP net income of $15.9 million included a $5.0 million gain on asset sales and a $1.9 million gain on interest rate swaps, which together account for a meaningful share of pre-tax income. On the operating line, Adjusted EBITDA of $70.7 million was up 16% sequentially and up from $65.5 million a year ago. However, that figure included roughly $3.7 million of Rockies commercial billing settlements and $4.1 million of Piceance MVC shortfall payments. Those Piceance minimum volume commitments expired at the end of the quarter. Revenue growth was also amplified by commodity sales: natural gas, NGL and condensate sales rose to $98.1 million, but cost of natural gas and NGLs climbed in step. Gathering fees, up from $65.4 million to $75.9 million, are the cleaner measure of underlying growth, and they were still strong.
The underlying volume trajectory is genuinely impressive. Fifty-one well connects in the Williston and DJ basins drove liquids throughput up 40% sequentially to 95 Mbbl/d. Rockies segment EBITDA has climbed from $26.4 million in Q1 to $30.4 million in Q2 to $40.0 million in Q3. Double E hit a record 1,002 MMcf/d, versus 805 MMcf/d in Q1, and Mid-Con gas volumes rose 7% to 561 MMcf/d. More important for the forward story, the DUC inventory behind the system roughly doubled from about 75 to about 140. Management now expects 200 to 250 well connects in 2027, versus 116 to 126 expected this year. The Double E compression expansion reached final investment decision, and the Permian EBITDA target moved to more than $100 million by 2029, from about $60 million earlier in the year. Management also floated up to a 30% two-year Rockies EBITDA CAGR and a company-wide mid-to-high-teens Adjusted EBITDA CAGR. The tone on the call was clearly more confident.
Bears still have legitimate ammunition. Free cash flow slid from $11.4 million in Q1 to $9.4 million in Q2 to just $5.2 million, as contributions to Double E jumped to $10.9 million. Distributable cash flow fell to $32.6 million from $36.8 million in Q2. Operating cash flow was only $5.5 million, versus $26.7 million a year ago, as receivables swelled. Losing the Piceance MVC payments cuts roughly half that segment's quarterly EBITDA, which management guided to about $4 million to $4.5 million per quarter. Capex is tracking to the high end of the $100 million to $120 million range, and brownfield expansions such as Jackson Lake could push 2027 spending higher. The rig count behind the Rockies system was cited at six to seven, down from eight in Q2. Management acknowledged that producer plans could adjust if crude falls below $60.
The market setup is more complicated than the surprise implies. Investor sentiment remained positive but weakened sharply, falling from 0.37 to 0.07 heading into the report. Shares at $27.96 are down 11.8% since the open after the August report and sit 8.9% below the 200-day moving average of $30.68. The Earnings Whispers trend readings are mixed, with momentum positive but AVWAP still negative. Investors appear to be discounting oil-price exposure and the cash-flow squeeze more heavily than the raised EBITDA trajectory.
The balance-sheet path is the potential bridge between those views. Total net leverage improved to 3.9x from 4.1x in Q2. Management targets about 3.6x by year-end, a level it says opens the door to considering a common dividend in early 2027. A credible dividend reinstatement would convert the EBITDA story into something shareholders can actually collect.
The bottom line is that Summit's quarter strengthened the long-term growth case. The guidance raise, the expanded DUC backlog and the Double E commitments give that case real substance. Still, the headline beat leaned on gains, settlements and soon-to-expire MVC support, while free cash flow is shrinking just as capital needs rise. Until well connects visibly translate into cash flow and the dividend question is resolved, the stock's discount to its 200-day average reflects real skepticism rather than mere oversight.
Read our earnings preview for Summit Midstream Corporation: https://www.earningswhispers.com/article/SMC/22789
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-09 | |
| Nov-03 | |
| Nov-02 | |
| Sep-01 | |
| Aug-31 | |
| Aug-10 | |
| Jul-30 | |
| Jun-08 | |
| Jun-05 | |
| Jun-01 | |
| May-12 | |
| May-11 | |
| Apr-29 | |
| Mar-31 |
