Janus International Misses Badly And Cuts Guidance Again As Self-Storage Demand Breaks Down; Cash Flow Is The Only Line Holding
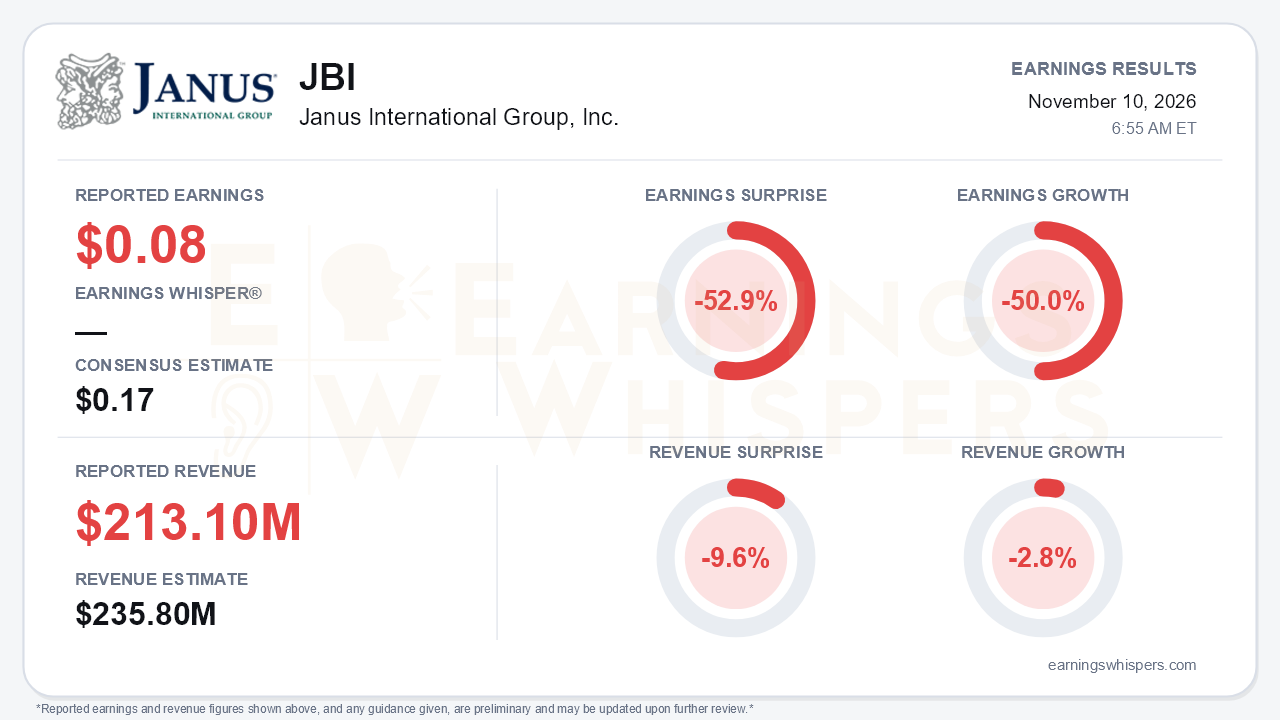
Janus International Group's third quarter was not a near-miss. It was a reset. Adjusted earnings of $0.08 per share came in 52.9% below the $0.17 consensus and fell 50.0% from a year ago. Revenue of $213.1 million missed by 9.6% and declined 2.8% year over year. On a GAAP basis the company swung to a net loss of $13.3 million, or $(0.10) per share, from a $15.2 million profit, partly because of an $18.3 million impairment of goodwill and tradenames tied to BETCO and the recently acquired Kiwi II Construction. Management cut full-year guidance for the second straight quarter. Revenue is now expected at $855-$865 million, down from $925-$945 million, and adjusted EBITDA at $127-$133 million, down from $150-$170 million. The central takeaway is that the self-storage slowdown bulls hoped was transitory is instead deepening, and management is no longer pretending otherwise.
The headline also flatters the organic picture. Revenue growth has gone from +5.8% in Q1 to +2.4% in Q2 to -2.8% now, and that trajectory includes $10.7 million of Kiwi II contribution. Strip out the acquisition and organic self-storage new construction fell 12.5%, versus flat in Q2. R3, the replacement and renovation business that had been a reliable bright spot (+6.6% in Q2), dropped 10.6% as owners deferred discretionary spending. Gross margin compressed roughly 600 basis points to about 33.1% on adverse mix away from high-margin North American self-storage. Adjusted EBITDA fell 22.0% to $34.0 million, with margin down 390 basis points to 16.0%. Commercial and Other grew just 2.3%, which is not enough to offset the deterioration in the core.
The call made the demand problem explicit. Steel costs are up 58% year over year and roughly 21% sequentially. Combined with rising rates and slower lease-ups, that is breaking developer project economics and causing some to halt planning of new facilities. The guidance implies Q4 volumes down roughly 20%. Management said it sees no evidence of improvement and does not expect a recovery into 2027. The tonal shift from Q2 is stark. Last quarter's talk of improving sentiment from larger customers and a sequentially stronger back half gave way to "the macro has gotten worse, not better" and "disappointing." The Kiwi II story has unraveled in parallel. Expected inorganic revenue has been cut from $90-$100 million to $80-$90 million and now to $55-$60 million, and the impairment followed a meaningful drop in the unit's first-year forecast.
The offsets are real but defensive:
- **Cash generation.** Free cash flow rose to $31.5 million from $21.6 million in Q2, and trailing free cash flow conversion of adjusted net income reached 203%. That figure is flattered by the shrinking denominator.
- **Cost savings.** A $10.8 million annualized program is in place, roughly half realized in 2026, with further actions flagged.
- **Product affordability.** Management is de-contenting products to make them cheaper for customers.
- **Noke.** Connected devices grew 19.4% to 524,000.
- **Capital return.** Janus repurchased about 5 million shares for $25.3 million and prepaid $30 million of its term loan.
Bears have legitimate ammunition here, though. Net leverage climbed to 2.9x from 2.7x last quarter and 2.1x at year-end. That puts it at the top of the 2-3x target, and the driver is falling EBITDA rather than new debt. Cash fell to $99.9 million and liquidity to $173.7 million. That likely constrains further buybacks. When asked about strategic alternatives, management said the board will "look at all options." That is notable phrasing, but it is not a commitment.
The market setup heading into the print was more constructive than the report justified. Investor sentiment improved sharply from -0.52 to roughly neutral at -0.03. Shares had rebounded 18.7% off a 52-week low of $4.01 set October 1. Even so, at $4.76 the stock was essentially unchanged from the $4.80 open after the August report, about 10% below its 200-day moving average of $5.30, and well under the $5.31 inter-earnings high set on that post-report day. The Earnings Whispers trend readings are mixed, with momentum negative while AVWAP is positive. A second consecutive guidance cut paired with an explicit no-recovery outlook challenges the improving expectations embedded in that sentiment shift.
The bottom line is that Janus delivered a miss on both lines and its second straight guidance reduction. The implied fourth quarter points to a business shrinking at an accelerating rate. Cash flow, cost cuts and buybacks provide some cushion, but rising leverage limits how far capital return can carry the stock. Until self-storage project economics improve, the investment case rests on cost control and balance-sheet discipline rather than growth.
Read our earnings preview for Janus International Group, Inc.: https://www.earningswhispers.com/article/JBI/22698
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 9 hours | |
| 11 hours | |
| 15 hours | |
| Nov-03 | |
| Oct-27 | |
| Sep-02 | |
| Aug-11 | |
| Aug-11 | |
| Aug-11 | |
| Aug-10 | |
| Jul-21 | |
| May-12 | |
| May-12 | |
| May-11 | |
| Apr-21 |
