Equinox Gold Beats On Orla-Fueled Scale, But Low-End Production And Above-Target Costs Temper The Senior-Producer Story
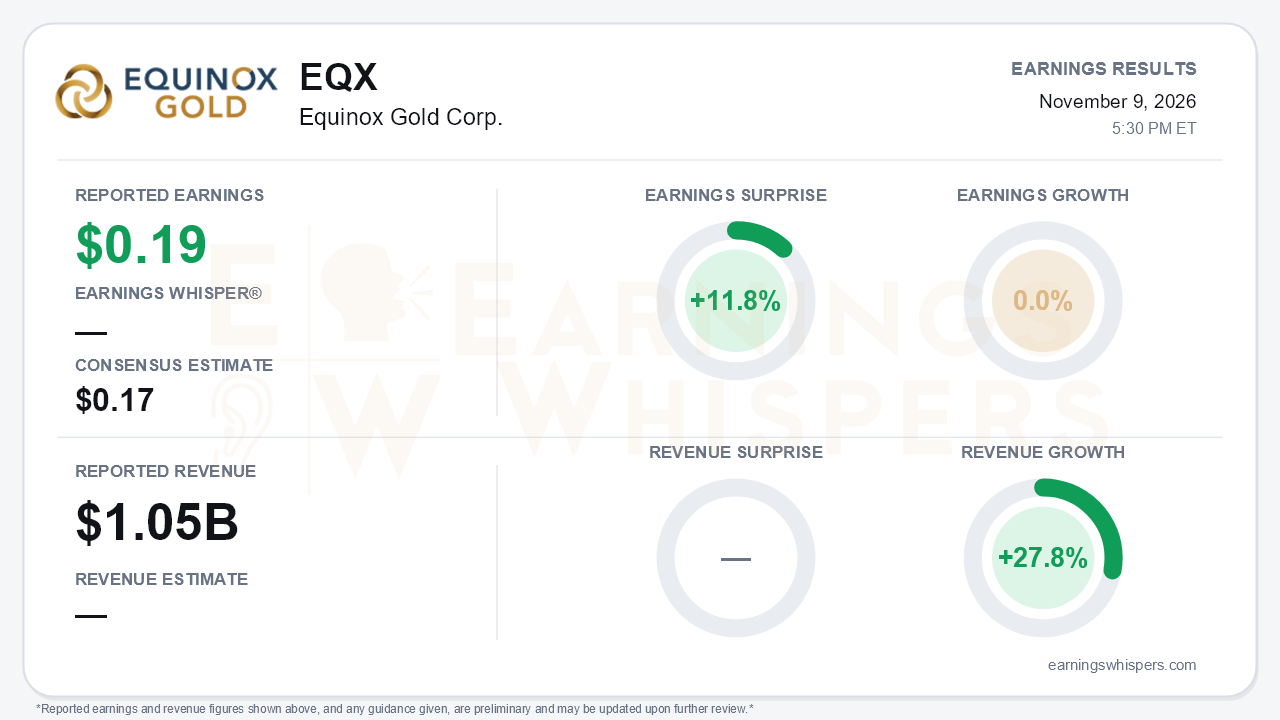
Equinox Gold delivered a clean headline beat in its first quarter as a combined company with Orla Mining. Adjusted earnings of $0.19 per share topped the $0.17 consensus by 11.8%, and revenue reached a record $1.047 billion, up 27.8% year over year, on 248,484 ounces sold at a realized $4,157 per ounce. Earnings growth was flat, however, at 0.0% year over year. That is the central tension. Scale and gold prices are lifting the dollar figures, but per-share earnings are not yet compounding. Guidance has also slipped toward the less comfortable end of the ranges management set only a quarter ago.
The quality of the beat deserves scrutiny on two fronts. First, dilution is absorbing the growth. Adjusted net income rose to $199.3 million from $139.9 million a year earlier, but diluted weighted shares climbed to roughly 1.05 billion from about 782 million. As a result, the bottom line barely moved per share. Second, the gap between adjusted and IFRS results is wide. GAAP net income was $62.5 million, or $0.06 per share, versus $0.10 a year ago. The difference reflects a $76.6 million fair-value adjustment on acquired Orla inventories, a $50.0 million warrant-liability charge, and $17.7 million of transaction costs. Most of these items are deal-related or non-cash, which supports the adjusted view. Even so, investors should not mistake the GAAP number for a clean quarter. The cash picture was stronger:
- Mine-site free cash flow before working capital jumped to $398.3 million from $223.7 million in Q2.
- Adjusted EBITDA hit a record $533.0 million.
On the cost side, the sequential direction was favorable. Cash costs fell 9% to $1,654 per ounce and AISC fell 4% to $2,091. The problem is the level rather than the direction. AISC remains above the $1,900-$2,000 range set in Q2, and nine-month AISC for guided mines is $2,061. Management says it remains on track for the high end of that range, which implicitly requires a meaningfully cheaper fourth quarter. On the call, management conceded costs are "higher than we would like." It cited fuel and broader inflation, launched cost-containment programs, and spoke of "responsible" 2027 guidance. That is a noticeably more guarded tone than in Q2, when the new ranges were framed as conservative. Production is now pointed to the low end of 870,000-920,000 ounces. Guided mines produced about 593,000 ounces through September, so Q4 has to be the strongest quarter of the year.
The asset-level story is a split decision. Musselwhite was the standout, producing 63,090 ounces on a full-quarter basis, running above 4,000 tonnes per day at 6.15 g/t, and pointing to a down-plunge extension and possible mill expansion. Valentine is improving:
- Grade rose 16% to over 1.8 g/t.
- September throughput ran 26% above nameplate.
- September output of 14,027 ounces was the mine's best month yet.
Still, Valentine's grade remains well short of the roughly 2.5 g/t plan, and selective mining is inflating costs. Greenstone moved backward. The HPGR replacement cut throughput to 23,682 tpd, the trommel slipped from a 2026 benefit to Q1 2027 commissioning, and recoveries remain around 80%. Mesquite added a fresh headwind from geotechnical instability in the Brownie pit.
The longer-term catalyst slate is genuinely richer, and the call preserved a credible growth story. New CEO Jason Simpson framed a path from roughly 1 million ounces toward 2 million in existing jurisdictions. Two growth projects advanced:
- South Railroad received its federal Record of Decision. Engineering is 71% complete and about $180 million of $395 million initial capital is committed, with first gold targeted for the first half of 2028.
- Valentine Phase 2 was approved at $436 million for completion in late 2028.
Los Filos could restart at roughly half its historical rate in 2027. The balance sheet supports these plans: about $1.3 billion of debt has been repaid year to date, net cash stands at $164 million excluding the now-converted notes, and buybacks have resumed alongside a 50% dividend increase. The offset is that cash fell to $528 million from roughly $650 million at the end of July, while two major builds are ramping.
The market has rewarded the transformation without fully embracing it. Shares are up 27.0% since opening at $9.52 after the August report, yet at $12.09 they still sit 4.5% below the 200-day moving average of $12.66. Investor sentiment edged up to -0.1417 from -0.1580. Sentiment is less negative, but skepticism clearly persists. The Earnings Whispers trend readings are mixed: sequential growth and momentum are positive, while the price and AVWAP trends remain negative.
The bottom line is that Equinox Gold has the scale, the balance sheet, and the project pipeline of an emerging senior producer, and the Orla assets, especially Musselwhite, are already pulling their weight. Execution on the legacy assets has not caught up. Near-term guidance has drifted lower, costs are above target, and Greenstone keeps slipping, so bears have legitimate ammunition until Q4 delivers the volume and cost relief that management's reaffirmed ranges now require.
Read our earnings preview for Equinox Gold Corp.: https://www.earningswhispers.com/article/EQX/22623
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-02 | |
| Oct-29 | |
| Oct-13 | |
| Oct-07 | |
| Sep-29 | |
| Sep-28 | |
| Sep-28 | |
| Sep-21 | |
| Aug-27 | |
| Aug-17 | |
| Aug-05 |
