Tidewater Misses Badly On EPS, But Accelerating Day Rates And A Bullish 2027 Guide Shift The Debate To Next Year
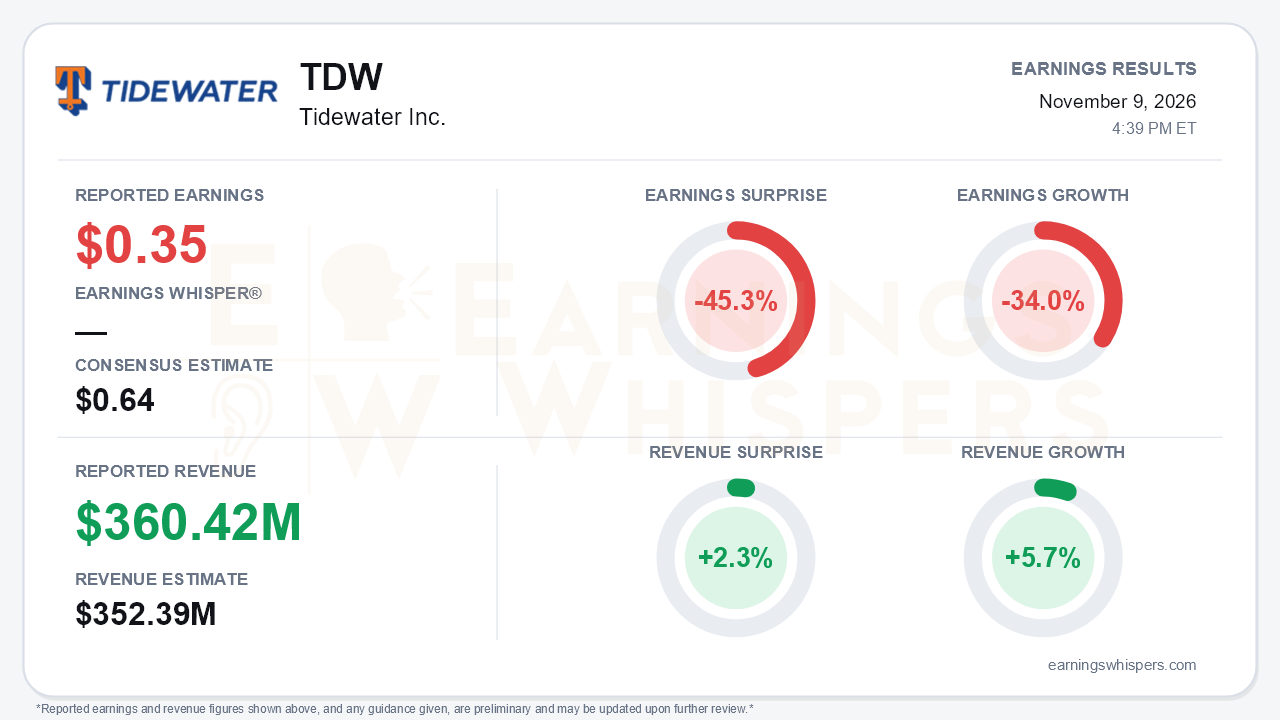
Tidewater's third-quarter report pairs a steep earnings miss with what may be its most constructive forward outlook in years. The offshore vessel operator earned $0.35 per share, 45.3% below the $0.64 consensus, and earnings fell 34.0% year over year on Earnings Whispers' normalized basis. On a GAAP basis, the year-ago quarter showed a $0.02 loss, distorted by a $27.1 million debt-extinguishment charge, so the year-over-year comparison is noisy either way. Revenue was cleaner. It reached $360.4 million, beating the $352.4 million consensus by 2.3%, rising 5.7% from a year ago and 5.3% sequentially. That is the central tension: 2026 earnings keep slipping, while pricing and the 2027 framework keep improving.
The quality of the miss deserves scrutiny, because most of it sits below the gross-margin line. Gross margin of 46.8% was flat with the second quarter but about a point above management's roughly 46% target. Adjusted EBITDA rose to $140.1 million from $135.5 million.
The damage came from several other lines:
- Operating income fell to $50.3 million from $62.5 million in the second quarter.
- Depreciation jumped to $47.0 million from $38.1 million after the $500 million Wilson Sons Ultratug Offshore (WSUT) acquisition closed September 1.
- Acquisition and integration costs reached $10.2 million.
- The company booked a $3.7 million foreign-exchange loss.
- Tax expense of $18.2 million consumed roughly half of pretax income.
Cash generation tells a better story. Free cash flow climbed from $34.4 million in Q1 to $64.4 million in Q2 and $90.9 million in Q3.
Pricing is the real headline. The average day rate rose $837 to $23,775, the third straight sequential gain. The weighted leading-edge term rate jumped 12.5%, or $3,033, to $27,373, accelerating from a 7.5% increase in Q2. Europe/Mediterranean drove the step-up: vessel revenue reached $121.5 million versus $83.7 million a year ago, and segment margin widened to 53.8% from 50.3% last quarter.
Other regions moved the other way. Active utilization slipped to 79.2% from 81.4%. Asia Pacific, the Middle East and West Africa each lost three to four points of margin sequentially. West Africa revenue has slid from $91.7 million in Q4 2025 to $73.0 million.
Management responded with initial 2027 guidance of $1.70 billion to $1.75 billion in revenue and 51% to 53% gross margin, with 64% of the revenue midpoint already in backlog. Leadership described production, subsea and drilling support all growing next year against tight vessel supply and rising secondhand PSV prices. Other catalysts include:
- **WSUT repricing:** the Brazilian contracts sit well below market rates, which offers a runway for higher pricing.
- **New awards:** Angola production contracts and Asia-Pacific drilling campaigns starting in Q2 2027.
- **Buybacks:** roughly $25 million of shares repurchased since the last report, with $475 million of authorization remaining.
Bears still have legitimate ammunition. The 2026 gross-margin guide has now been cut three times, from 49%-51% to 49%-50% to 47.5%-48.5%. That includes about 140 basis points of Middle East conflict costs, and only about $0.6 million of roughly $7 million in billable conflict costs has been collected. The revenue midpoint has also drifted down, from $1.455 billion to $1.435 billion. Additional near-term headwinds:
- Q4 faces a roughly 3% revenue drag from repair downtime, capacity reduction and softer Americas extension rates.
- Q1 2027 revenue is guided flat as drydock spending rises to about $147 million next year.
- Petrobras tendering has been delayed by Brazil's elections.
- Newbuild PSV deliveries have begun, and the Middle East may soften as vessels return.
- The 2027 guide embeds only about $2,700 per day of fleet rate uplift, below the $3,000 to $4,000 framing used earlier this year.
The balance sheet has also changed. Cash fell to $390.8 million from $613.5 million. Long-term debt rose to $803.6 million after the company assumed $214.9 million of Wilson debt, lifting net leverage to about 0.9x.
The market has treated the stock cautiously. Shares at $71.06 are 3.3% below the open following the August report and about 10.9% under the 200-day moving average of $79.78. Investor sentiment remains negative but improved meaningfully, rising from -0.50 to -0.32. That suggests expectations were already subdued heading into a quarter that delivered a headline miss alongside a stronger outlook. The Earnings Whispers trend readings are mixed: momentum is positive while AVWAP remains negative, consistent with a stock that has not yet been rewarded for its pricing gains.
The bottom line is that Tidewater's quarter was weak on reported earnings and another step down for 2026 margin expectations, but the call preserved a credible growth story built on accelerating leading-edge rates, rising free cash flow and a 2027 guide implying roughly 20% revenue growth with higher margins. The investment debate now hinges on execution. Integrating WSUT, repricing its Brazilian contracts and absorbing heavy drydock spending without further guidance erosion will determine whether investors believe the 2027 numbers after a year of repeated near-term cuts.
Read our earnings preview for Tidewater Inc.: https://www.earningswhispers.com/article/TDW/22846
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 9 hours | |
| Nov-09 | |
| Nov-09 | |
| Nov-04 | |
| Nov-03 | |
| Sep-22 | |
| Sep-01 | |
| Aug-31 | |
| Aug-31 | |
| Aug-12 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 | |
| Jul-28 | |
| Jun-25 |
