HighPeak Energy Crushes Estimates And Fixes Its Balance Sheet, But Shrinking Volumes And A Bigger Budget Temper The Story
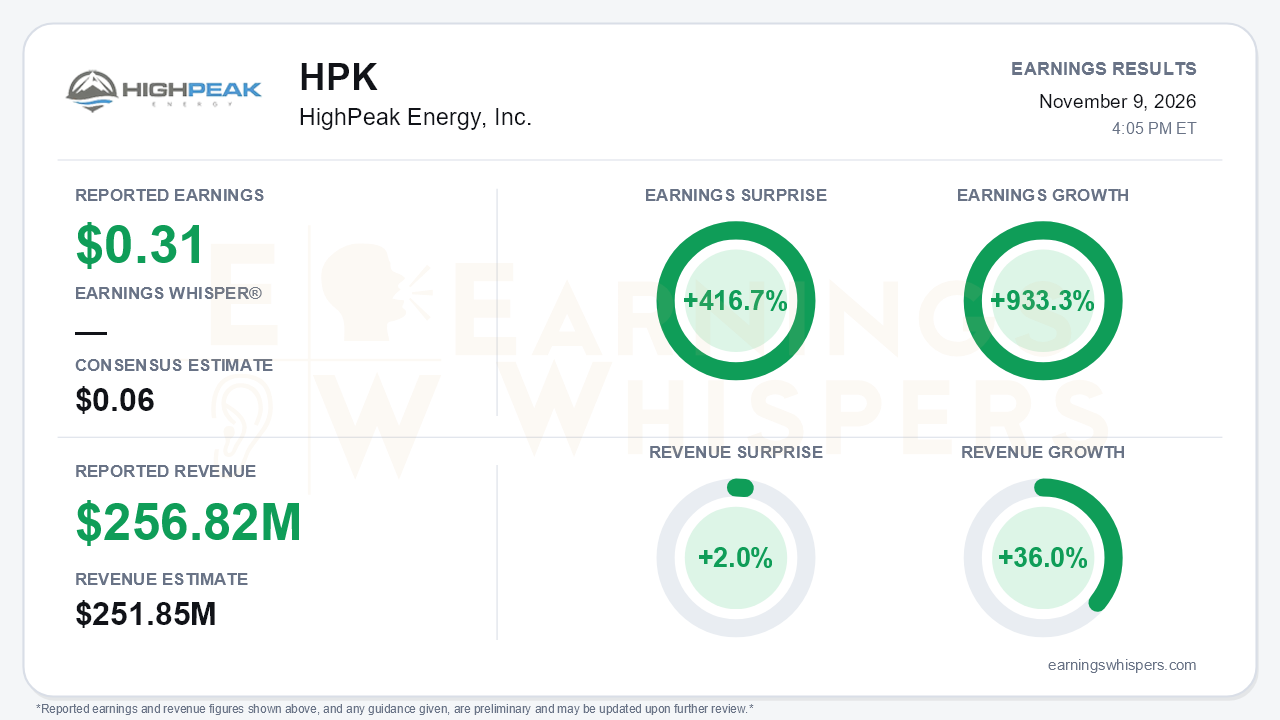
HighPeak Energy delivered a large third-quarter beat. Adjusted earnings of $0.31 per share came in far ahead of the $0.06 consensus, a 416.7% surprise. Earnings grew 933.3% year over year. Revenue rose 36.0% to $256.82 million, 2.0% above expectations. The company's own adjusted figure was $0.32, a penny above the normalized number. On a GAAP basis, HighPeak posted a net loss of $55.7 million, or $0.44 per share, wider than the $0.15 loss a year ago. The quarter's real headline, however, was not the beat. It was the refinancing announced in October, which roughly halves debt and reshapes the equity story. Weighed against that are operating trends that are flat at best.
The quality of the beat deserves scrutiny because price did nearly all of the work. Realized crude averaged $86.86 per barrel, up from $65.63 a year earlier. That lifted unhedged EBITDAX to $45.54 per Boe from $30.94. Meanwhile, total sales volumes fell to 44.2 MBoe/d from 47.8 MBoe/d, and oil volumes slid to 29,502 bbl/d from 31,594. Hedges absorbed a meaningful share of the upside. Including derivatives, realized crude dropped to $77.64, and the company booked a $107.5 million derivative loss, which explains the GAAP loss. Year-to-date cash paid on derivative settlements reached $93.5 million. The hedge book also matters going forward. Most 2027 swaps sit in the mid-$60s, well below recent realizations, which limits how much of any sustained oil strength reaches shareholders. On the positive side, cash generation improved materially:
- EBITDAX rose to $163.8 million from $139.9 million.
- Free cash flow before working capital was $58.4 million, versus $17.1 million a year earlier.
- Reported free cash flow was $22.4 million.
- Debt fell by $30 million.
The call marked a clear shift in tone. A year ago management had suspended the dividend and built a budget to survive mid-$50s oil. This quarter it described a transformational period and talked about optionality for 2027. The refinancing is the core of that change. A $450 million perpetual preferred investment and a new $800 million credit facility will retire the roughly $1.2 billion term loan, which carried a 10%-plus cost. Management expects:
- total debt to fall from about $1.17 billion to roughly $650 million;
- leverage to drop from 2.1x to about 1.2x;
- annual interest expense to decline by more than $50 million;
- maturities to extend to 2030, with liquidity above $180 million.
Operationally, the workover program has grown from 16 projects in Q1 into a primary driver of the production guidance raise. Full-year production guidance moved up to 44,500-45,500 Boe/d, and LOE guidance came down about 7% to $8.00-8.25 per Boe.
Bears have legitimate ammunition. The full-year capex budget rose to $310-320 million, against a midpoint of roughly $270 million implied on the Q1 call. Management framed the increase as reinvesting drilling efficiencies rather than releasing a rig, but it still erodes incremental free cash flow. Production is essentially flat in maintenance mode, and 2027 is signaled as similar activity. Sequentially, volumes have drifted down from about 46 MBoe/d in Q1. The workover gains also depend on supportive oil prices. The preferred carries a dividend obligation, and the sub-7% cost-of-capital math assumes that dividend is paid in cash. The refinancing has not yet closed and is expected by month-end. Two items flagged earlier were not revisited on the call: an oil cut that ran below guidance in Q2, and Waha gas takeaway exposure in late 2027-2028.
The market setup is more complicated than the surprise implies. Shares closed at $6.76 entering the report, down 17.8% from the $8.22 open after the August release and about 5.6% below the 200-day moving average of $7.16. That decline came even though the refinancing was announced in October. Investor sentiment remained positive but weakened, slipping from 0.41 to 0.29. Earnings Whispers trend readings are mixed: price momentum is positive, while sequential growth and AVWAP remain negative. That split fits a company whose balance sheet is improving faster than its production base.
The bottom line is that HighPeak delivered a strong, price-driven quarter and a genuinely transformative deleveraging that removes the balance-sheet overhang defining the stock for two years. The investment case now shifts from survival to execution. Investors will need to see the refinancing close, the higher capex budget produce more than flat volumes, and free cash flow hold up despite hedges that cap oil upside through 2027.
Read our earnings preview for HighPeak Energy, Inc.: https://www.earningswhispers.com/article/HPK/22634
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Nov-09 | |
| Nov-02 | |
| Oct-26 | |
| Oct-06 | |
| Sep-21 | |
| Aug-17 | |
| Aug-11 | |
| Aug-10 | |
| Jul-31 | |
| May-06 | |
| Apr-23 | |
| Apr-13 | |
| Mar-12 | |
| Mar-11 |
