HUYA's Buyback Bet Meets A Test: Can Game Publishing Outrun Fading Live Streaming?
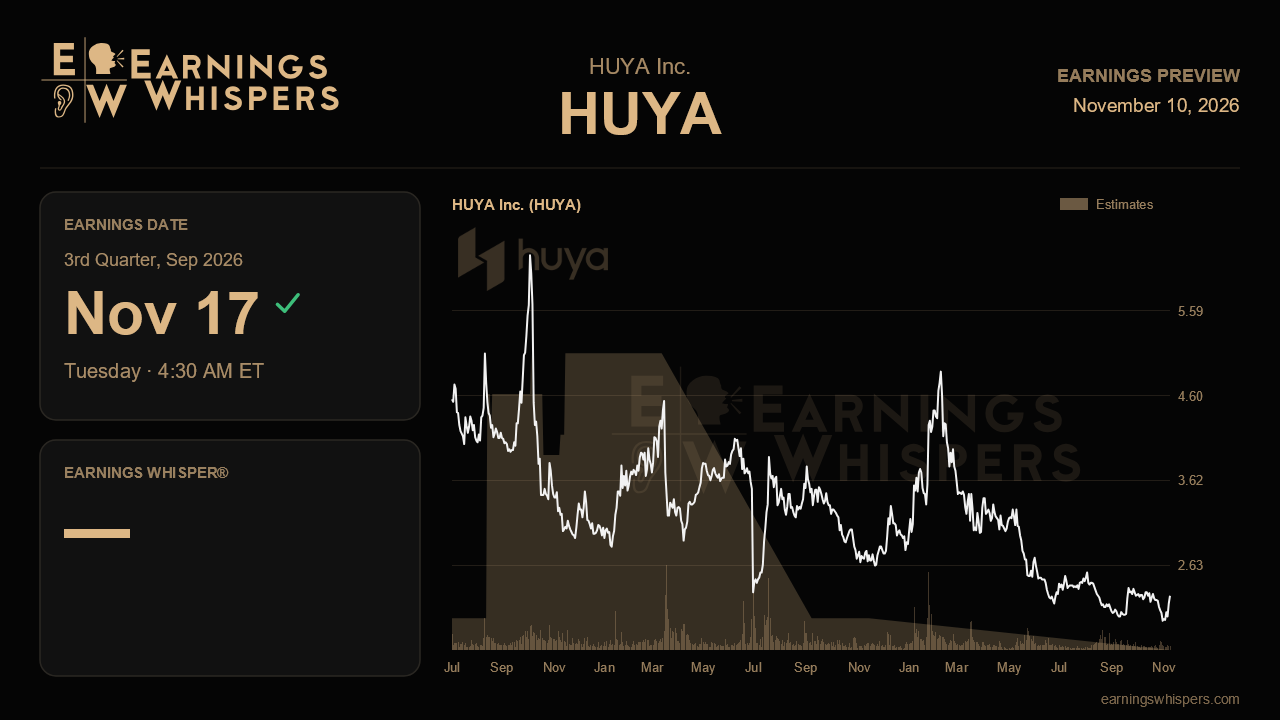
HUYA heads into its third-quarter report with a story that sounds better than its stock chart. Last quarter management showed rising profitability, a deepening game-publishing pipeline and a buyback expanded nearly sevenfold, yet the shares have fallen about 10% since then, trailing the S&P 500 by roughly seven percentage points. The November 17 release, due before the open, has to show whether the margin story can keep improving while the headline growth rate keeps slipping.
Usable Street forecasts are thin, and the company does not give formal numeric guidance, so the year-ago quarter is the cleanest benchmark. HUYA earned two cents a share on $237.1 million in revenue in that period, and it earned a penny last quarter on $256.3 million. Revenue growth has cooled from 16% in the fourth quarter of 2025 to 15% and then 11%. If the 11% pace simply held, third-quarter revenue would land near $263 million. Another step down in growth would suggest the deceleration is structural, while a stable rate would support the view that the business has found its footing.
The main question is mix. Game-related, advertising and other revenue rose to 37% of sales last quarter, up from about 31.5% a year earlier, and that shift has lifted gross margin to 14.7% and moved non-GAAP operating income to RMB16 million from a loss in the first quarter. However, growth in that segment slowed from 69% to 54%. Further share gains for these higher-margin businesses would confirm the thesis even if the segment's percentage growth keeps easing, because its comparisons are getting tougher. Signs of progress here would include continued triple-digit growth in in-game item sales, early revenue from the two newly exclusive titles, Legend of Swordsmen Reunion and Xiaoxiao Qiyu, and more advertising wins along the lines of the Hearthstone tie-in. The move from co-publishing to exclusive publishing matters because exclusive deals let HUYA keep more of the economics, though they also mean more upfront spending.
That spending is a swing factor. Sales and marketing jumped 58% year over year on Goose Goose Duck promotion. The game's return to the top of the iOS free chart in late July, helped by its Journey to the West and BDuck collaborations, should show up in the numbers this quarter. If marketing stays elevated without a clear lift in revenue, the operating leverage argument weakens. Readers should also look for updates on the planned WeChat minigame version and the timing of the first self-developed title.
Live streaming is the risk side of the ledger. That business still produces most of HUYA's revenue, slipped by a low-single-digit rate last quarter, and faces weak paying demand across the industry. Management said it would review the economics of its streaming partnerships in the second half. A tougher stance on content costs could help margins even if streaming revenue keeps shrinking, but a steeper drop would put more weight on the newer businesses than they may be ready to carry. Falling interest income, driven by a shrinking cash pile after dividends and buybacks, removes another source of support below the operating line.
Sentiment has improved, moving from mildly bearish before the last report to clearly bullish now, even as the stock trades at $2.28, well below its 200-day average of $2.79 and in the middle of its post-earnings range of $1.97 to $2.59. That gap between optimism and price is notable. The $100 million repurchase plan is large against a market value of roughly $554 million, and the pace of buying will show how seriously management means it. The report will ultimately be judged on one question: whether growth in publishing and game services, along with discipline on streaming costs, can keep operating profit rising while the core streaming business shrinks. If it can, the weak share price looks like an opportunity. If it cannot, the buyback looks more like support than a sign of confidence.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Oct-27 | |
| Oct-14 | |
| Aug-11 | |
| Aug-11 | |
| Aug-06 | |
| Jul-21 | |
| Jun-26 | |
| May-19 | |
| May-13 | |
| May-12 | |
| Apr-27 | |
| Apr-21 | |
| Mar-23 | |
| Mar-18 |
